



PW Consulting: Outdoor Warning & Mass Notification to Hit USD 4,584.9M by 2032, 7.42% CAGR

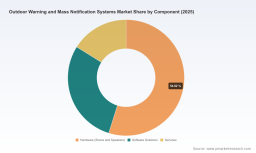
Outdoor Warning and Mass Notification Systems Market — Strategic Briefing for 2026 Decision Makers
As governments, critical infrastructure operators, campuses, and industrial sites reassess emergency preparedness in 2026, the outdoor warning and mass notification systems (OWMNS) market sits squarely on an investment inflection point. Our latest PW Consulting market study establishes a clear baseline: the market is forecast to expand from a 2025 estimated USD 2.78 billion to a materially larger footprint by 2032, tracking at a compound annual growth rate of approximately 7.4% over the 2026–2032 forecast window. For procurement leaders, security chiefs, and capital planners, this research is designed to convert that macro momentum into defensible, year‑one decisions.
Outdoor Warning And Mass Notification Systems Market
Why this study matters for 2026 planning
-
Regulatory and funding momentum is reshaping procurement priorities. Agencies are updating alerting taxonomies and procurement criteria to demand polygon-based, multi-channel alerting and closer integration with national alerting backbones. This creates immediate implications for device interoperability, firmware lifecycle, and message-design compatibility at the system level.
Outdoor Warning And Mass Notification Systems Market -
Technology transition is accelerating. Buyers are confronting choices between legacy electro‑mechanical sirens, IP-enabled giant‑voice arrays, long-range acoustic devices, and hybrid deployments that combine on‑premises control with cloud orchestration. Each option carries different operational tradeoffs — latency, resilience, cybersecurity posture, and lifecycle cost.
Outdoor Warning And Mass Notification Systems Market -
Market structure is neither a monopolist’s domain nor a scattershot cottage industry. Competitive intensity invites careful vendor selection: a small cluster of established manufacturers and systems integrators competes alongside regional and specialist suppliers. This structure favors buyers who use disciplined procurement frameworks to extract service guarantees, software roadmaps, and integration commitments.
What the PW Consulting report delivers
-
Operational procurement playbook — RFP templates and mandatory evaluation criteria aligned with current alerting standards and polygon-based delivery requirements, together with contract clauses that mitigate obsolescence risk and enforce software maintenance SLAs.
-
Decision frameworks — rapid assessment tools to size replacement versus retrofit options, including configurable TCO models that capture capital, installation, network, and lifecycle service costs across typical government and enterprise deployment profiles.
-
Technology roadmaps and integration checklists — vendor-agnostic guidance for integrating sirens, giant‑voice systems, IP‑speakers, and emergency management software with national alerting gateways and local sensor networks.
-
Vendor scorecards and scenario-based vendor shortlists — a reproducible methodology that scores suppliers on critical axes (voice intelligibility, network security, IPAWS/alerting compatibility, maintainability, and global support footprint) without exposing sensitive commercial intelligence in this executive summary.
-
Operational playbooks — deployment sequencing, commissioning and test protocols, community engagement templates, and exercises to validate end-to-end alert integrity under live conditions.
Market dynamics and strategic implications
The market is expanding steadily, driven by converging pressures: more frequent extreme weather events, heightened public‑safety expectations, and evolving regulatory baselines that standardize alert message formats and delivery mechanisms. Technology evolution is equally important — higher intelligibility voice platforms, encrypted networked sirens, and modular speaker architectures are increasingly table stakes for mid‑to‑large scale systems.
Three strategic implications stand out for 2026 decision makers:
-
Prioritize interoperability and lifecycle governance. With device and software obsolescence already a procurement risk, buyers who lock into closed ecosystems without end‑of‑life protections will face higher retrofit costs. Procurement should require vendor roadmaps and last‑time‑buy provisions as part of contract negotiations.
-
Adopt modular deployment strategies. Hybrid models that mix permanent, high‑power outdoor speakers with mobile trailers and targeted campus systems offer operational flexibility and faster time to coverage. These architectures balance capital intensity with responsiveness to changing threat geographies.
-
Account for cyber and operational resilience. Networked systems widen attack surfaces. Buyers must require proven security architectures, signed firmware updates, and third‑party vulnerability assessments as part of acceptance testing.
Competitive landscape — reading vendors through a strategic lens
The OWMNS landscape comprises legacy siren manufacturers, acoustic and giant‑voice specialists, global systems integrators, and regional manufacturers. Understanding where a vendor competes best — and where they are a risky choice — is essential for defensible selection.
-
Federal Signal Corporation (Oak Brook, Illinois) — A leader in community and industrial warning hardware with deep experience integrating high‑power sirens and giant‑voice systems. Notable for established IP-enabled product lines and government‑oriented certifications. Strategic buyers should probe lifecycle roadmaps and transition options when vendors announce product obsolescence to avoid surprise refresh cycles. ( https://www.fedsig.com/)
-
ATI Systems (Acoustic Technology Inc.) (North Billerica, Massachusetts) — Strong in high‑power speaker stations and voice‑clarity solutions for military, campus, and industrial sites. Their focus on networked and encrypted models suits defence and critical infrastructure customers with elevated security requirements. ( https://www.atisystems.com/)
-
American Signal Corporation (Atlanta, Georgia) — Offers high‑power electronic sirens with emphasis on intelligible voice and tone options for community, defence and industrial applications. Their product line-up is often selected where verified public address clarity is a procurement priority. ( https://www.americansignal.com/)
-
Genasys Inc. (formerly LRAD) (San Diego, California) — Specialist in long‑range acoustic devices and giant voice systems that deliver highly intelligible voice broadcasts over large distances; suited to large open areas and coastal communities where range and clarity are paramount. ( https://genasys.com/)
-
Whelen Engineering Company (Chester, Connecticut) — Known for warning sirens and integrated components for outdoor alerts, often selected where compatibility with legacy municipal systems matters. ( https://www.whelen.com/)
-
Telegrafia a.s. (Kosice, Slovakia) — A European specialist with strong international deployments; useful when buyers need proven European standards compliance and broad international service networks. ( https://www.telegrafia.eu/)
-
Systems integrators and multinational players — Honeywell, Eaton, and Siemens offer enterprise-grade integration of sirens with facility‑wide emergency communications; their value proposition centers on systems integration, lifecycle services, and the ability to incorporate OWMNS into broader building and industrial control ecosystems.
-
Regional and specialist manufacturers — A diverse set of suppliers (including several European and Asia‑based firms) supply compact rotating sirens, specialized signaling devices, and hazardous‑environment equipment. They can be cost‑effective for targeted deployments but require tighter verification of interoperability and long‑term support.
Recent industry signals worth watching into 2026
-
Product lifecycle events and targeted deployments show both continued replacement activity and selective modernization projects across counties and municipalities — a reminder that procurement teams must balance immediate coverage gaps with long‑term plans.
-
Vendors continue to invest in voice‑clarity and encrypted networked models; customers should request live intelligibility test results in environments that match their deployment conditions rather than accepting lab metrics alone.
-
Regulatory updates and national alerting platform changes are increasing the importance of compliance verification in procurement. Systems that lack timely firmware updates or integration paths risk being sidelined from funded modernization programs.
Practical 2026 actions — five priorities for decision makers
-
Run a 90‑day obsolescence audit of installed assets. Map which manufacturers and models are nearing end‑of‑life and quantify service and upgrade options to avoid emergency purchases later in the year.
-
Revise RFP templates now to mandate interoperability, firmware signing, and polygon-based alert capability. Include practical acceptance tests (two‑hour end‑to‑end live exercise) as pass/fail criteria.
-
Adopt a modular deployment strategy that pairs permanent high‑power assets with temporary/mobile units to manage capital exposure while improving near‑term coverage.
-
Request vendor roadmaps and service‑level commitments. Tie a portion of vendor compensation to demonstrated integration with national alerting gateways and timely security patch delivery.
-
Pursue coordinated funding strategies — align local capex plans with available grants and national programs and sequence projects to maximize matching funds while minimizing duplicate work.
How PW Consulting’s research supports your 2026 playbook
This study is deliberately structured as a practitioner’s briefing: it surfaces the macro trend lines, provides the procurement instruments and test protocols you need, and models the financial choices most commonly faced in 2026. To honor the “trailer” principle, we present the decision‑grade frameworks and competitive context here to enable rapid prioritization — the segment-level demand matrices, vendor scorecards, and downloadable raw datasets are reserved for the full report and online data portal. That level of granularity is essential for defensible vendor selection and capital approvals.
For procurement leads and operational commanders who must convert the market’s 7.4% CAGR and multi-year growth into measurable outcomes this year, our top recommendation is simple: combine a short-term, risk‑reduction retrofit plan with a medium-term modernization roadmap that locks software and service stability into contracts. If you are preparing an RFP, commissioning an audit, or building a capital plan for 2026, PW Consulting’s full report provides the sector‑specific scoring rubrics, contract language, and scenario models you will need to move from intent to executed projects.
Access the full report to unlock the complete vendor matrices, regional demand models, and downloadable datasets that support 2026 procurement and strategic investment decisions.
For detailed analysis of this topic, please visit the official page: Outdoor Warning And Mass Notification Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


