



PW Consulting: Hydrolyzed Formula Market to Hit USD 6,980M in 2025 with 8.8% CAGR

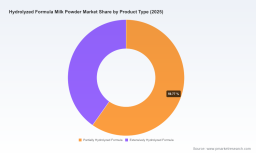
Hydrolyzed Formula Milk Powder Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted, action-oriented briefing on the hydrolyzed formula milk powder market that frames the commercial and regulatory landscape executives must navigate in 2026. This piece is a “trailer” — designed to demonstrate the methodological depth and strategic line-of-sight our full market study provides, while intentionally withholding the granular segment tables and proprietary model outputs that are included only in the full report.
Hydrolyzed Formula Milk Powder Market
Market snapshot: growth trajectory and structural context
The hydrolyzed formula market has moved from a sizable niche to a mainstream, strategically important segment within early-life nutrition. Our base-year analysis shows the market expanding from approximately USD 4.75 billion in 2020 to about USD 6.98 billion in 2025. Under our central forecast, the market is expected to grow at a robust compound annual growth rate (CAGR) of 8.8% through the forecast window, reaching an estimated USD 12.6 billion by 2032. This trajectory underscores two simultaneous forces: a persistent clinical and consumer demand for hypoallergenic and tolerance-improving formulas, and continued commercialization and geographic expansion by major CPG and ingredient players.
Hydrolyzed Formula Milk Powder Market
The market is structurally concentrated: the top three manufacturers account for the majority share, and the top five capture an even larger proportion — creating a high-barrier environment for standalone entrants but a favorable one for suppliers, private-label manufacturers, and value-accretive consolidation playbooks.
Hydrolyzed Formula Milk Powder Market
Why the 2026 decision calendar is pivotal
- Regulatory inflection points demand strategic re-alignment. Changes in regulatory classification, nutrient requirements, and permitted ingredient lists alter R&D priorities, label claims, and timelines to market. 2026 is the first full year in which several critical regulatory updates take effect, making immediate compliance planning essential.
- Ingredient sourcing and cost volatility are now core strategy levers. Established dairy-derived hydrolysates continue to dominate ingredient supply chains; securing long-term access to high-quality whey and milk hydrolysates is a competitive advantage and a risk mitigation necessity.
- Channel and premiumization strategies diverge. Growth is being captured simultaneously in clinical-use products and in premium/organic positioning; players must decide whether to chase clinical differentiation, premium consumer segments, or a dual-track approach supported by channel segmentation.
- Consolidation and private label create margin compression pressures. Retailers and contract manufacturers are leveraging cost leadership and store-brand strategies in multiple markets — prompting incumbents to sharpen portfolio economics and clinical evidence strategies to protect ASPs.
Regulatory and ingredient dynamics to factor into 2026 plans
- Regulatory updates. The European Commission’s late-2025 amendment to protein requirements for formulas based on hydrolysates redefines composition categories and permitted protein sources effective January 2026. Concurrently, U.S. regulatory practice continues to constrain permissible labeling and product claims (including controlled descriptions related to atopic dermatitis and hypoallergenicity) and enforces comprehensive nutrient and safety requirements for any formula sold domestically. These shifts increase the value of a living regulatory compliance map tied to product roadmaps.
- Ingredient concentration. Milk-based hydrolysates — particularly whey protein hydrolysates — maintain dominant share in ingredient consumption due to established dairy supply chains and their suitability for infant nutrition formulations. For 2026 planning, this means procurement strategy (long-term contracts, dual-sourcing, and supplier partnerships) and ingredient-traceability investments should be prioritized.
- Clinical evidence and label permissions. The regulatory environment rewards robust clinical evidence linked to specific formulations. Companies that can combine credible clinical research with permissible, nuanced label claims will enjoy sustained commercialization advantages.
Competitive landscape: what the leaders are doing (and what that implies)
The competitive field is composed of diversified nutrition majors, regional specialists, ingredient suppliers, and private-label manufacturers. The market’s concentration around a small set of global leaders creates distinct strategic dynamics: scale benefits for clinical R&D and manufacturing, and specialization opportunities for ingredient and regional players.
- Nestlé (Vevey, Switzerland). Nestlé’s extensively hydrolyzed offerings combine deep clinical positioning with global distribution muscle. Their strategy emphasizes proven hypoallergenic formulations and broad market availability. For challengers, this raises the bar on evidence generation and on claims discipline; for suppliers, Nestlé represents a high-volume, quality-focused customer.
- Danone / Nutricia (Paris, France). With extensive hydrolyzed brands and an expanding U.S. footprint, Danone focuses on clinical differentiation and global rollouts supported by channel muscle in both pharmacy and hospital segments. Competitors should expect aggressive geographic expansion from Danone in clinical channels.
- Mead Johnson / Reckitt (Evansville, USA). Their Nutramigen line underscores an emphasis on clinically oriented positioning and tailored formulas for complex indications. Reckitt’s route-to-market strength in HCP channels and training programs is an execution model to watch.
- Abbott Nutrition (Abbott Park, USA). Abbott capitalizes on strong brand recognition and a balanced portfolio that spans mainstream hypoallergenic products to specialized clinical powders. Their U.S. market presence and regulatory familiarity create high entry costs for new entrants seeking hospital or HCP endorsements.
- Perrigo (Dublin, Ireland). As a leading manufacturer of private-label and store-brand hydrolyzed formulas, Perrigo represents the principal margin-compression threat. Retailers and contract manufacturers leveraging scale will continue to pressure branded players’ value propositions.
- Meiji Group (Tokyo, Japan). Meiji’s regional focus and deep insights into Asian infant nutrition preferences translate into product variants optimized for local tolerance and flavor expectations — an important playbook for regional champions.
- HiPP (Germany), Arla Foods Ingredients (Denmark), FrieslandCampina (Netherlands). HiPP leads with organic and hypoallergenic positioning; Arla and FrieslandCampina are critical upstream partners supplying specialized hydrolysates. Ingredient suppliers wield outsized influence over formulation innovation, margin models, and supply continuity.
Collectively, these firms demonstrate three competing strategic archetypes: (1) clinical and evidence-led global incumbents, (2) regional/resolution players optimizing local taste and regulatory fit, and (3) cost/scale private-label operators compressing price-sensitive segments. Your 2026 roadmap should explicitly choose which archetype — or combination — you will align with.
What PW Consulting’s full report delivers (practical components)
Our comprehensive study is structured to convert insight into action. Highlights include:
- Granular market sizing and forecast models (2020–2032) with scenario sensitivity for regulatory and raw-material shocks.
- Competitive intelligence dossiers for each major player, including product portfolios, channel strategies, manufacturing footprints, and recent go-to-market moves.
- A regulatory compliance matrix mapping jurisdictional differences, claim-permissibility, and transitional timelines through 2026–2028.
- Ingredient supply-chain maps and risk scores, including supplier concentration, traceability, and cost pass-through modeling.
- Commercial playbooks: SKU rationalization templates, price-elasticity testing procedures, private-label defense strategies, and e-commerce acceleration plans.
- M&A and partnership screening tools that identify bolt-on capabilities (ingredient tech, clinical assets, regional manufacturing) and provide high-level valuation gates.
- Operational roadmaps for scaling production safely and compliantly, including recommended quality-management KPIs and traceability investments.
Note: While this preview outlines the study’s analytical architecture, the proprietary segment-level tables, region-by-channel revenue matrices, and downloadable financial models are withheld here to preserve actionable exclusivity available in the complete deliverable.
Prioritized actions for executives in 2026 (90–180 day plan)
- Regulatory readiness sprint. Establish a cross-functional regulatory task force to map new EU protein-category rules and U.S. label constraints against your product portfolio. Fast-track reformulations where necessary to avoid distribution interruptions.
- Secure ingredient continuity. Negotiate multi-year supply agreements with tier-1 hydrolysate suppliers and identify qualified secondary sources. Build ingredient buffers and ingredient-substitution decision rules into your ERP.
- Rationalize SKUs by channel. Rapidly assess SKU economics across hospitals/HCP, pharmacy, e-commerce, and retail to eliminate low-margin variants and redeploy CAPEX to high-return SKUs.
- Invest selectively in clinical evidence. Prioritize clinical studies that unlock permissible claims or HCP endorsements in target geographies — a relatively modest investment that can materially defend price realization.
- Prepare for private-label pressure. Develop a differentiation playbook (e.g., traceability storytelling, ingredient provenance, clinical endorsements) and consider strategic OEM partnerships to capture private-label volumes without brand dilution.
- Audit manufacturing compliance and scale capacity. Ensure all facilities meet the tightened documentation and nutrient-specification regimes and model incremental capacity needs through 2027.
Final perspective
The hydrolyzed formula milk powder market presents an attractive growth runway driven by medical demand, formulation innovation, and geographic expansion — but it is being re-shaped by regulatory updates and supply-chain dynamics that will determine winners and laggards in 2026 and beyond. The combination of high concentration among incumbents and the growing importance of upstream ingredient control means that strategic moves today (regulatory-planning, ingredient contracting, SKU and channel choices, and focused clinical investment) will disproportionately determine commercial outcomes over the next three to five years.
PW Consulting’s full report delivers the granular segment analytics, scenario models, and execution templates you need to convert this outlook into a defensible 2026 strategy. To access the complete dataset, models, and tailored strategic recommendations, please visit our report page or contact your PW Consulting representative for the full deliverable and a confidential walk-through of the findings.
For detailed analysis of this topic, please visit the official page: Hydrolyzed Formula Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


