



PW Consulting: Cellular Base Station Antenna Market Poised to Accelerate at a 15.0% CAGR, Reshaping Telecom Infrastructure Through 2032

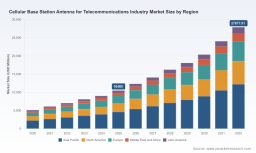
Cellular Base Station Antenna for Telecommunications Industry Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on Cellular Base Station Antennas positions stakeholders to make decisive 2026 investments in antenna technologies, deployment models and supplier strategies. The market has reached a material scale—exceeding USD 10.4 billion in 2025—and, with a compounded annual growth rate (CAGR) of 15.0% over the 2026–2032 forecast window, is projected to more than double by the end of the decade. This growth is being driven by the confluence of 5G densification, Massive MIMO rollouts, multi-band modernization and a renewed regulatory push to accelerate network upgrades.
Cellular Base Station Antenna For Telecommunications Industry Market
Why this matters in 2026
-
Near-term decisions (procurement, vendor selection, spectrum strategy, and capital allocation) will lock in operator performance and cost profiles for multiple technology cycles.
Cellular Base Station Antenna For Telecommunications Industry Market -
Supply-chain resilience, modularity of antenna systems (active vs. passive and hybrid designs), and energy efficiency will determine total cost of ownership (TCO) over the next seven years.
Cellular Base Station Antenna For Telecommunications Industry Market -
Regulatory developments and industry standards released through 2025–2026 create windows of opportunity—and risk—for rapid deployments, especially where spectrum repurposing and streamlining of local permitting are in play.
Market trajectory and what the headline numbers hide
The market’s headline trajectory—strong mid-teens CAGR and an expected multi-fold increase by 2032—signals both opportunity and complexity. While aggregate growth is robust, it masks heterogeneity in technology adoption, deployment formats (macro vs. small cell vs. distributed antenna systems), and supplier concentration. Our report quantifies these differences and situates them against cost, performance, and policy levers, but deliberately refrains from disclosing detailed segment tables in this preview to preserve the report’s role as the primary source for procurement- and investment-grade intelligence.
Report scope — practical, tactical, and decision-ready
This study is designed for executives who need to translate market dynamics into executable plans. Key operational deliverables included are:
-
Actionable procurement playbooks that map antenna type and architecture choices to CAPEX/OPEX scenarios and expected performance outcomes.
-
Vendor scorecards and supplier risk assessments, incorporating manufacturing footprint, compliance posture and product roadmap alignment.
-
Deployment-scenario modeling that tests outcomes under alternative spectrum rolls, permitting regimes and densification rates.
-
Technology-readiness timelines and integration guides for Massive MIMO, multi-band and small cell deployments to inform R&D and field trials.
-
TCO calculators and retrofit vs. greenfield decision frameworks to prioritize investments across macro sites, mid-band densification and capacity overlays.
Competitive landscape — concentrated but fast-evolving
The antenna market is meaningfully concentrated: the top three suppliers command a majority share, with the top five consolidating an even larger portion of market value. This concentration shapes bargaining dynamics, product roadmaps and cross-vendor interoperability considerations that operators must manage as they modernize networks.
Leading vendors profiled in the report include global incumbents and specialized manufacturers:
-
Huawei Technologies Co. Ltd. (Shenzhen) — A broad portfolio spanning passive and active antenna systems, with particular strength in high-port-density Massive MIMO and energy-efficient designs for macro deployments.
-
Ericsson AB (Stockholm) — Integrates antenna systems tightly with radio access infrastructure, offering solutions that emphasize multi-band and hybrid passive/active approaches under its Ericsson Antenna System (EAS).
-
Nokia Corporation (Espoo) — Focuses on multi-band and Massive MIMO antennas optimized for both dense urban and rural scenarios, with integration into AirScale platforms.
-
CommScope (Claremont, NC) — Offers scalable antenna and RF architectures, including hybrid LTE/5G configurations and distributed antenna systems for diverse topologies.
-
Other notable players profiled include Amphenol Antenna Solutions, Comba Telecom, Rosenberger, Radio Frequency Systems, ACE Technologies, Tongyu Communication, Kathrein (now part of Ericsson), PROSE Technologies, JMA Wireless, Alpha Wireless and HUBER+SUHNER. Each is evaluated on product breadth, geographic reach, manufacturing footprint and sustainability credentials.
Competitive moves and standardization trends to watch
-
Industry coordination gained momentum with the NGMN Alliance’s updated recommendations for base station antennas (V13.0), simplifying the language and interoperability requirements for passive, active and hybrid systems—critical for multi-vendor deployments.
-
Market entrants and incumbent R&D continue to prioritize compact, energy-efficient Massive MIMO RUs and antenna-integrated radios; late-stage announcements show suppliers optimizing throughput per watt and reducing RU size for easier rooftop and tower installations.
-
Supplier consolidation and ecosystem partnerships—especially between radio OEMs and antenna specialists—are accelerating to deliver turnkey solutions and to address installation and maintenance cost pressure.
Regulatory and deployment dynamics shaping 2026 choices
Recent regulatory actions materially influence deployment economics and speed. US regulatory developments in late 2025 and early 2026 aim to streamline siting and modernization processes, and proposed repurposing of upper C-band spectrum creates new capacity opportunities for terrestrial 5G. These moves lower barriers to densification but also create timing risks for spectrum-dependent deployment plans.
At the same time, high installation and maintenance costs remain a brake on densification. Operators will need to balance densification cadence against spectrum availability, energy consumption and workforce constraints. Notably, passive antenna improvements continue to deliver tangible user-edge throughput gains and energy savings—metrics that should be factored into architecture selection.
Strategic implications and recommended actions for 2026
PW Consulting recommends that organizations use 2026 as a window to shift from tactical rollouts to strategic platform choices. Key actions include:
-
Adopt modular antenna architectures that enable incremental capacity upgrades without full rooftop replacements; prioritize solutions that offer field-upgradeable RF and digital beamforming capabilities.
-
Recalibrate procurement to include lifecycle energy and site O&M costs, not just upfront hardware prices; apply our TCO models to compare active vs. passive trade-offs under operator-specific traffic profiles.
-
Lock in supplier diversity and geographic manufacturing balance to hedge against component and logistics disruptions; use the report’s vendor scorecards to identify second-source candidates and partnership risks.
-
Engage proactively with regulators and standards bodies to accelerate permitting reforms and to secure favorable treatment for densification-friendly spectrum policies.
-
Initiate targeted lab and field trials on multi-band Massive MIMO and small-cell integrations to validate vendor claims and to streamline commercial rollouts.
How the report supports boardroom and investment decisions
Boards and investment committees will find the report useful for prioritization, scenario planning and M&A screening. Our concentration analysis and supplier profiles surface both strategic acquisition targets and potential antitrust sensitivities. Scenario modules enable users to overlay different spectrum and permitting outcomes to understand upside and downside to revenue and margin projections through 2032.
What is deliberately withheld here — and why
This preview is intended to demonstrate the report’s strategic depth while preserving the proprietary segmentation tables, regional and application breakdowns, and the granular vendor market-share schedules that are essential for procurement and investment decisions. These detailed datasets—along with interactive models and client-specific advisory options—are available in the full PW Consulting report and through our analyst engagements.
Next steps and how to engage
-
Operators: commission a tailored workshop to map the report’s TCO and scenario outputs to your site estate and spectrum portfolio.
-
Vendors and suppliers: request a complementary vendor benchmarking call to understand relative positioning and partnership opportunities.
-
Investors and advisors: access the report’s strategic M&A pipeline analysis and concentration metrics to refine transaction risk models.
Closing
As 2026 unfolds, antenna strategy will be a pivotal determinant of network economics and competitive differentiation. PW Consulting’s Cellular Base Station Antenna for Telecommunications Industry Market report combines forecast rigor, supplier intelligence and executable tools to turn market growth and regulatory movement into concrete, defensible actions. For the full dataset, vendor scorecards, and scenario models that support high-stakes procurement and investment decisions, please consult the full PW Consulting report and contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Cellular Base Station Antenna For Telecommunications Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


