



PW Consulting: Global Packaged Baked Goods Market Poised to Reach USD 907.6 Billion by 2032, Growing at a 5.15% CAGR

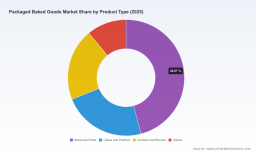
Packaged Baked Goods Market — 2026 Strategic Brief
Executive summary
The global packaged baked goods market is at an inflection point. Our PW Consulting Packaged Baked Goods Market Report (base year 2025) shows the market expanding from roughly USD 512.5 billion in 2020 to about USD 638.6 billion in 2025, and we forecast continued growth at a compound annual growth rate (CAGR) of approximately 5.15% through 2032. By the end of the forecast window the market is expected to approach the vicinity of USD 907.6 billion (nominal terms).
Packaged Baked Goods Market
That headline growth masks a complex mix of opportunity and risk. Growth is real and multi‑channel, but the industry remains structurally fragmented (the top three and top five players together account for a relatively modest portion of total market value), leaving space for nimble global players, regional champions, private-label consolidators and local innovators to pursue differentiated value propositions. The report synthesizes these dynamics into actionable frameworks for leadership teams planning 12–36 month strategies.
Packaged Baked Goods Market
Why this report matters for 2026 decisions
-
Strategic resource allocation: In a market growing at a mid-single-digit CAGR, differentiation and capital discipline determine who captures the upside. Our report translates macro demand into investment priorities—product innovation, channel expansion, manufacturing footprint and M&A screening—so CFOs and GMs can set capital spending and SKU portfolios with confidence.
Packaged Baked Goods Market -
Risk management: Recent supply‑chain, regulatory and quality incidents highlight vulnerability to raw‑material swings and compliance gaps. The report’s stress‑test models and scenario playbooks let procurement and operations teams quantify the P&L impact of wheat price moves, tariff shifts and recall events.
-
Regulatory readiness: With new labeling proposals and packaging EPR policies gaining traction, product and packaging roadmaps must incorporate compliance timelines. The report aligns reform scenarios with SKU rationalization and packaging investment plans to avoid costly last‑minute redesigns.
-
M&A and portfolio optimization: Given low market concentration, acquisitions and joint ventures remain effective routes to accelerate scale in targeted geographies or channels. Our M&A screening matrix prioritizes targets by strategic fit, integration risk and value creation potential.
Report contents — what executives will find inside
-
Market sizing and forecast (2020–2032) with scenario layers: baseline, upside (premiumization & convenience acceleration) and downside (supply shocks & regulatory headwinds).
-
Competitive mapping and capability heatmaps for global and regional players, including channel strength, innovation velocity and manufacturing footprints.
-
Go-to-market playbooks for retail, convenience and e‑commerce channels—practical tactics for pricing, promotion cadence, distribution economics and digital assortment management.
-
Supply‑chain stress tests: constructible models showing the impact of raw‑material inflation, tariffs and logistics cost shocks on margins and working capital.
-
Regulatory impact matrix: timelines and cost implications for proposed front‑of‑package nutrition labeling, EPR rules and regional packaging bans, with recommended compliance pathways.
-
Innovation and NPD frameworks: consumer insight arcs, SKU rationalization templates, rapid prototype-to-shelf process and cost‑yield levers.
-
M&A playbook and business case templates: valuation heuristics, integration checklists and 100-day plans for tuck‑ins and capability buys.
-
Executive dashboards and an interactive model (subscriber access): downloadable tools to run “what‑if” analyses against pricing, input cost and channel-mix scenarios.
Competitive landscape — who to watch and why
The market exhibits a mix of global platform players, regionally dominant bakers, ingredient and frozen specialists, and high‑growth challengers. Key incumbents profiled in the report include Grupo Bimbo, Mondelēz International, Flowers Foods, General Mills, Yamazaki Baking, Associated British Foods, Campbell Soup Company, Hostess Brands, Aryzta, Warburtons, Britannia Industries, Nestlé, McKee Foods and Rich Products. Each presents a distinct strategic posture — scale and distribution strength, brand portfolio breadth, or channel specialization — and the report maps those postures against opportunity windows for competitors and partners.
-
Global platform leaders (e.g., Grupo Bimbo, Mondelēz, General Mills): have the distribution muscle and R&D engines to drive rapid product rollouts but face margin pressure from rising input costs and channel shifts. Their playbooks prioritize premiumization, cost-to-serve optimization, and selective capacity investments.
-
Regional champions (e.g., Yamazaki, Warburtons, Britannia): hold durable positions in home markets and can monetize local loyalty via premium lines and export expansion. They are natural M&A targets or partners for market entrants seeking fast access.
-
Foodservice and ingredient specialists (e.g., Rich Products, Aryzta): bridge retail and foodservice demand with frozen and semi‑finished solutions, offering resilience when retail throughput softens.
-
Snack-focused players (e.g., Hostess, McKee, Mondelēz biscuits business): capture impulse and convenience consumption with high-frequency purchase patterns, enabling different promotional economics and faster innovation cycles.
Recent industry developments reinforce the strategic signals in the report. Product line expansions and premium/lifestyle launches were announced in 2025–2026, while several recall and allergy‑alert events in 2025–2026 underscore the reputational and P&L risk of quality lapses. Separately, commitments by challenger bakers to natural ingredients and colors reflect accelerating consumer demand for clean‑label claims — an area where formulary, cost and shelf‑life tradeoffs must be carefully modeled.
Supply‑chain and regulatory dynamics to plan for in 2026
Input cost volatility remains a top risk vector. While soft wheat and refined flour pricing showed relative stability in recent assessments, procurement teams cannot assume price predictability. Tariff actions and trade policy shifts in 2025 have already translated into higher landed costs for select agricultural and packaging inputs; management should model mid‑single to low‑double digit uplifts in input cost under stress scenarios. Packaging regulation and EPR rollouts are creating both compliance obligations and economics for circular solutions—brands that anticipate packaging redesigns will avoid reactive surcharge passes and shelf disruptions.
On labeling, proposed front‑of‑package nutrition disclosure rules introduce material rework risk for broad portfolios. Companies must triage SKUs into categories for relabeling, reformulation or rationalization, and factor the 3–4 year compliance timelines into their product roadmaps.
2026 strategic playbook — recommended imperatives
-
Rebase your SKU portfolio: apply an evidence‑based SKU rationalization to reduce complexity and free up capital for high-growth premium variants and channel-specific assortments.
-
Lock in procurement resilience: combine longer‑dated supply contracts, index‑linked pricing clauses, and targeted hedges for critical commodities; stress-test supplier concentration.
-
Accelerate channel economics: optimize assortment by channel (retail, convenience, online, specialist) and invest in direct‑to‑consumer pilots where margin capture offsets fulfillment costs.
-
Invest in premium and functional offerings: prioritize products that command higher price premiums or recurring purchase behavior (e.g., health-oriented, on‑the-go formats), supported by controlled go‑to‑market tests.
-
Embed regulatory foresight: establish a compliance roadmap for labeling and packaging changes with assigned ownership and budget contingencies tied to portfolio actions.
-
Design for quality and crisis readiness: update traceability, testing and recall playbooks; run tabletop simulations informed by recent industry incidents to reduce time-to-response and reputational exposure.
-
Pursue targeted M&A: prioritize tuck‑ins that fill channel gaps or add manufacturing flexibility rather than broad market share buys; use our M&A screening matrix to rank targets.
How to use the report — practical next steps
-
Executive workshop: use the report’s strategic scenarios in a half‑day leadership alignment session to set FY26 priorities and capital allocation.
-
Operational deep dives: deploy the supply‑chain stress‑test models at the procurement and operations level to set hedging and contract strategies for the next 12 months.
-
Regulatory impact sprint: convene cross‑functional teams (R&D, legal, packaging, sales) to map SKU action plans against compliance timelines routed from the report’s regulatory matrix.
-
M&A pipeline activation: apply the deal-screen templates to shortlist 3–5 near-term targets and run a focused commercial and integration diligence process.
Concluding note — the trailer, and where to go for the full picture
This brief is designed as a high‑impact trailer: it articulates the strategic choices and near‑term actions executives must prioritize in 2026, based on our proprietary analysis of market sizing, competitor dynamics and industry shocks. The full PW Consulting Packaged Baked Goods Market Report contains the complete data tables, country and channel splits, interactive models, and granular subsegment forecasts that senior teams use to build investment cases and operational plans. Detailed regional and application-level figures, SKU-level P&L templates, and downloadable scenario models are available exclusively on the report page.
For access to the full dataset, interactive dashboards and tailored consulting support to convert insights into a 100‑day action plan, visit the PW Consulting report landing page or contact our industry team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Packaged Baked Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


