



PW Consulting Forecast: Anticorrosion Tape Market Valued at USD 215 Million in 2025, Poised to Reach USD 344.8 Million by 2032 at a 5.37% CAGR

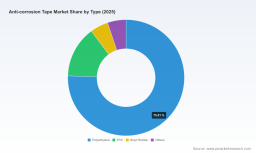
Anticorrosion Tape Market — 2026 Strategic Outlook and Decision Playbook
PW Consulting’s latest market research brief on the Anticorrosion Tape market (base year 2025; historical window 2020–2025; forecast 2026–2032) distils the evidence and scenarios executives need to make confident commercial and investment decisions in 2026. Our independent analysis combines high-granularity primary research with robust modeling: the market has grown from approximately USD 163.2 Million in 2020 to USD 215.0 Million in 2025 and is projected to expand to roughly USD 344.8 Million by 2032 at a compound annual growth rate (CAGR) of 5.37% over the forecast horizon.
Anticorrosion Tape Market
Why this report matters for 2026 decision-makers
-
Timing and inflection: The market’s mid-single-digit CAGR masks important inflection points driven by raw material dynamics, stricter sustainability rules, and new product introductions that will disproportionately reward fast movers.
Anticorrosion Tape Market -
Fragmentation and opportunity: Competitive intensity remains moderate; top-tier concentration is limited, creating opportunities for differentiated product plays, regional champions and roll-up strategies. PW Consulting’s concentration analysis shows the market is not dominated by a handful of players, making targeted consolidation and capability-driven M&A viable paths to rapid scale.
Anticorrosion Tape Market -
Margin pressure vs. premiumization: Volatility in specialty polymers and aluminum foil costs has compressed margins in recent cycles, while simultaneously accelerating buyer willingness to pay premium prices for low-VOC, longer-life and lower-total-cost-of-ownership solutions.
Data-driven signals you can act on
Our modelling synthesizes observed growth (2020→2025) with scenario-based forecasts (2026–2032) to quantify both base demand and downside/upswing risks. Key takeaway metrics (market size trajectory and CAGR above) are included here as anchor points; the full report overlays these with price-point elasticity, raw-material cost pass-through timelines, and project-level demand schedules for oil & gas, water infrastructure and marine sectors.
-
Historic momentum: The market accelerated through 2023–2025 as reconstruction and new pipeline projects rebounded, and as manufacturers introduced lower-VOC formulations in response to regulation and buyer preferences.
-
Forecast shape: Under our base-case design, market revenues increase steadily to 2032. Alternative scenarios presented in the report model a near-term shock to specialty polymer supply and a faster-than-expected adoption of eco-formulations — each implying distinct winners among producers and service providers.
-
Concentration insight: The market’s top-three and top-five concentration metrics indicate a fragmented supplier landscape — a structural feature that shapes pricing, channel strategy and M&A playbooks.
Competitive landscape — what leading firms are doing
We profile incumbent and emerging participants to show where capability advantage is being created and where it is fleeting. Our public-company and primary-interview coverage includes product strategy, recent launches, capacity moves and project footprints — synthesised to highlight repeatable plays and tactical missteps.
-
3M Company (St. Paul, MN) is leveraging adhesive R&D to introduce eco-friendlier butyl rubber tapes with lower VOCs and improved adhesion performance — a move designed to capture procurement mandates tied to sustainability and lifecycle cost procurement.
-
Winn & Coales (Denso) Ltd (Berkshire, UK) continues to be project-focused, supplying field joint and structural protection systems, and demonstrating the value of integrated product-project delivery in complex oil & gas contracts.
-
Nitto Denko Corporation (Ibaraki, Japan) is directing new adhesive formulations toward automotive applications — a diversification that reduces exposure to single vertical cycles and leverages higher-volume production economies.
-
Regional and specialist players (Scapa, Heskins, Polyken/Berry Global, Shurtape) are exploiting niche technical attributes — e.g., galvanic-isolation tapes, polymer-modified petrolatum systems and bespoke adhesive backings — to sustain margin insulation despite raw-material inflation.
Recent corporate moves highlight where strategic advantage is being built: capacity expansions in Southeast Asia, automotive-focused product launches, and field deployments on offshore projects. These developments underscore two concurrent trends: (1) geographic rebalancing of capacity toward growth end-markets, and (2) product innovation driven by regulation and lifecycle-cost procurement behavior.
Market dynamics and risk map — what to watch in 2026
-
Raw-material volatility: Specialty polymers and aluminum foils remain the primary cost vectors. Short-term spikes are likely to transmit to manufacturers unless mitigated through hedging, long-term contracts or formula redesign.
-
Regulatory and procurement shifts: Sustainability standards — including RoHS-style restrictions and buyer-mandated VOC ceilings — are creating both compliance costs and pricing opportunities for next-generation formulations.
-
Customer decision logic: Procurement is shifting from lowest-price to lowest lifecycle cost. Tenders increasingly reward demonstrable durability, compatibility with cathodic protection systems, and environmental compliance documentation.
-
Project pipeline exposure: Oil & gas and large water infrastructure projects are dominant demand drivers; timing variability in these sectors remains the largest single source of demand risk.
What the full PW Consulting report contains (practical, executable elements)
-
Executive playbook — concise, prioritized strategic moves for 12–36 month horizons (pricing, product roadmap, channel incentives, capital allocation).
-
Detailed market-sizing and forecasting model (2020–2032) with downloadable inputs and scenario toggles so teams can run custom “what-if” analyses against price and raw-material shocks.
-
Granular competitive profiles and actionable intelligence: product features matrix, go-to-market footprints, and supplier capability heatmaps — designed for M&A screening and partnership assessments.
-
Cost-to-serve and pricing playbook — including recommended pass-through mechanisms, contract language templates for hedging and procurement, and margin-protection tactics for manufacturers.
-
Regulatory compliance compendium and product reformulation checklist covering low-VOC pathways and RoHS conformity — enabling faster time-to-market for compliant products.
-
Supply-chain resilience pack: supplier segmentation, dual-sourcing templates, and inventory policy simulations calibrated to raw-material volatility profiles.
-
Deal and integration guidance for buyers: valuation adjustments, synergy capture checklists, and integration milestones that reflect the industry’s technical and regulatory idiosyncrasies.
-
Primary-data annex: interview transcripts, procurement RFP signals, and anonymized project-level demand curves that validate forecast assumptions.
Recommended 2026 actions for executives
-
Hedge and diversify raw-material exposure. Secure multi-year supply agreements for critical polymers and foils where possible, and evaluate formula redesigns that maintain performance while reducing dependence on high-volatility inputs.
-
Invest selectively in low-VOC and extended-life formulations. Regulatory headwinds and procurement preferences are accelerating willingness to pay for demonstrable TCO improvements.
-
Prioritize aftermarket and services. Extend warranty and inspection services attached to tape systems to capture recurring revenue and differentiate on lifecycle value.
-
Use M&A to consolidate technical capabilities and regional footprints. Given the market’s moderate concentration, bolt-on acquisitions can rapidly improve scale and accelerate entry into adjacent verticals (e.g., automotive, marine coatings).
-
Prepare contract clauses and pricing mechanisms for pass-throughs in volatile raw-material cycles; use indexed pricing for long-term projects to protect margins without sacrificing competitiveness.
How PW Consulting’s deliverables de-risk executive choices
Beyond headline forecasts, the report furnishes scenario-based P&L impacts, sensitivity tables linking raw-material price moves to margin erosion/recovery, and a prioritized list of rapid-win product and commercial initiatives. For due-diligence teams, we provide an M&A financial model with integrated technical risk scoring and contract-review templates to accelerate transaction timelines while preserving seller/buyer negotiation leverage.
Next steps — where to find the full intelligence
This article provides a strategic preview. For the underlying segment breakdowns, the full competitive benchmarking, downloadable modeling tools and the step-by-step playbooks that translate insights into 90/180/360‑day plans, please consult the full PW Consulting Anticorrosion Tape Market report. The full document contains the proprietary segment data and scenario models required to operationalize the recommendations summarized here.
PW Consulting is available to brief boards or investor committees, run bespoke workshops to stress-test your portfolio under the report’s scenarios, and support M&A screening, product roadmapping or procurement redesigns derived from this research. Contact our industry team to schedule a confidential briefing.
For detailed analysis of this topic, please visit the official page: Anticorrosion Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


