



PW Consulting: Dental Implant Fixtures Market Reaches USD 5,545 Million in 2025, Poised for Continued Expansion

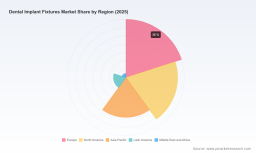
PW Consulting Strategic Preview: Dental Implant Fixtures Market Outlook (2026–2032)
Executive snapshot
As PW Consulting’s lead industry analyst, I present a strategic preview of our new Dental Implant Fixtures Market report — a tactical briefing designed for executive teams, corporate development functions, and strategic investors preparing decisions in 2026. The global fixtures market is on a sustained expansion path: our model places the market at USD 5,545.0 Million in the base year 2025 and projects a trajectory to approximately USD 8,947.2 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.01% across the 2026–2032 forecast window.
Dental Implant Fixtures Market
This release follows the “trailer” principle: it demonstrates the analytical depth and decision-useful insights contained in the full study while intentionally withholding granular segmentation outputs — the exact regional, design and material splits are reserved for the full report. Use this preview to assess the report’s strategic value for 2026 planning and to determine whether a deeper purchase is warranted for tactical execution.
Dental Implant Fixtures Market
Why 2026 is a pivotal decision year
- Inflection between clinical adoption and commercialization: Technology advances (immediate-loading systems, surface chemistries) and renewed regulatory activity are compressing time-to-adoption for premium fixtures. Organizations that finalize channel and regulatory strategies in 2026 can capture disproportionate share through 2027–2029.
- Consolidation and scale economy: Market concentration metrics indicate a mid-to-high consolidation environment (CR3 and CR5 demonstrate meaningful incumbent advantage). This dynamics favors players who combine product innovation with distribution scale and cost discipline.
- Payer and procedure economics: In core markets, reimbursement constructs and procedure-level economics (for example, bundled payments for implant-supported rehabilitations) will materially influence case mix and pricing power during the 2026 contracting cycle.
Key market dynamics and what they mean for strategy
- Steady demand, premiumization trend: Demographic tailwinds and higher case acceptance in established and emerging clinics are underpinning steady revenue growth. The market wide CAGR of ~7% reflects both volume growth and a skew toward higher-value fixture systems (new alloys, advanced surface treatments and esthetic collars).
- Technology-driven differentiation: Immediate-loading platforms, porous and trabecular titanium geometries, and microchannel surface treatments are maturing from clinical pilots to commercial-scale offerings. Firms that demonstrate clear, reproducible clinical advantages will win preferential procurement from implantologists and leading dental networks.
- Regulatory and standards environment: Compliance with standards such as ISO 14801 (dynamic fatigue testing), EN 556-1 sterilization requirements and AAMI guidelines is now table stakes. Regulatory refreshes and regional certification updates will create windows for competitive repositioning and localized product relaunches.
- Reimbursement & procedural economics: Procedure-level reimbursement remains a pivotal demand enabler. In several jurisdictions, bundled payment codes for implant rehabilitations materially affect pricing thresholds and return-on-investment calculations for clinics and DSOs.
- Supply chain & cost structure: Primary fixture materials — grade 4 titanium and Ti-Zr alloys (e.g., Roxolid) — remain the dominant substrates; their relative cost and manufacturing complexity create entry barriers for new entrants but also provide margin opportunity for process innovators. Sterilization modalities and single-use packaging trends are incremental cost drivers that buyers will scrutinize in 2026 procurement cycles.
Competitive landscape — who to watch
The sector combines global leaders with highly capable regional specialists. Market concentration indicates meaningful leadership by the top-tier vendors while leaving room for regional challengers and low-cost players to expand. Our report contains a proprietary competitor scoring matrix; below are strategic profiles and recent moves that matter for 2026 strategy.
Dental Implant Fixtures Market
- Straumann Group (Basel, Switzerland) — Recognized for material innovation (Roxolid) and high-velocity implant platforms (BLX family). Recent product refreshes emphasizing esthetics and immediate loading accelerate their premium positioning.
- Nobel Biocare / Danaher (Zurich, Switzerland) — Portfolio breadth includes established surface technologies and all-on-4 solutions. Regulatory clearances and modular platform extensions have preserved their relevance across treatment segments.
- Dentsply Sirona (Charlotte, NC, USA) — Delivers systems with conical connections backed by long-term clinical datasets; published multi-year studies strengthen clinical trust and clinician preference in institutional settings.
- Zimmer Biomet (Warsaw, IN, USA) — Focus on trabecular/porous designs to enhance osseointegration; certification and regulatory lifecycle management are central to their go-to-market.
- BioHorizons (Birmingham, AL, USA) — Differentiates through surface microchannels and soft-tissue attachment tech; clinical soft-tissue outcomes drive adoption among aesthetics-focused clinicians.
- Geistlich Pharma (Wolhusen, Switzerland) — While primarily known for biomaterials, its compatibility positioning with major fixtures creates strategic partnership leverage across the restorative pathway.
- Henry Schein (Melville, NY, USA) — As a global distributor, Henry Schein’s network effects and channel execution make it a critical route-to-market partner for many OEMs.
- OSSTEM Implant (Seoul, South Korea) — Competitive with cost-effective, clinically robust systems; recent distribution expansions signal an aggressive push into North America and other developed markets.
- Neodent (Curitiba, Brazil; part of Straumann) — Targets emerging market segments with value-engineered platforms; strategy is to complement parent-company premium portfolio with local-market reach.
- Bego Implant Systems (Bremen, Germany) — European-focused player with traditional surface technologies; stable incumbent among a subset of clinical customers.
Recent corporate moves underline the competitive tempo: product launches and regulatory clearances (e.g., new BLX variants, FDA 510(k) approvals), distribution agreements expanding routes-to-market, and fresh clinical evidence that accelerates adoption cycles. Our full report includes a timeline of these developments and forward-looking impact scenarios for each major player.
What the PW Consulting report contains (operational, decision-ready deliverables)
- Proprietary demand model (2020–2032) with scenario pathways—base, upside, downside—driven by demographic, clinical adoption and reimbursement inputs.
- Price-volume matrix and sensitivity analysis to quantify margin outcomes under alternative material and sterilization cost scenarios.
- Regulatory & standards playbook summarizing certification timelines, testing standards (e.g., ISO 14801) and key regional submission levers.
- Commercial go-to-market playbook—segment-specific channel maps, distributor scorecards, clinician segmentation and DSO procurement decision criteria.
- Technology assessment—comparative clinical evidence scorecards for surface treatments, connection designs and emerging materials (including Ti and Ti-Zr alloys).
- Competitive intelligence: strategic profiles, M&A pipeline tracker, and benchmarked KPIs (including market concentration analysis showing CR3/CR5 implications for market entry or consolidation).
- Clinical & economic case models that integrate payer reimbursement constructs (impact analysis for typical procedure economics and break-even timelines).
- Operational checklists for manufacturing scale-up, sterilization compliance, packaging, and post-market surveillance requirements.
Strategic implications and targeted recommendations for 2026 planning
- Prioritize regulatory and clinical evidence investments: For premium players, accelerating controlled clinical trials and securing regional clearances in 2026 reduces adoption friction and expands tender eligibility.
- Channel architecture matters: Evaluate hybrid models (direct in key accounts + distribution partnerships in breadth markets). Distributor scorecards in our report identify partners that balance reach with clinical support capabilities.
- Value-engineering versus premiumization trade-offs: Use our price-volume sensitivity outputs to determine where to invest in costly material science (alloys, surface processing) versus cost-out in manufacturing to protect margins.
- M&A and alliance playbook: Targeted acquisitions of complementary biomaterials, digital prosthetics, or regional distributors can accelerate time-to-scale. The report’s M&A pipeline and valuation heuristics are calibrated to 2026 market multiples and integration risk profiles.
- Operational readiness: Review sterilization pathways and supply-chain robustness now—compliance with sterilization standards and validated supply of key alloys are practical gating factors for new product launches in 2026.
Methodology and data integrity
Our analysis synthesizes primary interviews with clinicians, distributors and OEM R&D leads, audited company disclosures, regulatory filings and a granular shipment-to-revenue model. Historical coverage spans 2020–2025 with a forecast framework from 2026–2032. Key model assumptions and sensitivity levers (adoption curves, pricing dynamics, material cost inputs and reimbursement scenarios) are fully documented in the full report to support executive decision memos and board-level investment approvals.
Next steps — how this preview helps you
This strategic preview is intended to help teams decide whether to deploy the full report as part of 2026 planning. If you are evaluating:
- Product roadmap prioritization,
- Market entry or expansion,
- M&A targets or divestiture timing, or
- Commercial channel redesigns—
—then the full PW Consulting Dental Implant Fixtures Market report provides the actionable intelligence, financial models and playbooks to operationalize those decisions.
Accessing the full report
To obtain the complete dataset, scenario models, and the competitive intelligence annex (including the detailed regional, material and design-level splits that are intentionally withheld in this preview), please visit our report landing page or contact PW Consulting’s market advisory desk. The full deliverable includes editable financial models, a board-ready slide deck, and a bespoke one-hour briefing tailored to your organization’s strategic questions.
For detailed analysis of this topic, please visit the official page: Dental Implant Fixtures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


