



PW Consulting: Ultra Fine Precipitated Calcium Carbonate Market to Surge from USD 215.0 Million (2025) to USD 344.8 Million by 2032 at a 6.98% CAGR

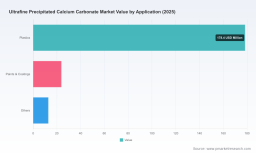
Ultra Fine Precipitated Calcium Carbonate (PCC) Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
PW Consulting’s Ultra Fine Precipitated Calcium Carbonate (PCC) Market study, calibrated to a 2025 base year with a historical lens on 2020–2025 and a forecast horizon through 2032, delivers the kind of actionable intelligence that senior executives and corporate strategy teams need to make confident 2026 decisions. The global market — measured in USD Million — is on a sustained upswing, with a near 7.0% compound annual growth rate (CAGR) projected across our 2026–2032 forecast window. By 2032 the market is expected to approach the mid-hundreds (USD 344.8 Million), up materially from the 2025 baseline (USD 215.0 Million). This brief outlines the strategic logic, tactical playbook and competitive diagnostics investors and operators must consider now — while deliberately reserving granular segment-level datapoints for the full report.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Why this market matters in 2026
-
Demand resiliency: Ultrafine PCC has become a core filler and performance additive across plastics, paints & coatings, sealants, and specialized industrial applications. Structural demand drivers (lightweighting, functional reinforcement, opacity and rheology control) are converging with sustainability and regulatory pressures that favor engineered mineral solutions.
Ultra Fine Precipitated Calcium Carbonate Pcc Market -
Growth trajectory: A projected ~7% CAGR through 2032 translates into significant capacity and revenue opportunities for manufacturers, formulators and integrated chemical players. The growth is neither speculative nor niche — it is measurable and persistent across the forecast period.
Ultra Fine Precipitated Calcium Carbonate Pcc Market -
Fragmented competitive dynamics: Market concentration remains low relative to many chemical commodities (CR3 and CR5 metrics indicate a broadly fragmented supplier base). That fragmentation creates room for disciplined consolidation, premiumization strategies, and differentiated technology plays.
Market dynamics shaping 2026 decisions
-
Raw material and price volatility: Commodity pressure is alive and relevant. Recent index movements show step-changes in calcium carbonate pricing that materially affect margins and procurement strategy — buyers and sellers must adopt dynamic price models and hedging playbooks to sustain profitability.
-
Regulatory tightening accelerates clean production: The EU’s tightened REACH regulations and updated North American occupational exposure limits have accelerated investment in cleaner precipitated processes and airborne particulate controls. Companies yet to upgrade processes face both compliance risk and market access friction with large downstream customers.
-
Environmental constraints on capacity expansion: Mining-related emission controls, dust limits and water discharge regulations are raising the effective cost of capacity expansion in mature production regions. That shifts strategic emphasis toward efficiency gains, coated/functional product premiumization and selective greenfield siting.
-
Geopolitical exposures: Currency swings, tariff uncertainty and supply-chain routing concerns persist across major production and consumption geographies — requiring integrated FX, logistics and trade-policy scenario planning in capital allocation decisions.
-
Technology and formulation innovation: Advances in ultrafine particle engineering (surface treatments, coating chemistries and dispersible grades) are enabling performance-led premium segments. R&D intensity in these areas will determine margin capture more than scale alone in the coming cycle.
Competitive landscape — what leading players are doing
The industry comprises a spectrum of specialized producers and regional players, each pursuing distinct strategies: product engineering, vertical integration, and end-market focus. Representative participants covered in our analysis include Calcite GmbH (Germany), 20 Microns Nano Minerals Limited (India), Guangdong Qiangda New Materials Technology Co., Ltd. (China), Fujian Sanmu Nano Calcium Carbonate Co., Ltd. (China), and EZ Chemicals Inc. (China). Collectively these companies exemplify a mix of capabilities — from deep application know-how to plant-level process expertise — that shape competitive positioning.
-
20 Microns Nano Minerals Limited ( https://20microns.com) recently reinforced its product-led strategy with a December 2025 SKU launch: Micron PCC 500. The grade is engineered for high-performance sealants and claims improvements in reinforcement, rheology control, surface finish and durability. This type of SKU-level innovation is indicative of how companies are migrating up the value chain to capture application-specific price premia.
-
European and Chinese manufacturers are differentiating through process cleanliness, particle engineering and regional service models. Several suppliers are investing in coated and surface-functionalized grades to address formulators’ needs for dispersion stability, UV resistance and rheological control.
-
Across the vendor set, strategic moves fall into three patterns: (1) product premiumization and application-specific R&D, (2) selective capacity additions in cost-advantaged geographies, and (3) commercial tie-ups with downstream compounders and formulators to lock-in offtake and accelerate co-development.
What PW Consulting’s report delivers — practical, deployable assets
Our full Ultra Fine PCC study is structured to be operational from day one. Key deliverables include:
-
Demand scenarios and capacity maps — forward-looking supply-demand balances across the 2026–2032 horizon, with scenario sensitivities for price, regulation and raw-material shocks.
-
Go-to-market playbooks — segmented GTM strategies for premium, standard and specialty PCC offerings, including channel design, distributor economics and sample-to-spec conversion roadmaps.
-
Price-sensitivity and margin models — rolling simulation models that quantify margin impacts of feedstock swings, freight changes and blending strategies so CFOs can stress-test budgets.
-
ESG & compliance checklist — a stepwise remediation roadmap aligned to REACH and North American occupational exposure updates, including capex and operating-cost implications for common abatement technologies.
-
Technical KPIs and product attribution matrices — clear metrics to assess grade differentiation (particle size distribution targets, surface area, coating chemistries, dispersibility, and rheological impact) and their commercial value.
-
M&A and partnership screening toolset — scored target lists, integration risk heatmaps and value-capture estimates to guide acquisitive growth strategies in a fragmented market.
Strategic playbook for 2026 — recommended executive priorities
-
Lock in secure, flexible feedstock sourcing. Use indexed purchasing, strategic supplier partnerships and dual-sourcing architectures to buffer near-term price volatility and supply interruptions.
-
Invest selectively in premium grades and application co-development. Convert commodity exposure into differentiated, higher-margin product lines through targeted R&D and co-engineering with key customers.
-
Accelerate compliance and worker-safety upgrades. Prioritize investments that both reduce regulatory risk and serve as commercial differentiators for environmentally conscious downstream buyers.
-
Adopt an M&A lens focused on technology and channel. Given low concentration metrics, strategic acquisitions or joint ventures that deliver proprietary process technology or entrenched customer relationships can materially shift market share.
-
Deploy advanced pricing and analytics. Implement real-time price-sensitivity tools that feed commercial negotiation, tendering and long-term contract design to protect margins during cyclical swings.
-
Build resilience into logistics and manufacturing footprint design. Re-evaluate plant siting against environmental permitting risks and freight economics to reduce the likelihood of disruptive capacity curtailments.
Decision-use cases where the report adds immediate value
-
Board-level capital allocation: Quantified scenarios and payback analytics to justify brownfield expansions or greenfield investments in 2026–2027.
-
Commercial strategy: A GTM playbook that converts technical grade improvements into contracted revenue and reduced spot exposure.
-
M&A diligence: Rapid target screening and integration playbooks that reduce transaction risk and accelerate value capture post-close.
-
Risk & compliance planning: A prioritized capex roadmap to meet REACH and updated occupational exposure limits while minimizing production downtime.
Why PW Consulting’s analysis is different
Many market reports recycle headline growth and a list of suppliers. This study combines proprietary primary interviews, plant-level technical evaluation and scenario-based financial modeling to produce not just market forecasts but executable strategies. We explicitly tie technical grade attributes to commercial outcomes — for example, how a defined improvement in dispersibility or surface treatment translates into formulation cost-savings for a plastics compounder, and into pricing power for the supplier.
What we are not disclosing here — and why
Consistent with our “trailer” principle for this release, we have provided the market macro picture and the executive-level implications you need to act. We have intentionally withheld granular regional and application revenue splits, detailed per-grade price curves, and certain proprietary supplier benchmarking scores. These are included in the full report because they are high-value, client-grade assets meant to inform commercial negotiations and capital decisions; sharing them publicly would undermine their strategic utility.
Next steps
If your 2026 planning involves capacity decisions, product roadmap prioritization, commercial contracting or M&A in ultrafine PCC, PW Consulting’s full report provides the evidence base, models and playbooks to shorten decision cycles and de-risk execution. Contact our industry practice to license the full report and receive a tailored briefing focused on your strategic questions.
PW Consulting — turning technical detail into boardroom-ready strategy for the ultrafine PCC economy.
For detailed analysis of this topic, please visit the official page: Ultra Fine Precipitated Calcium Carbonate Pcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


