



PW Consulting: Heat Transfer Vinyl Market Poised for a 6.45% CAGR Through 2032

Heat Transfer Vinyl Market 2026: A Strategic Preview for Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise yet strategically rich preview of our forthcoming Heat Transfer Vinyl (HTV) Market report — a resource designed to shape high-confidence decisions for 2026. This briefing synthesizes the report’s macro view, near-term risk vectors, and the practical playbook we provide to commercial, product and corporate development teams. We deliberately surface the intelligence you need to test hypotheses and prioritize action while reserving granular segment-level metrics for the full report.
Heat Transfer Vinyl Market
Market snapshot: scale, trajectory, and competitive posture
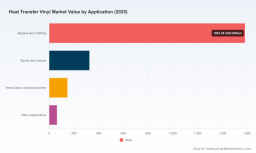
The HTV market is well into a steady expansion phase. From a 2025 baseline of roughly USD 2.12 billion, our model anticipates continued growth through the forecast window, underpinned by an expected compound annual growth rate (CAGR) of 6.45% (2026–2032). By the end of the forecast horizon, the market is projected to climb materially versus 2025 levels, a trajectory driven by rising demand for customized apparel, sportswear innovations, new printing/transfer technologies, and sustainability-driven reformulation.
Heat Transfer Vinyl Market
Market structure remains moderately fragmented: the combined share of the three largest players sits in the low-to-mid 30% range, and the top five firms control just over two-fifths of the market. That concentration profile creates dual opportunities — scale benefits for established manufacturers and attractive niches for agile challengers able to combine technical differentiation with localized service models.
Heat Transfer Vinyl Market
Why this matters for 2026 decision-making
- Allocate capital to high-conviction innovations: The market’s growth rate supports investment in next-generation PU formulations, printable HTV systems, and sustainable chemistries that meet tightening regulatory requirements in key markets.
- Prioritize supply-chain resilience: Volatility in vinyl and resin supply, recent plant turnarounds and commodity swings have shown how margin exposure can materialize quickly. Procurement strategies and dual-sourcing plans should be stress-tested now.
- Use channel leverage to win share: Distribution partnerships and ecosystem plays (hardware + consumable bundles) are accelerating reach into SMEs and professional decorators. Strategic alliances can be a faster route to scale than greenfield expansion.
- Refine M&A thesis: Fragmentation means attractive tuck-in targets exist that offer technology upgrades, regional distribution, or adjacent product lines (e.g., printable films, heat presses).
Report deliverables — what you will get (practical, executable)
Our full report is organized to move teams from insight to implementation. Key deliverables include:
- Actionable market sizing and forward scenarios calibrated for 2026 planning cycles. We provide a base case, downside stress test, and upside adoption scenario to guide CAPEX and inventory decisions.
- Supply-chain risk heatmaps highlighting raw-material dependencies, single-source exposures, and critical lead-time sensitivities by production step.
- Regulatory and sustainability roadmap with thresholds and triggers that matter to product teams (e.g., chemical-restriction timelines, recyclability milestones, low-VOC targets) and a checklist for reformulation prioritization.
- Commercial playbooks for three archetypal companies — a global incumbent, a regional challenger, and a pure-play innovator — including go-to-market KPIs, pricing tolerance ranges, and channel incentive designs.
- An M&A decision framework with valuation drivers, integration risk scorecards, and a list of acquisition criteria mapped to likely targets (technology, distribution, geographic footprint).
- Competitive threat dossiers synthesizing public and proprietary signals for 12+ key vendors, including product roadmaps, patent, and partnership landscapes.
Competitive landscape — who’s shaping the market and how
The HTV ecosystem blends global materials specialists, equipment vendors, and consumer/SMB platform players. Several dynamics stand out:
- Technology and brand leadership: Long-standing HTV specialists continue to assert leadership through breadth of product range and specialty lines (glitter, stretch, printable, metallic). Their scale supports R&D and global branding that matters to large apparel decorators and licensing partners.
- Channel consolidation: Recent distribution arrangements and reseller expansions are accelerating. Notable partnerships that expanded access in North America and consolidated supply to key decorator channels have implications for regional incumbency and pricing power.
- Hardware + consumable convergence: The consumer/SMB ecosystem led by integrated cutter and heat-press makers is broadening product bundles to lock users into consumable cycles. This vertical integration increases lifetime value per customer and raises barriers for standalone film suppliers unless they integrate with platform players.
Strategic implications by player type
- Global material leaders retain advantage through product breadth and specialty formulations. Their near-term priority should be accelerating eco-friendly reformulations and expanding printable HTV lines for industrial digital workflows.
- Regional specialists and Asian manufacturers can compete on price and speed-to-market, and will gain if they invest in qualified quality systems and certifications required by Western OEMs and retailers.
- Platform and equipment vendors represent both distribution partners and competitors — partnering with them can fast-track SMB penetration, but it requires careful commercial terms to avoid margin erosion.
Industry dynamics: raw materials, regulation and product evolution
Three structural shifts should be on every executive’s radar for 2026:
- Raw-material pressure and margin squeeze: PVC resin markets showed renewed upward pressure in early 2026 amid plant maintenance cycles and recovering downstream demand. Producers exposed to PVC volatility must model margin scenarios and use hedging, alternative formulations, or strategic inventory as buffers.
- Regulatory-driven material transitions: Across major markets, policy and retailer chemical standards are accelerating substitution away from legacy PVC formulations toward polyurethane (PU) and polyester-based films that offer lower emissions and better end-of-life profiles. This is not a binary move; it creates transitional product windows and opportunities for value-added differentiated chemistries.
- Demand-side product sophistication: Performance requirements for sportswear (stretch, wash durability, hand feel) and printability for digital textile workflows are raising the technical bar. Firms that control both formulation and application guidance will capture premium pricing.
Recent market moves that foreshadow 2026 winners
- Distribution alliances that broaden market access and shorten customer adoption cycles are becoming decisive enablers for share gains.
- Product launches that integrate consumables with improved end-user hardware — including faster, lower-temperature presses compatible with multi-technology transfers — are expanding addressable use cases among prosumers and micro-businesses.
- Corporate investments in traceability and RFID-enabled film solutions signal the beginning of a secondary product tier focused on supply-chain authentication and value-add in packaging and premium apparel.
Strategic recommendations — prioritized actions for 2026
We recommend a three-track program for companies aiming to strengthen commercial returns in 2026:
- Short-term (0–6 months): Execute a supply-chain stabilization plan (dual-source critical resins, increase safety stock for high-use SKUs, and renegotiate lead times). Launch a targeted promo with channel partners to convert SMB users to higher-margin specialty films.
- Medium-term (6–18 months): Accelerate reformulation programs to meet imminent chemical and recyclability standards. Pilot bundled hardware-consumable offerings with select platform partners to prove unit economics before scale-up.
- Long-term (18+ months): Build or acquire digital-printable HTV capabilities and invest in traceability-enabled film products to capture premium segments in performance and branded apparel markets. Use M&A to fill gaps in distribution or to acquire environmentally preferred chemistries.
How PW Consulting’s report supports execution
The full report includes the verification datasets, supplier scorecards, and an executable playbook we describe above. It is intentionally structured to support cross-functional planning: procurement teams receive supplier heatmaps and contingency templates; R&D gets reformulation milestones aligned to regulatory timelines; commercial teams receive channel partnership frameworks and a prioritized list of SKU rationalizations designed to protect margin while supporting growth.
We adhere to a “preview” philosophy in this brief — we have shown the macro outlook, the competitive dynamics, and the specific strategic levers that matter in 2026 while withholding granular split-level KPIs and region-by-application tables to preserve the report’s full operational value. Those detailed segment and pricing matrices are included in the full deliverable and are essential for models, valuations, and negotiation strategies.
Next steps
- If you are leading procurement, request the supplier risk appendix to stress-test your resin exposure.
- If you run product or R&D, secure the reformulation roadmap and the prioritized test matrix for switching to low-VOC PU and polyester-based films.
- If you are in corporate development, receive the M&A target shortlist and the integration scorecards that align with 2026 value-creation milestones.
For commercial teams planning their 2026 go-to-market, this report is designed to be the action manual — enabling you to recalibrate pricing, prioritize SKU investments, and structure channel incentives that capture share without sacrificing margin. To access the full datasets, scenario models, and competitor dossiers referenced here, please visit the PW Consulting report page for the Heat Transfer Vinyl Market study.
PW Consulting remains available for bespoke briefings and rapid workshops to convert the report’s insights into an executable 90-day plan tailored to your company’s appetite for investment, risk tolerance, and strategic objectives.
For detailed analysis of this topic, please visit the official page: Heat Transfer Vinyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


