



PW Consulting: Flutes Instrument Market Poised for Steady Expansion at a 4.31% CAGR in 2026–2032 Forecast

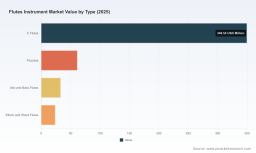
Flutes Instrument Market — Strategic Preview for 2026: Actionable Intelligence from PW Consulting
Executive summary
PW Consulting’s new Flutes Instrument Market report delivers a focused, decision-ready briefing for executives planning resource allocation, product strategy, and channel investments in 2026 and beyond. The global market for flutes stood at USD 467.18 Million in 2025 and has demonstrated steady recovery from the pandemic era, rising from USD 382.15 Million in 2020. Our 2026–2032 forecast projects the market to grow at a compound annual growth rate (CAGR) of 4.31%, reaching approximately USD 627.72 Million by 2032. These headline metrics underline a market large enough to justify targeted strategic plays, yet sufficiently specialized to reward companies that execute differentiated value propositions.
Flutes Instrument Market
Why this report matters for 2026 corporate planning
- Timing for resource reallocation: With a mid-single-digit CAGR and evident post-2020 momentum, 2026 is a pivotal year for shifting investment from broad-based volume plays to targeted innovation (e.g., premiumization, sustainable packaging, and new educational channels).
- Risk-calibrated market entry: Trade friction and tariff volatility introduce execution risk for import-dependent models; our intelligence identifies where to localize manufacturing, adjust pricing frameworks, and design compliant supply chains.
- Channel and product prioritization: The market structure favors firms that align product tiers (student, intermediate, professional) with the right distribution and service models—school programs, institutional contracting, and premium direct-to-consumer experiences.
- M&A and partnership signals: Moderate market concentration (top-3 vendors account for ~43% and top-5 for ~56% of market sales) means consolidation and strategic alliances can quickly shift competitive dynamics—use our report to evaluate targets and partnership rationales.
Data-driven positioning without the spoilers
To preserve the strategic value of this preview, we present high-level, verifiable metrics (overall market size, growth rate, concentration) while deliberately reserving granular regional, application and type splits for the full report. Clients will find rich tables, dynamic dashboards, and downloadable models that unpack those segment-level figures, enabling revenue-scenario modeling and price-volume forecasting tailored to your business. This “trailer” approach demonstrates our method and findings while inviting teams to access the full dataset for executable plans.
Flutes Instrument Market
What’s inside the full PW Consulting report (practical deliverables)
- Market sizing and baseline time series (2020–2025) with scenario-based forecasts (2026–2032) that support budgeting and three-tier planning (conservative, base, aggressive).
- Segmentation frameworks (by geographic market, instrument type, and end-use) with interactive sensitivity analysis and break-even maps for manufacturing, import, and distribution choices.
- Channel and go-to-market playbooks: recommended direct-to-consumer, distributor, and institutional strategies for each product tier, including margin calculators and lead-time impact models.
- Supply-chain and cost-pressure analysis: import tariff scenarios, sourcing alternatives, manufacturing footprint optimization, and inventory buffers tuned to instrument lead times.
- Competitive benchmarking: detailed company profiles, product positioning matrices, go-to-market strengths, IP and craftsmanship differentiation, and acquisition targets with quantified fit scores.
- Risk register and mitigation plans covering regulation, trade policy, currency exposure, and demand shocks from education budgets.
- Practical implementation templates: product roadmap prioritization, trade-show and institutional sales calendars, and a 12–24 month M&A diligence checklist.
Competitive landscape — who matters and why
The flute market blends global brands, regional volume players, and a cluster of highly specialised artisanal makers. Strategic implications differ by competitor archetype:
Flutes Instrument Market
- Global integrated manufacturers (e.g., Yamaha Corporation): Scale across student through professional tiers, global distribution reach, and brand trust make them natural partners for institutional programs. Recent moves toward sustainable packaging reinforce a combined product-and-brand experience play that competitors should monitor and, where relevant, emulate.
- Volume/education specialists (e.g., Trevor James, Jupiter, Conn-Selmer/Armstrong): These makers dominate accessibility and price-sensitive channels. They are positioned to capture demand from school programs and beginner segments; incumbents should consider product-adjacent services (rental, maintenance) to protect margin.
- Premium Japanese makers (e.g., Muramatsu, Miyazawa, Altus, Sankyo): Their Japan-based craftsmanship and R&D focus attract professional and advancing players. They set quality benchmarks that define high-price tiers and act as natural partners for artist endorsements and orchestral supply contracts.
- US artisan cluster (Powell, Wm. S. Haynes, Brannen Brothers, Burkart, Di Zhao, and peers): The Boston and broader New England ecosystem delivers ultra-premium, custom instruments prized by orchestras and soloists. Recognition of Greater Boston as a global premium hub in 2025 amplifies brand value for these makers—opportunities exist to scale bespoke services via limited editions, artist collaborations, and experiential marketing.
- Hybrid strategies (Gemeinhardt, Pearl): Firms blending local manufacturing for specific components with offshore assembly achieve favorable cost-quality balance for mid-tier and professional instruments. These models are resilient in tariff environments if component localization is strategically deployed.
Recent developments that should inform 2026 strategy
- Yamaha’s 2025 sustainable packaging redesign demonstrates how product presentation and ESG credentials can be a low-friction lever to improve perceived value at entry price points.
- Regional recognition: the 2025 spotlight on Boston’s artisanal cluster elevates premium makers’ bargaining power with orchestras and collectors, creating aftermarket and service opportunities beyond primary instrument sales.
- The Musical Instrument Museum’s “Magical Flute” exhibition (launched December 2025) is enlarging public interest and can be leveraged by brands for co-marketing, provenance storytelling, and cross-channel promotions.
- Policy and trade noise: 2025 U.S. tariffs on woodwind instruments have reached effective levels up to 27.4% in some cases; export figures showed an 8.4% decline in U.S. musical instrument exports in early–mid 2025 versus prior averages. These disturbances matter for pricing strategy and sourcing decisions in 2026.
- Demand drivers: continued government investments in music education across emerging Asian markets present structural expansion opportunities for student-focused manufacturers and for companies willing to build institutional relationships.
Strategic plays for 2026 — prioritized and actionable
- Localize selectively: Protect margin and access by localizing critical components or assembly in tariff-sensitive markets. Use our cost-benefit templates to identify the break-even point for localization vs. import.
- Product tier segmentation: Differentiate offers by lifecycle stage—promote rental and service bundles in educational markets, emphasize customization and limited editions for premium buyers, and support mid-tier with upgrade paths and trade-in programs.
- Capitalize on sustainability and experience: Align packaging, materials sourcing and repair services with ESG narratives; invest in premium unboxing and post-sale service for higher lifetime value.
- Partnerships with public institutions: Establish curricula and rental agreements with schools and conservatories in growth markets, leveraging government music-education initiatives to secure volume and visibility.
- Digital and direct engagement: Build D2C channels focused on configurators, virtual try-before-you-buy tools, and artist-led content to shorten the consideration cycle for intermediate and professional buyers.
- M&A and alliance playbook: Target bolt-on artisanal brands to capture premium margins, or consolidate distribution in strategic territories to mute tariff impact.
How PW Consulting’s report translates into a 2026 action plan
Executives will find an immediately usable 90–day activation plan inside the full report: prioritized initiatives by expected return and implementation complexity, vendor and partner shortlists, and a set of KPIs for quarterly tracking. The report’s downloadable financial model lets teams stress-test scenarios—tariff shocks, demand surges from education programs, and premiumization rate changes—so CFOs can model cash flow and capital allocation implications quickly.
Closing — next steps
For decision-makers preparing budgets and strategic roadmaps in 2026, PW Consulting’s Flutes Instrument Market report provides the empirical foundation and tactical tools necessary to convert market signals into competitive advantage. This brief exposes the market shape, concentration dynamics, and near-term risks; the full report contains the granular segment data, model access, and company-level detail required to operationalize those insights.
Access the full report and the interactive dataset on PW Consulting’s website to download the executive toolkit, request a bespoke briefing, or arrange a scenario workshop tailored to your organization’s product and distribution footprint.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


