



PW Consulting: Corrugating Grease Market Poised to Reach USD 295.56 Million by 2032, Says New Insights

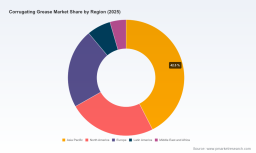
Corrugating Grease Market — 2026 Strategic Outlook and Decision Playbook
Executive summary
As corrugated packaging rebounds and industrial maintenance priorities refocus on uptime and lifecycle cost, corrugating greases are moving from a commoditized maintenance item to a strategic input for plant reliability and packaging safety. PW Consulting’s latest market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, quantifies the market and translates that data into a practical playbook for management teams preparing 2026 budgets and strategic choices.
Corrugating Grease Market
Key macro markers: the global corrugating grease market shows clear expansion into the latter half of the decade, underpinned by a steady compound annual growth rate (CAGR) of 4.62% across our forecast window and a base-year market size that informs FY-2026 planning. Our research triangulates demand-side recovery in corrugated packaging volumes, technology shifts in high-temperature greases, and raw-material structural changes to surface the highest-impact decision levers for 2026.
Corrugating Grease Market
Why this matters for 2026 decisions
- Procurement and operations leaders face a narrow window (next 12–18 months) to lock in lubricant strategies that affect maintenance intervals, inventory carrying costs, and operational safety through 2030.
- Suppliers and OEMs must align product roadmaps and service propositions around heat-resistant chemistries and certifications relevant to food-contact packaging lines.
- Private equity and corporate M&A teams will find the sector’s current concentration and margin dynamics useful for identifying consolidation or joint-service opportunities.
Market dynamics and structural drivers
Several structural themes are shaping the corrugating grease market:
Corrugating Grease Market
- Packaging recovery: The corrugated packaging market’s rebound supports sustained maintenance spend on corrugating equipment, creating a predictable baseline for grease demand.
- Formulation pressure from raw materials: Lithium soap and lithium complex thickeners remain significant components of global grease production, but volumes have experienced near-term pressure amid competing demand (notably from electric-vehicle battery supply chains) and a broader shift to alternative thickeners. Tighter upstream controls and regulatory scrutiny on lithium extraction are accelerating formulation experimentation across suppliers.
- Regulatory and certification pull: NSF H1 registration and similar food-contact certifications are material procurement differentiators for grease used on corrugating lines involved in packaging foodstuffs. Certification status is increasingly a must-have in commercial negotiations with major packagers.
- Supplier concentration and bargaining dynamics: The market exhibits a moderate degree of concentration among leading suppliers, creating both opportunities for premium, service-led offerings and vulnerability for buyers that rely on a narrow supplier base.
Technology and formulation trends
High-temperature, low-volatility chemistries continue to dominate technical conversations. Fully fluorinated PFPE/PTFE-based greases remain the benchmark for single-facer and heated-roll applications because of their film strength and thermal stability at elevated temperatures. At the same time, synthetic hydrocarbon and other engineered high-temperature synthetics are making inroads where cost or regulatory considerations require alternatives to fluorinated systems.
Manufacturers must weigh trade-offs: top-tier PFPE systems offer superior thermal performance and maintenance interval extensions but come with higher upfront material cost and tighter supplier concentration. Non-fluorinated high-temperature synthetics and novel thickener-systems provide cost and regulatory latitude, but require thorough compatibility and wear testing before plant-wide conversion.
Competitive landscape — what leading suppliers are doing
PW Consulting’s competitive review highlights differentiated strategies from incumbents and specialist suppliers:
- Chemours (Krytox) leverages its Krytox Performance CORR product family to anchor premium positioning: established industry standards for high-temperature corrugator bearings and strong brand recognition among maintenance teams. Their value proposition is thermal performance combined with proven uptime benefits.
- FUCHS Lubricants (including Nye Lubricants) competes on a combined product-and-service model. Their food-grade, PTFE-thickened solutions and Total Corrugator Plant Lubrication service illustrate a route to lock-in through plant conversions and lifecycle services that reduce total cost of ownership for buyers.
- LUBCON and IKV Tribologie operate as focused specialists, targeting technical niche applications and compliance-driven segments with NSF H1-registered products, quick-response technical support, and regional presence that appeals to converters with specific certification needs.
- Adjacent chemistry and materials developments — for example, coatings and inks with improved grease resistance showcased by suppliers in late-2025 — change the operational interface between grease and substrate. These cross-supply chain interactions are emerging negotiating points between packaging material suppliers and lubrication providers.
Strategic implications and recommended moves for 2026
For executive teams building 2026 plans, the report highlights a set of prioritized actions that create optionality and de-risk exposure to raw-material and regulatory shocks:
- Procurement diversification: Establish dual-source contracts for premium high-temperature greases and map alternative-thickener suppliers to mitigate single-supplier risk. Include supply continuity clauses and multi-year pricing collars tied to raw-material indices.
- Certification roadmap: Require NSF H1 (or equivalent) compliance where lines produce food packaging. Make certification a gate in supplier RFPs and include periodic re-audits in vendor terms.
- Service-led conversions: For converters aiming to reduce downtime, pilot plant conversions using service packages (lubrication audits, conversion trials, and predictive monitoring) rather than spot-product switches. Track maintenance interval improvements and capture actual TCO impacts to justify roll-outs.
- R&D and testing protocols: Allocate budget to qualification testing for non-fluorinated alternatives — including thermal cycling, wear particles monitoring, and substrate interaction tests — before committing to fleet-wide changes.
- Cross-supply chain coordination: Coordinate procurement and technical teams with ink and coating suppliers to ensure grease compatibility, particularly as packaging surface technologies evolve.
- Scenario planning and hedging: Use scenario-based planning to model upstream raw-material constraints and regulatory changes (including potential REACH-like actions) and build contingency capex and inventory strategies accordingly.
What PW Consulting’s report delivers (practical content)
The full report is built for action: it combines robust market-sizing and forecast models with operationally focused tools that can be executed during 2026 planning cycles. Highlights include:
- A verified market-size baseline and a transparent CAGR forecast to 2032, enabling finance teams to quantify near-term budget envelopes for lubricant spend.
- Supplier scorecards and a competitive playbook describing product portfolios, certification coverage, service models, and win-loss patterns observed in customer conversions.
- A regulatory and raw-material risk map with trigger points for formulation sensitivity and sourcing contingency options.
- Technical evaluation templates and an equipment-level pilot checklist for safe, repeatable grease qualification in plant environments.
- Commercial negotiation levers and contracting templates designed to protect buyers from supply shocks while allowing suppliers to monetize performance improvements.
- Scenario analytics that connect packaging demand forecasts to grease consumption patterns under multiple recovery and cost-inflation assumptions.
How to use this intelligence in 2026 planning cycles
Executives, procurement leads, and plant managers should use the report in three immediate ways:
- Inform the 2026 procurement RFP: use supplier scorecards and certification filters to structure RFPs that prioritize continuity, compliance, and demonstrable performance gains.
- Design pilot programs: deploy the report’s pilot checklist across representative lines to measure real-world maintenance interval shifts, lubricant consumption, and interfacing risks with inks and substrates.
- Support capital allocation: feed forecast scenarios into maintenance-capex planning to determine whether investments in bearings, seals, or advanced lubrication systems produce superior ROI versus repeated lubricant-based interventions.
Decision primers for specific stakeholders
- C-suite and strategy teams — incorporate supplier concentration metrics and sensitivity to raw-material regulation in portfolio scenarios and M&A screening.
- Procurement — implement multi-source strategies with contractual protections linked to performance metrics and certification maintenance.
- Operations — prioritize pilot-based conversions and embed grease compatibility checks into change-control procedures.
- R&D — accelerate qualification of non-lithium thickener systems and alternative synthetics where regulatory or cost risk is material.
Conclusion and next steps
The corrugating grease market is not a niche of purely technical interest — it is a lever for uptime, packaging safety, and cost control. Our research shows a clear growth trajectory through the rest of the decade and identifies the practical interventions that create value in 2026 planning cycles. PW Consulting’s full report contains the granular segmentation, supplier-by-supplier benchmarking, and downloadable operational templates that decision teams need to execute with confidence.
To access the complete dataset, segmentation tables, supplier contact map, and the operational playbook, download the full report or contact PW Consulting’s Industrial Lubricants practice. For immediate inquiries and enterprise licensing options, visit: pwconsulting.com/reports/corrugating-grease-market.
For detailed analysis of this topic, please visit the official page: Corrugating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


