



PW Consulting: TiO₂ Pigment Market Hits USD 22,240.11 Million in 2025 — Poised for 4.6% CAGR Through 2032

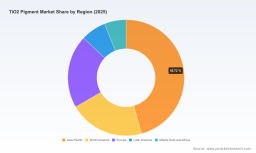
TiO2 Pigment Market — 2026 Strategic Preview
Executive summary
PW Consulting’s TiO2 Pigment Market report is built for commercial and strategic leaders who must make high-consequence decisions in 2026. The global TiO2 pigment market reached approximately USD 22.24 billion in 2025 and is projected to expand to roughly USD 23.38 billion in 2026, progressing to an estimated USD 30.47 billion by 2032. That trajectory implies a mid-single-digit compound annual growth rate (CAGR) of 4.6% over the 2026–2032 forecast window — a profile that rewards disciplined portfolio repositioning, feedstock risk management, and selective capacity investment.
TiO₂ Pigment Market
Why this matters for 2026 corporate decision-making
- Timing capital deployment: With demand growth steady but not explosive, 2026 is a year to prioritize retrofit, debottlenecking and margin protection over large greenfield builds unless executed with feedstock guarantees.
- Price and margin management: Volatile feedstock and input pricing — and regulatory-driven cost increases — mean producers and buyers must adopt flexible contracting, dynamic hedging, and tiered pricing strategies.
- M&A and consolidation playbook: Market concentration metrics indicate meaningful advantages for scale players; strategic acquisitions and bolt-ons remain effective routes to capture synergies and improve utilization.
- Regulatory readiness: Evolving rules on process emissions and waste (notably for sulfate-process producers in major jurisdictions) require compliance capex and operational redesign to avoid disruption to supply and market access.
What PW Consulting’s report delivers (practical, transaction-ready content)
- Integrated market model (2020–2032): demand-supply modeling with scenario variants (baseline, downside, upside) and sensitivity toggles for feedstock cost, tariffs, and demand shocks.
- Price and margin deck: forward price curves and break-even maps for chloride- and sulfate-process economics across typical operating footprints, including working-capital and freight assumptions.
- Plant-level capacity & utilization framework: a methodology to assess brownfield upgrade economics, near-term debottleneck options and greenfield capex thresholds (note: detailed plant-level tables are available in the full report).
- Regulatory and ESG matrix: jurisdictional permitting risk, likely timeline impacts, and recommended mitigation actions for producers subject to REACH-like processes and national industrial policies.
- M&A due diligence toolkit: valuation multiples calibrated to TiO2 economics, integration checklists (feedstock, logistics, downstream exposure), and a playsheet for post-acquisition margin capture.
- Commercial playbook for buyers: procurement negotiation templates, indexation alternatives, and structural hedging approaches to stabilize input-driven cost passes.
- Executive dashboards: KPIs and early-warning indicators (feedstock price triggers, capacity additions, regulatory milestone breaches) to alert management teams and investors.
Market dynamics shaping 2026 strategic choices
Several structural and near-term dynamics underpin the 4.6% CAGR profile and will shape tactical choices in 2026:
TiO₂ Pigment Market
- End-market demand mix: Steady demand from coatings and plastics remains the primary growth engine, while paper, inks and specialty applications provide margin differentiation for premium products.
- Feedstock pressure: Titanium slag and other feedstock prices spiked through 2023 amid supply tightness (industry sources recorded roughly an 18% year-over-year increase in Q3 2023). Cost pass-throughs to end users have been uneven, elevating margin dispersion across the value chain.
- Price level and volatility: Reported average TiO2 prices in established markets rose between 2022 and 2023, contributing to revenue resilience for vertically integrated players; companies without feedstock control continue to face margin squeeze during price spikes.
- Regulatory complexity: Policy measures such as EU REACH authorizations for certain sulfate-process operations, and national industrial capacity controls in major producing countries, are shaping the viable investment set and require proactive compliance planning.
- Trade policy risk: Import duties and trade measures create persistent arbitrage opportunities and cost shocks for cross-border supply chains (notably heavy tariff schedules on some trade lanes), making sourcing strategy a live strategic concern in 2026.
Competitive landscape — who matters and why
The industry features a mix of global-scale integrated players, large regional producers and specialty producers focused on performance niches. Market concentration is meaningful: the top three producers command a substantive share of supply, and the top five account for more than half of market capacity — a structure that rewards scale, integration and channel control.
TiO₂ Pigment Market
- Chemours Company — Ti‑Pure brand: Strong premium brand recognition and established channel relationships in coatings and plastics; incremental value comes from product performance and commercial coverage.
- Tronox Holdings plc — integrated model: Vertical integration into mining and feedstock creates cost and security advantages; reported record TiO2 sales volumes demonstrate executional scale on the demand side.
- Venator Materials PLC — restructuring for resilience: Post-restructuring balance sheet improvement positions the company to invest selectively and defend market position following its Chapter 11 emergence.
- Lomon Billions Group — capacity footprint: Recent capacity additions brought the group to a materially larger installed base; scale in both chloride and sulfate routes positions it as a swing supplier in global markets.
- Major Chinese producers and state-owned groups: A diverse set of domestic champions plays a pivotal role in feedstock sourcing, regional pricing and export dynamics — constrained, however, by policy limits on large new sulfate projects.
- Specialty and regional players (Japan, Europe, Czech Republic): These firms retain leadership in niche, high-performance segments where tight product specifications and technical support create defensible margins.
Strategic implications by stakeholder
- Producers — Prioritize margin capture: Focus 2026 capex on debottlenecking and product premiumization while locking feedstock via long-term offtakes or upstream investments. Evaluate chloride-process conversions where regulatory and commercial math supports it.
- Buyers (coatings, plastics, paper) — De-risk supply: Move to blended sourcing, layered contract tenors and selective indexation to maintain cost predictability while preserving access to high-performance grades.
- Investors — Seek asymmetric value: Target assets with feedstock access, under-utilized capacity that can be consolidated, or specialty positions with differentiated technical barriers to entry. Avoid overpaying for low-margin commodity positions in regions with tariff exposure.
- Policy & compliance teams — Plan for enforcement: Incorporate regulatory scenarios (authorization delays, stricter waste requirements, export controls) into operational continuity plans and capex timelines.
Decision checklist for 2026 (what to watch this quarter)
- Feedstock price trendline and logistics costs — set alert thresholds for when margin remediation actions must trigger.
- Announced capacity start-ups and brownfield upgrades by large suppliers — map geopolitical exposure and potential volumetric swings.
- Regulatory milestones (REACH authorizations; national approvals) — confirm lead times and contingent capital needs.
- Balance sheet health of key suppliers — follow restructuring outcomes and working-capital stress indicators to anticipate supplier exits or consolidation opportunities.
- End-market demand signals in coatings and packaging — correlate with regional construction and automotive OEM order books to refine demand forecasts.
How PW Consulting can help
Our TiO2 Pigment Market product is intentionally designed as a decision-enabling deliverable. The executive report you are reading is a strategic preview; the full PW Consulting package includes the model, plant-level assessment, proprietary benchmarking data and an implementation playbook for suppliers, buyers and investors. Clients engage us for tailored executive briefings, bespoke financial models, and M&A diligence that translate these insights into executable 90–180 day plans.
Closing — a “trailer” not the film
This article has highlighted the structural storylines and provided the high-level evidence that should shape corporate choices in 2026: steady mid-single-digit growth, meaningful feedstock and regulatory risk, and competitive advantage concentrated among integrated and scale-minded players. PW Consulting’s full TiO2 Pigment Market report contains the detailed segmentation, plant-by-plant analytics, and transaction-level models that we intentionally withhold here to preserve the commercial value of the underlying work. For an executive briefing, model access or to download the full report, contact PW Consulting and request the TiO2 2026 Strategic Pack.
For detailed analysis of this topic, please visit the official page: TiO₂ Pigment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


