



PW Consulting: Steel Idler Rollers Market to Grow at 4.5% CAGR in 2026–2032, New Report Finds

Steel Idler Rollers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s Steel Idler Rollers Market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) provides a forward-looking, commercially actionable view of a market that is returning to steady expansion. The market is forecast to grow at a compound annual growth rate (CAGR) of approximately 4.5% through 2032, moving from an industry scale measured in the low‑thousands of USD million in the mid‑2020s to a substantially larger install base and aftermarket opportunity by the end of the decade. This preview highlights the implications that growth, technology shifts, input‑cost volatility and a fragmented supplier base have for procurement, product strategy, and M&A decisions in 2026.
Steel Idler Rollers Market
Why this report matters for 2026 decisions
- Timing capex and maintenance cycles: The report translates macro demand trajectories into practical windows for capex (major conveyor installations) and maintenance spend (idler replacement and retrofits), helping asset owners prioritise 2026 budgets to maximise throughput and uptime.
- Supplier selection and commercial terms: With raw‑material pressure and variable lead times remaining prominent, commercial negotiation strategies (fixed‑price windows, hedged procurements, consignment inventory) materially affect total cost of ownership — the report supplies comparative supplier scorecards and procurement playbooks.
- Technology adoption roadmap: Advances in self‑lubricating bearings, corrosion‑resistant coatings and embedded monitoring change the buyer value equation from first cost to lifecycle cost; the study provides an adoption framework and ROI thresholds for sensorised idlers versus traditional replacements.
- M&A and partnership signalling: Buyers and private equity should be able to identify tuck‑in targets and differentiated OEMs (product engineering, service networks, digital IP) better positioned to capture aftermarket and retrofitting revenue streams.
What the full report contains (practical, non‑academic deliverables)
- Market sizing & forecast model: Bottom‑up and top‑down models with scenario runs (base, upside, downside) for 2026–2032, enabling quick sensitivity analysis for different commodity and infrastructure investment pathways.
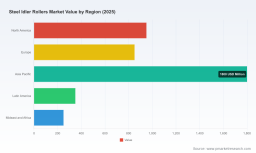
- Segment playbooks: Actionable guidance per commercial dimension (By region, By type, By end‑use) that translate high‑level trends into procurement checklists, retrofit decision trees, and service bundle pricing templates. Note: this preview excludes detailed sub‑segment numerics — they are reserved for the full report.
- Supplier scorecards and heat maps: Comparative assessments across engineering capability, manufacturing scale, OEM certifications, aftermarket density and digital maturity; includes recommended negotiation levers and preferred sourcing strategies for each supplier archetype.
- Cost & TCO models: Modular cost models that incorporate material price scenarios, labour and logistics, bearing life, coating life and monitoring benefits — designed for quick adaptation into capital approval packages.
- Risk matrix & mitigation playbook: Practical mitigation actions for raw‑material shocks, regulatory changes, logistics disruption and warranty/risk allocation in supply contracts.
- Technology & IP landscape: Mapping of incremental innovations (coatings, bearings, sensorisation), patent activity and likely technology adoption curves with implications for product roadmaps and aftersales monetisation.
- Implementation templates: Tender and RFP templates, technical acceptance test lists, and KPI dashboards to measure idler performance post‑installation.
Market dynamics and near‑term risks
Three structural dynamics will shape outcomes for suppliers and buyers in 2026:
Steel Idler Rollers Market
- Input volatility: Steel price swings remain a dominant margin driver for idler manufacturers; industry tracking indicates high‑grade alloy steel can vary by as much as c.18% year‑over‑year. Procurement strategies that fail to account for these moves will see margin compression or sudden price pass‑throughs that disrupt contracts.
- Macro demand from infrastructure and bulk handling: Continued investment in ports, cement manufacturing and regional infrastructure — notably in Southeast Asia and the Middle East — is underpinning demand for heavy‑duty rollers and replacement cycles. These projects create concentrated windows of demand that reward suppliers with manufacturing flexibility and local presence.
- Regulatory and safety drivers: Idlers are judged not only on load capacity but on the role they play in meeting worker safety and environmental standards in abrasive, dusty environments. Durability and low‑maintenance designs can reduce safety incidents and therefore command pricing premiums.
Market pricing signals should also be read against industrial indices: the Producer Price Index for Conveyor and Conveying Equipment Manufacturing stood at 348.731 in March 2026, a useful forward indicator for OEM pricing pressure and contract escalation clauses.
Steel Idler Rollers Market
Technology pulse — what to watch
- Self‑lubricating bearings & coatings: Industry analysis released in early 2026 highlights extended service life from self‑lubricating bearings and advanced corrosion‑resistant coatings for mining environments — a clear route to reduce downtime and warranty claims.
- Smart idlers and predictive maintenance: Product integrations introduced in late 2025 demonstrate the near‑term commercialisation of sensorised rollers. Real‑time condition monitoring shifts the aftermarket business model toward recurring service revenues and predictive spare‑parts supply.
- Design for maintenance: Modular idler designs that reduce mean time‑to‑repair are increasingly important for customers with tight shutdown windows; these designs also enable higher margins in retrofit projects.
Competitive landscape — preview of strategic positions
The sector remains relatively fragmented with market concentration metrics consistent with broad supplier choice: CR3 near 24.5% and CR5 near 34.8%. That fragmentation opens strategic options for both incumbents and new entrants.
- Rulmeca (Italy) — https://www.rulmeca.com: A global manufacturer with deep experience in heavy‑duty rollers for ports and mining. Strengths: international standards compliance, engineering depth. Strategic implication: ideal partner for multi‑site rollouts where spec consistency matters.
- Metso Outotec (Finland) — https://www.metso.com: Focused on high‑performance rollers for mining and aggregates; noted for durable, low‑maintenance solutions. Strategic implication: competitive in high‑abrasion environments and long‑term service contracts.
- Continental (Germany) — https://www.continental.com: Supplies rollers as part of integrated conveyor systems; advantage in system bundling and aftermarket integration. Strategic implication: suits customers looking for end‑to‑end supply and single‑vendor liability.
- ASGCO (USA) — https://www.asgco.com: Specialist in complete idler systems compliant with CEMA; strength in heavy bulk handling. Strategic implication: contender for retrofit projects with demanding standards.
- Douglas Manufacturing, PPI, Martin Engineering (USA) — various URLs: These OEMs compete on heavy‑duty engineering, aftermarket reach and CEMA‑rated products. Strategic implication: strong regional OEMs that are acquisition targets for scale‑seeking buyers.
- HIC Universal (India) & GCS Conveyor (China): Competitive cost structures and expanding export footprints. Strategic implication: cost‑competitive sourcing but attention required on quality control and lead‑time consistency.
- Melco (South Africa), Fenner Dunlop (Australia/Netherlands), Superior Industries (USA): Regional specialists with tailored offerings for mining and aggregates. Strategic implication: valuable local partners for regionally concentrated projects.
Actionable recommendations for 2026
- Hedge material exposure proactively: Negotiate hybrid contracts with both fixed‑price bands and index‑linked escalators tied to steel benchmarks and PPI readings to avoid margin erosion.
- Prioritise sensorised pilots on critical conveyors: Run two to three field pilots of smart idlers on high‑value assets to quantify uptime gains and build a business case for wider rollout.
- Shift procurement from capex to TCO: Re‑score bids on lifecycle cost metrics (bearing life, lubrication cycles, coating longevity) rather than purchase price alone; include mandated acceptance testing and penalty clauses for warranty breaches.
- Targeted M&A and partnerships: For strategic acquirers, prioritise niche players with strong aftermarket networks or sensor IP rather than purely volume manufacturers — the aftermarket drives predictable revenue.
- Flexible manufacturing and local-footprint strategies: Build or partner for regional manufacturing near major infrastructure corridors to shorten lead times and reduce logistics risk.
- Design for maintainability: Require modular idler specifications that reduce downtime and enable faster interchangeability during planned maintenance windows.
How PW Consulting can support 2026 execution
PW Consulting offers a suite of implementation services tied directly to the research: bespoke market landscaping, supplier due diligence, TCO and contract modelling, procurement playbooks, pilot design and execution support for sensorised idlers, and M&A advisory focused on value drivers in the aftermarket. Our templates and model libraries are designed to be plugged into capital approval processes and tender cycles for immediate use.
Next steps
This article is a strategic preview intended to demonstrate the report’s depth while reserving the full sub‑segment datasets, granular competitive scoring and downloadable Excel models for the proprietary report. For access to the full Steel Idler Rollers Market report (including detailed regional, type and application breakdowns, supplier scorecards, and the downloadable forecast model), please visit the PW Consulting report page or contact our industry team for a demo and procurement package.
For detailed analysis of this topic, please visit the official page: Steel Idler Rollers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


