



PW Consulting Forecast: Low Fat Soya Flour Market to Grow from USD 586.39 Million in 2025 to USD 865.54 Million by 2032 at a 5.72% CAGR (2026–2032)PW Consulting: Oat Flakes Market Forecast to Reach USD 9,411.39 Million by 2032

Low Fat Soya Flour Market 2026: Strategic Insights for Executives — A PW Consulting Briefing
As global food manufacturers, ingredient traders, and investment committees plan capital allocation and product roadmaps for 2026, Low Fat Soya Flour is shifting from a niche functional ingredient to a strategic building block for protein fortification, plant-based product innovation, and cost-efficient formulation. PW Consulting’s new market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes commercial intelligence, supply-chain dynamics, and competitive positioning to convert market trends into clear, executable corporate choices.
Low Fat Soya Flour Market
Executive snapshot
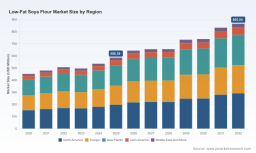
The low fat soya flour market recorded steady expansion through 2020–2025, rising from roughly USD 452 million in 2020 to USD 586 million in 2025. Our base-year assessment (2025) and forward-looking scenario analysis project the market to reach approximately USD 865 million by 2032, reflecting a compound annual growth rate of ~5.72% across the 2026–2032 forecast window. Market concentration is moderate — the top three players account for c.38.5% of market revenues and the top five roughly 52.2% — leaving room for regional specialists, co-ops and niche ingredient innovators to capture share.
Low Fat Soya Flour Market
Why 2026 is a decision inflection point
-
Supply-side reconfiguration: Recent capacity investments and new entrants have altered bottlenecks in key crushing and flour-processing corridors. Executives must decide in 2026 whether to secure long-term off-take, invest in captive processing, or pursue tolling arrangements to stabilize supply.
Low Fat Soya Flour Market -
Product architecture: Low-fat variants (high-protein, low residual fat) are becoming baseline specs in bakery, meat analogs, and fortified beverages. Formulation choices made in 2026 will lock-in cost and label attributes for multi-year product cycles.
-
Risk management: Agricultural input volatility, shifting crush rates and trade classification changes are compressing margins for downstream manufacturers; 2026 is the window for hedging, sourcing diversification and contractual innovation.
Market dynamics and contextual drivers
-
Demand composition: Protein-fortification and plant-based product development remain the primary growth engines. Consumer preference for high-protein, lower-fat formulations underpins steady off-take across bakery, meat alternatives and nutrition segments.
-
Raw material and crush trends: In early 2026 soybean meal prices displayed regional variation, with CIF reference points near USD 316/MT in the U.S. during February. Concurrently, USDA lifted the 2025/26 U.S. soybean crush forecast to a record 2.61 billion bushels, indicating a structural increase in processing throughput that will influence meal and flour availability.
-
Regulatory context: Low-fat soya flour continues to fall under established international tariff classification (HS Code 12081000), which has implications for cross-border pricing, duty planning and preferential tariff utilisation in multi-jurisdiction sourcing strategies.
-
Innovation and product launches: The market is seeing higher-protein soy flours and ultra-high-protein variants targeted at sustainable protein propositions; these introduce new formulation options but also require commercial validation and supply assurances.
Competitive landscape — strategic positions
Our competitive analysis profiles global processors, regional specialists, and co-operatives to show tactical options for partners and competitors.
-
Cargill, Incorporated (Minneapolis) — Offers branded defatted/low-fat soy flours (e.g., Prolia®) with ~50% protein positioning for bakery, snacks and meat applications. Cargill’s strength lies in integrated supply chains, formulation support, and established food-industry relationships that reduce time-to-market for co-developed concepts.
-
Archer Daniels Midland (ADM, Chicago) — ADM is a large-capacity global processor with a broad portfolio including non-GMO options, enabling scale contracts and consistent quality for multinational food companies. Their value proposition centers on secure supply and program-level sourcing.
-
Tiger Soy, LLC (Mexico, Missouri) — A regional specialist focusing on reduced-fat and low-fat, non-GMO and gluten-free lines sourced from local farmers. Their advantage is traceability and fast-cycle custom batches for mid-size food manufacturers.
-
Soy Austria Produktions GmbH (Austria) — European producer of non-GMO semi-defatted flours, positioned to serve premium ingredient requirements and regional certification demands.
-
Agricultural Cooperative BACEX (Vojvodina) — A cooperative model that offers competitive cost structures and direct farmer linkage, attractive for buyers seeking origin differentiation and price resiliency in Eastern Europe.
-
Bic Services (Netherlands), Seasons International (India), CHS Inc. and Bunge — Each brings distinct strengths: specialty ingredient development, export capacity, cooperative member supply integration, and global crushing/processing networks respectively. These companies enable varied commercial strategies from local bespoke supply to global program buying.
Recent strategic moves shaping the supply picture
-
Facility expansions among processors (e.g., a new plant in Kansas that materially increases crush and ingredient throughput) are relieving capacity tightness in certain corridors and create new arbitrage opportunities for buyers willing to re-route logistics.
-
Product innovation (for example, launches of ultra-high protein soy flours) is broadening the addressable set of formulations for plant-based and fortified foods, but also raises quality-control and specification hurdles that buyers must validate before scaling.
What PW Consulting’s report delivers — practical outputs for 2026 decisions
We built the study as a decision-support toolkit, not an academic exercise. Key deliverables include:
-
Verified market sizing and a scenario-capable financial model (2026–2032) that allows users to run custom price, volume and margin scenarios linked to input-cost and crush-rate assumptions.
-
Supply-chain maps and supplier scorecards (quality, capacity, certification, ESG exposure) that convert competitive intelligence into shortlist recommendations for long-list/short-list selection.
-
Go-to-market playbooks for ingredient companies and food manufacturers: three pragmatic routes — defend (scale & integrate), niche (formulation-led differentiation), and partner (co-development & supply contracts).
-
Contracting templates and risk mitigations for 2026 negotiations (indexed off-take clauses, flex-buys, multi-sourcing guardrails, and logistics contingency plans).
-
M&A and CapEx decision heuristics, including an invest/defend framework calibrated to market concentration metrics and regional processing economics.
-
Regulatory and trade implications — compliance checklists and tariff planning tied to international codes and common certification pathways.
How corporate leaders should use these insights in 2026
-
Procurement: Reassess sourcing strategy to balance cost and continuity. Consider partial vertical integration or strategic tolling partnerships where feedstock risk and freight volatility threaten margins.
-
R&D and innovation: Prioritise pilot programs that leverage high-protein, low-fat variants for label-differentiated launches. Use the report’s formulation risk matrix to shorten validation cycles.
-
Commercial strategy: Align pricing and promotional plans with projected market growth and competitor capacity expansions. Where concentration is moderate, targeted partnerships or exclusivity in regional supply can create defensible advantages.
-
Investors & Boards: Use the scenario model to stress-test returns for capacity investments versus contract acquisition. The market’s mid-single-digit CAGR and the identified concentration profile will shape expected IRR horizons and exit options.
Trailer — what we intentionally withhold here
To ensure strategic value for subscribers and prospective clients, this briefing highlights the analytical architecture and executive implications while withholding granular breakdowns of revenue by region, type and application. The full report contains the detailed segment-level modellings, supplier-by-capacity tables, and downloadable Excel scenario files that underpin the recommendations summarized above.
Concluding guidance
2026 is the moment to convert market momentum into structural advantage. Whether the objective is to secure low-cost protein inputs, launch higher-margin plant-based SKUs, or evaluate strategic M&A into processing, the choices made this year will determine cost structures and differentiation for the next investment cycle. PW Consulting’s Low Fat Soya Flour study equips decision-makers with a repeatable playbook — a mixture of data, supplier intelligence, scenario tools and negotiation templates — designed to accelerate confident, risk-calibrated action.
To access the full dataset, segment analyses, and proprietary modelling tools that support these recommendations, visit the PW Consulting report page and download the complete Low Fat Soya Flour Market report.
For detailed analysis of this topic, please visit the official page: Low Fat Soya Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


