



PW Consulting: Skin Measurement Instruments Market Poised to Expand at an 8.24% CAGR, Fueling the Next Wave of Cosmeceutical Innovation

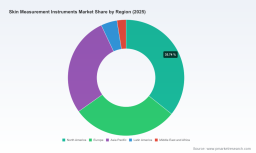
Skin Measurement Instruments Market — Strategic Briefing for 2026
PW Consulting’s latest market intelligence on Skin Measurement Instruments synthesizes five years of historical performance (2020–2025) and a forward-looking 2026–2032 forecast to equip executives, investors, and clinicians with the actionable insight needed to make decisive moves in 2026. The global market has expanded from approximately USD 685 million in 2020 to roughly USD 1,022 million in 2025, and our base-case projection points to continued robust growth (CAGR 8.24%) through the forecast window, with the market approaching USD 1.78 billion by 2032. This briefing highlights strategic implications, competitive vectors, regulatory inflection points, and the practical content you will find in the full report — while reserving the full, segment-level intelligence for report subscribers.
Skin Measurement Instruments Market
Executive snapshot
-
Historical coverage: 2020–2025 (base year 2025). Forecast horizon: 2026–2032.
Skin Measurement Instruments Market -
Market scale and momentum: market more than doubled in valuation across the decade pathway embedded in our model; measured growth is underpinned by a sustained CAGR of 8.24% through 2032.
Skin Measurement Instruments Market -
Market structure: mid-level concentration — our concentration metrics indicate the top three and top five vendors capture meaningful pools of value, leaving ample room for vertical challengers, regional specialists, and platform-enabling players.
-
Segmentation: the market is multi-modal (contact sensors, TEWL, dielectric/TDC, imaging, spectroscopic and multi-parameter platforms) and serves distinct end markets (cosmetic R&D, dermatology, academic research, point-of-sale/retail consultation). Detailed splits and segment-level forecasts are available in the paid report.
Why this matters for 2026 decision-making
-
Regulatory momentum is lowering barriers to market in the United States: a recent reclassification of certain optical diagnostic devices and electrical impedance spectrometers to Class II (with special controls) enables a 510(k) pathway for many instruments, accelerating commercialization timelines and altering product development roadmaps.
-
Reimbursement and hospital outpatient payment changes for CY 2026 are shifting how skin-related procedures and adjunct technologies are billed. These coding and APC adjustments influence hospital purchasing behaviour and the downstream demand for capital imaging systems versus portable point-of-care instruments.
-
Convergence of clinical-grade imaging and AI analytics is creating a two-speed market: high-capability capital equipment for clinics and research, and validated portable devices for point-of-care and consumer-facing use. Each requires distinct regulatory, clinical-evidence, and go-to-market playbooks.
Key market dynamics driving near-term growth
-
Evidence-driven claims and regulatory scrutiny are compelling cosmetics and device manufacturers to invest in validated measurement systems and robust clinical protocols.
-
AI-enabled image analysis and 3D mapping are expanding the value proposition of imaging platforms from simple visualization to quantifiable decision-support tools for clinicians and consumer advisers.
-
Portability and non-invasive measurement technologies (including dielectric constant methods and TEWL measurement) are enabling new clinical workflows and at-home monitoring — creating recurring revenue opportunities via software and services.
-
Channel evolution: aesthetic clinics and specialty dermatology practices are increasingly purchasing capital imaging systems to differentiate offerings, while retail and personalized beauty consultation channels adopt lower-cost, turnkey analyzers supported by cloud analytics.
-
Standardization pressures (ISO, CE, 510(k) pathways) are driving consolidation among vendors who can demonstrate compliance and strong clinical documentation.
Competitive landscape — who matters and strategic implications
-
Courage + Khazaka electronic GmbH (Köln, Germany) — recognized for gold-standard probes and modular multi-probe systems used in laboratory and clinical research. Strategic implication: incumbency in validated measurement creates high switching costs for R&D customers; challengers must match traceability and calibration regimes or own niche clinical endpoints to compete.
-
Delfin Technologies (Finland) — strong in portable, peer-reviewed devices (including TDC/lymphedema diagnostics and layered hydration meters). Strategic implication: validated portability paired with cited evidence makes Delfin an attractive partner for telehealth and managed-care pilots.
-
Canfield Scientific, Inc. (Parsippany, NJ) — leader in VISIA® and VECTRA® 3D imaging; recently launched a next-gen VISIA that integrates AI-driven facial analysis (March 2026). Strategic implication: the leader’s product refresh sets a bar for 3D + AI feature sets and will reframe competitive expectations for consultation and procedural planning tools.
-
FotoFinder Systems GmbH — specialist in dermatology imaging and AI lesion assessment; acquisition-led expansion into handheld solutions extends reach into point-of-care. Strategic implication: combining total-body mapping with handheld follow-up tools is a winning play for longitudinal dermatology workflows.
-
Emerging and specialized providers (Cortex Technology, Callegari, Bomtech, 3Gen/DermLite, HEINE, Michelson Diagnostics, DermaSensor) — collectively, these vendors create a vibrant ecosystem spanning dermatoscopy, OCT, spectroscopy, and salon/professional analyzers. Strategic implication: partnerships and modular integrations (hardware + SaaS) will be critical to scale distribution and clinical validation affordably.
What the full PW Consulting report delivers (practical, operational items)
-
Granular market model (historical & forecast) by technology tier, application, and channel — with scenario and sensitivity analysis to stress-test pricing, adoption rates, and regulatory timelines.
-
Competitive matrix and vendor scorecards with capability mapping, go-to-market footprints, product roadmaps, M&A activity trackers, and vendor financial proxies.
-
Regulatory playbook and submission templates tailored to US (510(k)), EU (CE/MDR), and key APAC jurisdictions, plus a stepwise clinical-evidence generation plan aligned to intended claims.
-
Reimbursement and procurement mapping, including hospital outpatient APC implications and payer engagement strategies for clinical-grade devices.
-
Actionable GTM blueprints for manufacturers, distributors, and clinic operators: pricing archetypes, channel economics, sales-force segmentation, and service/consumable revenue levers.
-
M&A and partnership shortlist with play-by-play rationale: tuck-in vs. platform buy, capability vs. market-access targets, and integration risk benchmarks.
-
Primary research appendices: interview summaries with clinicians, procurement officers, and R&D heads; methodological notes; and downloadable data tables (note: detailed segment tables require subscription).
Actionable 90–180 day priorities for 2026
-
For device manufacturers: accelerate regulatory readiness for the 510(k) pathway where applicable; prioritize clinical studies that support both safety and differentiated efficacy claims; and architect modular hardware that can host cloud analytics and subscription services.
-
For investors and corporate development: focus diligences on imaging + AI platforms with defensible datasets and OEM relationships; seek targets that close capability gaps (spectroscopy, OCT, or strong clinical trial portfolios) rather than only revenue scale.
-
For dermatology and aesthetic operators: evaluate ROI for capital imaging upgrades versus portable validated systems; design bundled service offerings (diagnostics + treatment + follow-up analytics) to capture higher lifetime value.
-
For cosmetics R&D teams: form early-stage co-development and measurement partnerships with vendors able to provide traceable, validated endpoints to shorten product claim cycles.
-
For distributors: invest in field-service capabilities and outcome-focused training to reduce churn and increase consumables/analytical-subscription attach rates.
M&A and partnership signals — where consolidation makes sense
The market’s mid-level concentration and distinct technology adjacencies create attractive consolidation corridors: (1) horizontal roll-ups to aggregate regional share and calibration standards; (2) vertical integration pairing hardware leaders with AI/software analytics providers to capture higher-margin services; and (3) bolt-on clinical evidence houses to accelerate claim substantiation. Buyers should prioritize integration targets with clean regulatory histories and modular architectures to minimize technical debt.
Concluding perspective and next steps
2026 is a strategic inflection point for skin measurement instruments: regulatory changes accelerate market entry in major geographies, AI-enabled imaging redefines clinical utility, and service-first business models unlock recurring revenue. PW Consulting’s report provides the playbook required to translate these trends into executable 12–36 month plans. For vendors, payers, and clinical operators preparing capital allocation, R&D prioritization, or M&A activity in 2026, the report delivers the evidence base and decision frameworks necessary to act with confidence.
To access the full dataset, vendor benchmarks, and proprietary scenario models that underpin the insights summarized here, visit the PW Consulting report page or contact our industry practice lead for a briefing and sample executive dashboard.
For detailed analysis of this topic, please visit the official page: Skin Measurement Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


