



PW Consulting Forecast: IL-11 Market to Reach USD 848.2 Million by 2032, Growing at an 8.01% CAGR as North America Leads with USD 210.84M

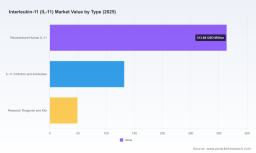
Interleukin-11 (IL-11) Market — Strategic Briefing from PW Consulting
Executive summary
PW Consulting’s Interleukin-11 (IL-11) Market report (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the actionable intelligence required to make high‑stakes 2026 decisions across R&D, manufacturing, M&A and commercialization. The IL‑11 space is on a sustained expansion path with a compound annual growth rate (CAGR) of 8.01% across our forecast period. After recovering from a measured growth profile in the early 2020s, the total market shows clear scaling dynamics into the late 2020s and early 2030s, driven by intensified preclinical activity, expanding research applications and an emergent therapeutic inhibitor pipeline. This briefing outlines the strategic implications and the operational playbook included in the full report — while deliberately withholding granular segment tables and proprietary split figures to encourage direct access to the underlying analysis.
Why this report matters for 2026 strategic planning
- Timing and investment calibration: With a mid-single-digit-plus CAGR projected through 2032, 2026 is a pivotal year to commit to strategic supplier agreements, scale manufacturing capacity selectively, or enter licensing discussions tied to the therapeutic inhibitor pipeline.
- Risk versus optionality: IL‑11 is primarily available as a research‑grade product today. Near‑term commercial value hinges on clinical readouts for IL‑11 pathway inhibitors — a binary but material value driver that alters supplier, partnership and R&D priorities.
- Procurement and supply chain decisions: Consolidation among leading reagent suppliers means procurement strategies must balance supplier concentration risk, lot‑to‑lot consistency, and format differentiation (carrier‑free, lyophilized, animal‑free, expression host choices).
Market trajectory — a data‑driven view
Our market model charts the total IL‑11 market from the early 2020s through 2032. The market expanded steadily from the start of the decade, reached a material inflection by the mid‑2020s, and our forecast shows continuation of that momentum into the early 2030s. The forecast embeds conservative, base and upside scenarios tied to three levers: acceleration of fibrosis and oncology research funding, the pace of clinical progress with anti‑IL‑11 candidates, and reagent providers’ ability to deliver scaled, consistent product formats (including animal‑free and carrier‑free offerings).
Key macro takeaway: the pathway to therapeutics is the high‑impact lever — if clinical programs validate therapeutic hypotheses, adoption of IL‑11‑related reagents, companion diagnostics and downstream services will jump relative to the base case; conversely, prolonged negative or ambiguous clinical outcomes would slow commercial expansion but still leave a resilient research reagent market.
Demand drivers and constraints
- Demand drivers: intensified fibrosis and oncology research, growing interest in cardiovascular/renal immunomodulation, standardization of preclinical models requiring higher‑quality cytokines, and laboratories shifting to animal‑free reagent formats.
- Constraints: regulatory positioning (IL‑11 remains research‑only per major regulators), lot variability concerns, and supplier concentration that can create spot shortages at inflection points.
- Operational friction points: customers increasingly request lot‑specific bioactivity data, validated cold‑chain logistics, and consistent formats — requirements that raise manufacturing and QC costs for suppliers but improve downstream reproducibility for labs and developers.
Regulatory and clinical landscape
Regulatory reality: IL‑11 (native/recombinant) is not approved by FDA or EMA for therapeutic use; commercial products on the market are sold as research‑grade and labeled “For Research Use Only (RUO), not for diagnostic or therapeutic procedures.” This limits current commercial pathways to reagent and kit sales, service contracts, and preclinical collaborations.
Clinical activity: independent clinical programs targeting the IL‑11 pathway — notably anti‑IL‑11 antibodies and other inhibitors — are progressing in fibrosis indications. These trials are the pivotal watchpoint for 2026: positive clinical validation would unlock a fast‑track for downstream translational products, increase demand for GMP‑grade materials, and reconfigure partner priorities. Negative or slow readouts would emphasize the reagent market and delay therapeutic commercialization.
Market structure and concentration
The IL‑11 market exhibits a moderate‑to‑high concentration profile: the top three suppliers account for a clear majority of research‑grade supply, with the top five further concentrating the market. This concentration has three practical consequences for strategy:
- Established suppliers dictate quality baselines and commercial terms; new entrants must demonstrate superior value (cost, format, quality) or niche specialization.
- Supply continuity planning is essential — single‑source dependencies materially raise operational risk if research or clinical programs scale quickly.
- Partnership and M&A opportunities are available for mid‑sized reagent firms seeking scale or for investors looking to consolidate capabilities around production quality and lot‑release testing.
Competitive dynamics — profiles and implications
PW Consulting’s report includes deep vendor profiles. Below is a high‑level analysis of core players whose positioning shapes the market.
- Sino Biological (Beijing, China) — supplier of high‑purity recombinant human IL‑11 in multiple formats. Strengths: vertical manufacturing scale, wide format availability, competitive global distribution. Strategic implication: attractive partner for volume procurement and custom reagent development, but buyers should conduct lot‑specific activity verification.
https://www.sinobiological.com - R&D Systems (Bio‑Techne) (Minneapolis, MN, USA) — known for bioactive proteins with lot‑specific activity testing. Strengths: rigorous quality and brand trust in translational research. Strategic implication: preferred for studies where lot activity data and reproducibility are prioritized.
https://www.rndsystems.com - PeproTech (Thermo Fisher Scientific) (Cranbury, NJ, USA) — offers animal‑free recombinant IL‑11 emphasizing lot consistency. Strengths: integration into large distribution channels and validated animal‑free processes. Strategic implication: strong choice for labs transitioning away from animal‑derived components and for customers needing consistent upstream sourcing.
https://www.thermofisher.com/peprotech - MedChemExpress (Monmouth Junction, NJ, USA) — provides recombinant IL‑11 with detailed bioactivity and storage guidance. Strengths: robust technical documentation and customer support. Strategic implication: well‑suited for investigators that require clear handling protocols and technical service.
https://www.medchemexpress.com - ProSpec (Ness Ziona, Israel) — produces IL‑11 expressed in E. coli, targeted at cytokine research. Strengths: cost‑effective E. coli expression workflows and niche cytokine expertise. Strategic implication: competitive option for cost‑sensitive preclinical programs; buyers should evaluate how expression host choice impacts downstream assays.
https://www.prospecbio.com
What the full PW Consulting report contains (practical deliverables)
Our release provides a structured, executable suite of deliverables designed for decision makers who need to act in 2026:
- Proprietary market model (time series and scenario outputs) with sensitivity sliders for clinical success, pricing and adoption speed.
- Supplier scorecards and procurement playbooks (quality, format, lot‑testing, lead times, geographic footprint).
- Clinical pipeline mapping and go/no‑go decision frameworks for business development and licensing teams.
- Regulatory checklist and gap analysis for converting research‑grade reagents to GMP‑grade materials required by translational programs.
- Commercialization and pricing frameworks for reagent and kit suppliers anticipating therapeutic validation.
- M&A shortlist with diligence templates focused on manufacturing scalability, QC capability and IP ownership.
Note: To preserve competitive sensitivity and to follow our “preview” principle, this press release omits detailed regional and application splits, pricing tables and raw proprietary figures — these are included in the full report and model package.
Actionable recommendations for 2026
- For reagent manufacturers: prioritize investment in lot consistency and animal‑free options now; secure long‑term supply contracts with tier‑one academic and biopharma labs ahead of potential clinical readout inflections.
- For therapeutic developers and pharma: treat clinical readouts as binary value triggers — stage contingent investment and secure GMP conversion pathways with existing suppliers to accelerate translational timelines if trials succeed.
- For procurement and operations: implement multi‑sourcing strategies for critical lots and build inventory buffers tied to program milestones to mitigate supplier concentration risk.
- For investors and M&A teams: evaluate targets with proven QC systems, scalable manufacturing and strong service offerings (e.g., lot‑specific activity testing), and prioritize deals that deliver rapid capacity scaling.
Methodology and validation
The full study synthesizes primary interviews with suppliers and end users, proprietary demand modelling, patent and clinical trial mapping, and supply chain validation. Historical data (2020–2025) were reconstructed from supplier disclosures, procurement datasets and market channel checks; forward forecasts (2026–2032) employ scenario‑based monte‑carlo analysis that stress‑tests therapeutic success and reagent market resilience.
Next steps — access and engagement
PW Consulting’s Interleukin‑11 (IL‑11) Market report is structured to be immediately operational for 2026 planning cycles. The full report contains the complete segmentation tables, regional and application splits, vendor financial benchmarks, pricing matrices, and downloadable forecasting models — information withheld here to protect the proprietary work that supports client decision making.
To request the full report, schedule a briefing, or commission a custom scenario run tailored to your portfolio or procurement book, contact PW Consulting’s market intelligence team or visit our Interleukin‑11 Market page. Our specialists will walk you through the model and outline how the insights map to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Interleukin-11 (IL-11) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


