



PW Consulting: Ultrasound Market to Hit $12.87B by 2032, 5.97% CAGR Forecast 2026-2032

Navigating the Ultrasound Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
The ultrasound sector is entering a phase of disciplined expansion, where growth is no longer solely driven by volume but by precision, integration, and application-specific engineering. As enterprise leaders map capital allocation and technology roadmaps for the coming cycle, understanding the underlying revenue trajectory, competitive fragmentation, and operational shifts across the supply chain becomes a critical differentiator. This article distills the strategic contours of the market environment and positions our latest Ultrasound Market research as an operational compass for 2026 planning.
Worldwide Horse Bedding Products Market
The Growth Arc: From Baseline Momentum to Sustained Trajectory
Over the past half-decade, the industry has demonstrated a consistent upward revenue curve, moving from approximately 5.96 billion USD in the base reference year to a projected 8.59 billion USD by 2025. This historical progression reflects maturation across multiple application verticals, improved manufacturing yields, and the gradual replacement of legacy mechanical processing methods with ultrasonic alternatives. Looking forward, the forecast window extends through the early 2030s, with revenue projections advancing toward the 12.87 billion USD range by 2032. The compound annual growth rate over this forecast horizon sits at 5.97 percent, signaling a steady, compounding expansion rather than a speculative spike.
Enterprise Tax Management System Market
For executives evaluating 2026 budgets, this trajectory carries nuanced implications. A mid-single-digit CAGR suggests that market participation will increasingly reward firms that invest in process optimization, hygienic design standards, and modular system architectures, rather than those chasing marginal volume gains through commoditized pricing. The revenue curve also indicates that certain segments will experience divergent performance, meaning aggregate growth figures alone cannot guide procurement or R&D strategy. Understanding where value concentrates and how demand shifts across use cases is essential to avoiding misallocated capital.
Worldwide Equine Veterinary CT Imaging Market
Structural Segmentation: Where Demand Is Redefining Value Creation
The market is structured around multiple dimensions that intersect to shape purchasing behavior, engineering priorities, and supplier positioning. By operational type, diagnostic and therapeutic configurations form the operational backbone of the sector, while ancillary and hybrid categories capture a meaningful share of total activity. Each category serves distinct engineering requirements: diagnostic-style implementations emphasize precision sensing, repeatability, and non-destructive evaluation, while therapeutic and processing-oriented deployments focus on energy delivery, material interaction, and throughput efficiency.
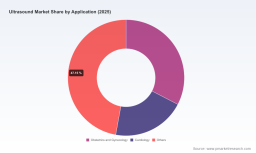
Application-wise, the landscape spans highly specialized verticals and broad industrial use cases. Obstetrics and gynecology continues to represent a substantial share, reflecting enduring demand for reliable imaging and procedural support. Cardiology remains another anchor vertical, driven by diagnostic frequency and integration with broader clinical workflows. Beyond these established pillars, a wide array of additional applications collectively commands a significant portion of market activity, highlighting the technology's adaptability across sectors ranging from medical diagnostics to industrial processing. The diversity of end-use scenarios creates both opportunity and complexity, as buyers increasingly seek systems that can be calibrated to specific material properties, flow rates, and hygiene protocols.
Geographic distribution further influences strategic planning. Revenue activity is spread across multiple regional ecosystems, with North America comprising the largest single contribution, followed by Europe and Asia Pacific in close succession. Latin America and the Middle East and Africa collectively represent smaller but steadily developing footprints. For 2026 decision-makers, regional comparisons must go beyond headline share figures. Supply chain resilience, regulatory alignment, local reimbursement environments, and the availability of skilled service personnel will determine which markets deliver the highest return on deployment investment. Detailed regional revenue breakdowns and application-level share compositions are mapped comprehensively in our full report, enabling planners to model regional scenarios without relying on consolidated averages.
Competitive Landscape: Concentration, Differentiation, and the Battle for Process Integration
The ultrasound market features a cluster of established participants who have secured a dominant position through product specialization, regional service networks, and continuous innovation in cutting, sealing, homogenization, and cleaning technologies. Market concentration remains notable, with the top three firms accounting for approximately 65.5 percent of industry revenue and the top five expanding that share to roughly 73.2 percent. This concentration does not imply a monolithic supply base; rather, it reflects differentiated leadership where firms compete on engineering precision, material compatibility, and integration with automated production lines.
Several core companies define the competitive frontier. Hielscher Ultrasonics, headquartered in Teltow, Germany, centers its offering on high-performance ultrasonic homogenizers, probe-type and flow-through sonicators tailored for food processing applications including extraction, homogenization, emulsification, pasteurization, fermentation, and dairy or beverage workflows. Emerson Electric Co., based in St. Louis, Missouri, advances its Branson brand with ultrasonic cutting systems, cleaners, cell disruptors, and homogenizers designed for food processing, bakery, confectionery, dairy, and portioning tasks that require clean cuts and reduced waste. RINCO ULTRASONICS, operating from Germany, delivers ultrasonic welding and cutting equipment engineered for food portioning, confectionery, baked goods, cheese, and packaging sealing within automated production environments. TELSONIC AG, located in Bronschhofen, Switzerland, supplies ultrasonic cutting sonotrodes, generators, and integrated systems for portioning, sealing, and packaging across confectionery and convenience product lines. Weber Ultrasonics, also based in Germany, provides modular ultrasonic systems for food cutting, packaging and sealing, and utensil cleaning in industrial production settings.
Additional participants reinforce the breadth of competitive capabilities. Dukane, headquartered in Illinois, USA, develops ultrasonic knives, generators, and components that enable clean, precise food cutting in bakery, confectionery, cheese, and layered products without sticking or waste. Herrmann Ultrasonics, from Germany, offers ultrasonic sealing machines and cutting solutions optimized for food packaging and clean cuts in cakes, chocolate, energy bars, and ready meals. Marchant Schmidt, based in the USA, specializes in ultrasonic food-grade cutting systems, including two-stage and continuous process cutters for high-volume sheet products like cakes, brownies, and frozen meals. Sonics & Materials, Inc., also USA-based, delivers ultrasonic processors, cutters, and welding equipment suited to liquid and food processing applications in packaging and high-volume food lines. Together, these organizations illustrate how the market is shaped by application-specific engineering rather than generalized equipment sales.
Recent Product and Innovation Signals Shaping 2026 Planning
Product launches over the past year provide direct visibility into the innovation cadence that will influence 2026 procurement and engineering decisions. Emerson Electric Co. announced a new generation of ultrasonic cutting systems for confectionery and bakery products, signaling continued refinement in frictionless portioning and waste reduction for sticky and multi-layered materials. Marchant Schmidt launched the UC23 Ultrasonic Two-Stage Cutting System, designed for high-volume sheet cake, brownie, and frozen meal portioning, demonstrating a focus on throughput consistency and process continuity. Hielscher Ultrasonics introduced the Stepped Plate Sonicator, enabling intense airborne non-contact ultrasonic thawing of frozen foods such as seafood and meat, expanding the operational envelope of ultrasonic processing beyond traditional cutting and homogenization.
These developments underscore a broader industry pattern: manufacturers are moving toward equipment that reduces mechanical blade dependence, minimizes residue buildup, and improves overall equipment effectiveness in hygienic production environments. The emphasis on non-contact thawing, continuous portioning, and clean-cutting sonotrodes reflects buyer demand for systems that integrate seamlessly into automated lines while supporting stricter food safety and maintenance standards. For procurement teams, evaluating these innovations requires more than comparing feature lists; it demands scenario-based assessment of how each solution interacts with product geometry, throughput targets, cleaning cycles, and line changeover requirements. Our report examines these launch trajectories in context, connecting product announcements to broader adoption drivers and operational outcomes.
Regulatory, Compliance, and Infrastructure Dynamics in Motion
Operational feasibility in the ultrasound sector is increasingly influenced by material certification, hygiene expectations, and process efficiency mandates. Titanium ultrasonic knives are recognized as completely inert and approved by the food industry for use in ultrasonic food cutting equipment, a factor that directly affects material selection, durability, and regulatory acceptance in sensitive production environments. Food-certified ultrasonic cutting solutions are also gaining traction for their ability to reduce maintenance requirements and raise overall equipment effectiveness in industrial food applications, reinforcing the link between compliance readiness and line profitability.
Ultrasonic cleaning of utensils has become a standard application of power ultrasound in food and beverage manufacturing, supporting hygiene targets and process efficiency across high-utilization facilities. In parallel, ultrasonic cutting and sealing systems are enabling precise portioning and packaging for confectionery, baked goods, and cheese without blade maintenance or residue, which is particularly relevant for facilities managing frequent changeovers and stringent sanitation protocols. Frictionless portioning technology is further reducing waste and downtime in sticky and multi-layered products, translating material savings into measurable operational gains. These dynamics illustrate that adoption decisions are rarely driven by a single technical attribute; instead, they emerge from the intersection of food safety mandates, maintenance economics, and throughput reliability. Detailed regulatory mapping and infrastructure implications are unpacked in the full research, where each dynamic is connected to specific operational trade-offs and deployment considerations.
What 2026 Decision-Makers Gain from the Full Research
Macro indicators establish direction, but actionable strategy requires granularity that consolidated summaries cannot provide. Our Ultrasound Market report is built to bridge that gap by combining revenue trajectory analysis with operating-level intelligence across product types, application verticals, regional deployment patterns, and competitive positioning. The study details the scope of coverage, data construction methodology, segmentation frameworks, and scenario modeling tools that enable planning teams to test assumptions before committing resources.
Readers will find structured analysis of how diagnostic, therapeutic, and ancillary system categories are evolving, how application demand is shifting across obstetrics and gynecology, cardiology, and broader industrial use cases, and how regional revenue activity aligns with local supply chain and service dynamics. The report also integrates competitive profiling, recent product development tracking, and regulatory and infrastructure context to help leaders interpret market signals with greater confidence. By linking demand patterns to operational realities, the research is designed to support capital allocation, technology sourcing, and market-entry evaluations with a consistent analytical framework.
Strategic Imperatives as the Cycle Advances
As the ultrasound market progresses toward the next phase of expansion, 2026 strategy will hinge on several interconnected priorities. First, firms must assess whether their equipment portfolios align with the growing premium on hygienic design, non-contact processing, and reduced maintenance burdens. Second, procurement and engineering teams should evaluate how modular system architectures and application-specific tuning influence total cost of ownership across different product mixes and line configurations. Third, regional planning must account for the uneven pace of adoption, local certification pathways, and the importance of service availability in sustaining operational uptime. Finally, competitive positioning will increasingly depend on the ability to demonstrate measurable improvements in waste reduction, portioning precision, and process continuity rather than relying on generalized performance claims.
The market’s mid-single-digit growth rate, combined with meaningful concentration among leading participants and rapid iteration in product capabilities, creates an environment where informed differentiation matters more than ever. Enterprises that map these dynamics early will be better equipped to time investments, select partners, and align technology roadmaps with the operational demands of the coming years.
Accessing the Full Intelligence
This article offers a strategic preview of the market environment shaping 2026 decision-making, but the full Ultrasound Market research contains the detailed segmentation data, regional revenue breakdowns, application-level share analysis, competitive benchmarking, and scenario frameworks necessary for precise planning. To access the complete dataset, methodology notes, and executive dashboards that support board-level reviews and procurement strategy sessions, visit the source report page and download the full study. Continuous intelligence, structured for operational use, is available there for teams ready to move from directional insight to executable strategy.
For detailed analysis of this topic, please visit the official page: Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


