



PW Consulting Forecasts Military Antenna Market to Hit $4B in 2025, 5.6% CAGR Through 2032

Strategic Imperatives in the Military Antenna Market: Navigating Growth, Supply Chain Friction, and Competitive Positioning Through 2032
The global military antenna market is undergoing a structural recalibration that places antenna systems, RF front-ends, and precision-enabled signal architectures at the center of defense modernization. From a strategic advisory perspective, this sector no longer behaves as a passive procurement category. It has evolved into a technology-intensive, program-critical supply chain node that shapes communications resilience, electronic warfare effectiveness, surveillance reach, and the tactical edge of next-generation platforms. The latest PW Consulting market intelligence on the Military Antenna Market is designed to convert this complexity into executive-grade decision clarity, enabling leadership teams to prioritize investments, manage supplier risk, and sequence capacity strategies with greater confidence.
Pre-coating Lubricant Market
The strategic timing of this research is deliberate. Defense budgets are expanding, multi-domain operations are increasing the demand for robust RF connectivity, and advanced aperture technologies are migrating from specialized programs into broader operational fleets. At the same time, export governance, tariff-driven component inflation, and concentrated sourcing for high-performance materials are reshaping both cost structures and delivery timelines. In that environment, the market cannot be evaluated through headline growth figures alone. Decision-makers need a disciplined view of where demand is intensifying, which platforms and functional requirements are absorbing the largest shares of investment, and how incumbents and challengers are differentiating their offerings in a market that remains moderately consolidated.
AMOLED DDIC Market
This report is structured to meet that need. It provides a full retrospective view from 2020 through 2025, then extends the outlook across a forecast horizon from 2026 to 2032. Throughout the analysis, the focus remains on strategic interpretation rather than raw enumeration. The objective is to help executives understand not just how the market is expanding, but why growth is unevenly distributed across frequency regimes, platform environments, mission roles, and supplier ecosystems.
OLED Driver ICs Market
Market Trajectory and the Strategic Meaning of 2026–2032 Growth
The historical record shows a market that has consistently advanced through the 2020–2025 period, reflecting sustained procurement activity and incremental technology upgrades across defense portfolios. Revenue reached approximately USD 3,085 million in 2020 and climbed to about USD 4,000 million by 2025, with year-over-year movement shaped by platform refresh cycles, modernization mandates, and the ongoing replacement of legacy antenna assets. This trajectory matters because it establishes baseline momentum entering the forecast window. A market that has already demonstrated durable lift is better positioned to absorb new requirements, but it also becomes more sensitive to supply disruptions, pricing pressure, and regulatory shifts.
Looking ahead, the forecast period from 2026 to 2032 indicates continued expansion at a compound annual growth rate of 5.6 percent. Under this trajectory, the market is projected to reach roughly USD 4,220 million in 2026 and advance toward approximately USD 5,812 million by 2032. The strategic implication is straightforward: growth is real, but it is not uniform or automatic. Organizations that treat the forecast as a flat tailwind will miss the operational reality that expansion is mediated by program timing, procurement cycles, component availability, and the pace at which technical requirements migrate across communication, surveillance, electronic warfare, telemetry, and satellite communications applications.
From a planning standpoint, the 2026–2032 outlook is most valuable when it is used to inform three executive actions: capacity commitment decisions, supplier diversification strategies, and portfolio alignment with high-demand frequency and platform categories. The report does not simply project aggregate revenue; it connects growth to the operational logic behind procurement. That approach helps leadership teams anticipate where pipeline strength is likely to concentrate, where lead-time risk may become binding, and where competitive positioning will increasingly depend on manufacturability, certification capability, and mission-specific performance assurance.
For executives evaluating market entry, expansion, or partnership opportunities, the macro trajectory also serves as a filter. A 5.6 percent CAGR suggests steady demand creation rather than explosive volatility, which favors organizations that can build repeatable supply, manage qualified component streams, and align with long-cycle defense procurement. At the same time, the upward revenue path indicates that the market is large enough to support differentiated positioning. Winners will likely be those that can translate growth into margin through process maturity, strategic sourcing, and selective technology commitment rather than those relying solely on volume.
Competitive Landscape and the Meaning of Moderate Consolidation
One of the most important strategic features of this market is its moderate concentration. The report surfaces a competitive structure in which the top three firms account for roughly 26.8 percent of market revenue, while the top five firms represent about 32.5 percent. That pattern tells a clear story: no single supplier dominates the field, but leading incumbents hold meaningful positions through specialization, platform certifications, and long-standing defense relationships. For procurement leaders and investors, this balance of fragmentation and concentration creates both risk and opportunity.
On the risk side, moderate concentration means that a handful of established players influence pricing expectations, qualification pathways, and preferred-supplier dynamics on key programs. If an organization depends too heavily on a narrow set of approved vendors, it may face schedule exposure if capacity tightens or if export-control and sourcing constraints slow delivery. On the opportunity side, the market is not so concentrated that entry or expansion is impractical. There remains room for companies that can differentiate through application-specific antenna design, rapid prototyping, ruggedization, and strong integration support. The competitive environment rewards precision positioning more than undifferentiated scale.
The report profiles a broad cross-section of active participants whose strategies illustrate how competitive advantage is being built in practice. Several U.S.-based firms emphasize mission-specific design, prototyping, and manufacturing for military and commercial requirements, reflecting the value of domestic capability in programs where trusted supply and certification speed matter. Others focus on broadband and specialized frequency coverage, including military allocations such as 1350 MHz or 4.4 GHz, demonstrating the importance of frequency fluency in procurement conversations. In the airborne segment, suppliers with electrostatic and lightning protection capabilities show how antenna provision increasingly intersects with broader aircraft protection and certification requirements. High-performance RF and microwave specialists, along with wideband antenna providers, highlight the market’s shift toward systems that must perform under demanding environments and contested spectral conditions. International suppliers add further nuance by bringing HF/VHF/UHF capabilities and specialized mast and antenna solutions into the competitive mix.
Recent contract and program activity reinforces the competitive picture. The market is being shaped by tangible wins across procurement, system integration, and qualification milestones. For example, notable activity includes a procurement award tied to a specific National Stock Number antenna requirement, a significant multi-source contract set spanning airborne communication antennas, anti-jamming GPS systems, and beam-forming antennas for unmanned aerial operations, and a substantial U.S. Navy program focused on antenna array panels for a surface electronic warfare improvement effort. Additional milestones, such as multi-orbit antenna qualification and type certification for in-flight connectivity, along with new manufacturing facility expansion in Europe, indicate that competitive positioning is increasingly tied to certified performance, production scalability, and geographic sourcing strategy.
The strategic takeaway is that competitive advantage in this market is rarely built on product presence alone. It is built on the intersection of frequency capability, platform experience, certification readiness, and the ability to support sensitive programs through complex approval and integration pathways. The report uses these developments to illustrate where incumbent strength is being reinforced and where new entrants or subsidiary capabilities may find traction. Rather than providing a static vendor list, the analysis stresses the behaviors that separate durable competitors from temporary participants.
Dynamics Shaping Procurement, Cost, and Delivery Risk
The market environment entering 2026 is defined by a set of dynamics that directly affect pricing, schedules, and strategic sourcing. Export-control evolution is among the most consequential. In 2025, a U.S. Department of State interim final rule was followed by a final rule, with changes becoming effective later in the year, removing certain Controlled Reception Pattern Antennas for Position, Navigation, and Timing from the U.S. Munitions List and moving them under the Export Administration Regulations. This type of reclassification matters because it alters the compliance pathway for specific antenna technologies and can influence how quickly allied programs can access, integrate, or manufacture particular capabilities. At the same time, export-control friction remains persistent. High-performance apertures tied to sensitive platform electronics and military communications functions continue to face approval delays, and ITAR and sovereign procurement export bottlenecks still affect allied integration schedules and can constrain production scalability for some suppliers.
The regulatory environment therefore has a dual character. On one hand, targeted rule changes can open narrow pathways for faster commerce or integration in defined categories. On the other hand, the broader export-control regime continues to create uncertainty for programs that rely on sensitive RF hardware, especially where antennas are embedded into platforms with restricted mission functions. For procurement leaders, this means that sourcing decisions cannot be made solely on performance or price. Compliance posture, export classification awareness, and supply chain transparency have become strategic variables in program execution.
Material and component supply pressures add another layer of complexity. Rising demand across defense programs can strain trusted-source supply chains for advanced RF components, especially where phased-array antennas depend on gallium nitride on silicon carbide wafers, foundry capacity, packaging, and qualified assembly. When advanced materials and process capacity become constrained, the effect is not limited to unit cost. It also touches lead times, program sequencing, and the pace at which technical upgrades can be delivered into active fleets. In practical terms, the market is entering a phase in which performance differentiation may be limited by manufacturing capacity as much as by design sophistication.
Tariff policy has also influenced the operating environment. Tariff actions on Chinese electronics and communication parts have affected the military antenna market by straining global supply chains and increasing the prices of antenna subcomponents such as RF modules, connectors, and circuit boards. Even when final antenna assemblies are produced domestically or in allied locations, the cost base can still be influenced by upstream component exposure. This dynamic has strategic implications for margin planning, inventory policy, and sourcing diversification. Organizations that rely on concentrated sub-tier supply may find themselves exposed to cost volatility and delivery inconsistency, while those that invest in broader supplier mapping and qualified alternates may gain more stable execution.
Taken together, these dynamics shift the center of gravity in market strategy. The decisive question is no longer simply who can design a capable antenna. The more important question is who can deliver certified performance on time, at a defensible cost, through a supply chain that can withstand regulatory, material, and trade-related pressure. The report addresses these dynamics directly by linking them to procurement behavior, supplier selection criteria, and the practical limits they place on scalability.
What the Report Delivers: Operational Intelligence for Decision-Makers
The PW Consulting Military Antenna Market research is built for use, not just reference. It is structured to support scenario planning, supplier evaluation, investment prioritization, and capability roadmapping. The report combines market sizing, forward projections, segmentation logic, competitive profiling, and event-driven context into a single decision framework. Readers can expect a layered analysis that moves from macro direction to actionable segmentation insights without relying on oversimplified headline figures.
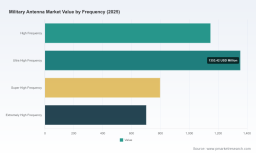
A core strength of the report is its treatment of segmentation as a strategic lens rather than an academic taxonomy. Frequency ranges, platform environments, and mission applications all matter because they influence procurement behavior, qualification requirements, and the economics of manufacturing. The analysis examines how demand is distributed across high-frequency, ultra-high-frequency, super-high-frequency, and extremely-high-frequency categories, as well as across ground, airborne, marine, and space platforms. It also maps application demand across communication, surveillance and reconnaissance, electronic warfare, telemetry, and satellite communications. These segmentation views are used to identify where growth logic is strongest, where program-driven demand is likely to remain concentrated, and where suppliers can position for differentiation through specialized performance attributes.
Just as important, the report keeps the segmentation discussion tied to real operating conditions. In practice, an antenna requirement for a ground-based communication node is not equivalent to one for an airborne platform, and an ultra-high-frequency communications application does not carry the same sourcing constraints as an extremely-high-frequency surveillance requirement. By using segmentation to explain demand logic, the report helps executives evaluate where to concentrate commercial attention, which platform segments may offer the most resilient demand, and how frequency preferences can affect design, testing, and supply commitments.
The competitive section goes beyond identification. It connects supplier profiles to the ways they compete, including design and manufacturing focus, frequency specialization, platform coverage, and the ability to support military and commercial requirements with qualified processes. This is paired with recent developments that show how competition is actually unfolding through contracts, qualifications, facility expansion, and program wins. For procurement and strategy teams, that combination is valuable because it shows both the static shape of the market and the dynamic actions that are reshaping it.
The dynamics section is equally operational. It examines how regulatory reclassification, export-control delays, advanced RF material constraints, and tariff-driven component inflation interact to shape cost, schedule, and scalability. Rather than treating these factors as background noise, the report uses them to explain why some programs move faster than others, why certain suppliers may face tighter delivery conditions, and why sourcing strategy must account for more than unit pricing. This makes the research useful for risk assessment, contract strategy, and internal planning discussions where resilience matters as much as performance.
The report also supports executive use cases that extend beyond market curiosity. For product and program leaders, it helps define where to invest in capability development and where to monitor substitution risk. For supply chain and procurement teams, it provides a basis for evaluating supplier concentration, trusted-source exposure, and the practical implications of component and material constraints. For commercial and business development teams, it offers a structured way to prioritize segments, assess partnership fit, and identify where differentiated value can be defended. For investors and corporate strategy functions, it supplies a reasoned view of growth direction against a backdrop of regulatory and supply-chain uncertainty.
Why This Research Matters for 2026 Decision-Making
For organizations making decisions in 2026, the military antenna market presents a rare combination of opportunity and complexity. Demand is expanding, modernization priorities are intensifying, and antenna capability is increasingly embedded in mission-critical functions. Yet that growth is being filtered through export governance, component cost pressure, material constraints, and competitive dynamics that differ sharply by platform, frequency range, and application. In this setting, strategy depends on more than knowing that the market is growing. It depends on knowing where growth is most defensible, where risk is most likely to materialize, and where competitive advantage can be sustained over the forecast horizon.
The report is designed to answer those questions with precision. It gives decision-makers a coherent view of market direction from 2026 to 2032, a practical reading of competitive structure, and a realistic assessment of the forces that will influence execution. It also deliberately preserves the depth that only the full study can provide. Segment-level revenue detail, application-level breakdowns, platform-level quantification, and company-specific positioning insights are reserved for the complete report so that executives and their teams can evaluate the market with the granularity required for real-world decisions.
In practice, that means the research can support more confident answers to questions that matter in 2026: which frequency and platform categories should command the most commercial attention, how supplier concentration affects sourcing resilience, how regulatory and trade dynamics may alter program timelines, and where recent contract and qualification activity signals durable competitive shifts. It is built to help leaders move from awareness to action, using intelligence that is both current and strategically framed.
Accessing the Full Intelligence
The complete Military Antenna Market report provides the detailed segmentation analysis, competitive intelligence, event context, and forward projections needed for program planning, supplier evaluation, and investment strategy. It is intended for leaders who need more than a high-level summary and who must align organizational decisions with a market that is expanding, differentiating, and becoming more operationally complex. For teams that require the full set of quantified insights, the complete study is available through the PW Consulting market research portal.
If your 2026 agenda involves defense portfolio positioning, antenna capability investment, procurement risk management, or competitive benchmarking, this research offers the structured intelligence needed to move forward with greater clarity. The market’s growth path, competitive shape, and regulatory and supply dynamics make it a sector where disciplined insight pays dividends. The full report is designed to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Military Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


