



PW Consulting: Contact Center Market Reaches $47.18B in 2025 with 11.05% CAGR Thru 2032

The Contact Center Market in 2026: Why Strategic Intelligence Is No Longer Optional
The contact center has evolved from a cost-bearing operational unit into a strategic revenue and retention engine. Over the past five years, that transformation has accelerated, driven by shifting customer expectations, the rapid infusion of artificial intelligence into customer experience workflows, and a market that has consistently outpaced broader enterprise technology growth. As organizations finalize their 2026 investment decisions, the difference between reactive procurement and proactive competitive positioning will come down to one factor: the quality of the intelligence guiding those choices.
Electric Mosquito Repellent Incense Market
This article serves as a strategic preview of PW Consulting’s latest Contact Center Market research. It highlights the structural forces reshaping the industry, the competitive dynamics that will define vendor selection, and the operational variables that will determine whether contact center investments deliver measurable returns. The full report contains the granular segmentation, regional contributions, application-level breakdowns, and company-specific benchmarking data required to translate these macro trends into precise budget allocations and roadmap decisions.
Single Bolt Cable Cleat Market
The Market Trajectory: Sustained Growth Meets Structural Pressure
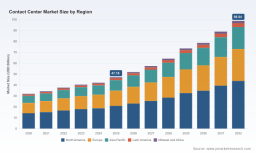
The contact center market has demonstrated consistent expansion across the historical window and is positioned for continued growth through the forecast period. Total market revenue climbed from approximately $32.0 billion at the start of the historical baseline to $47.2 billion by the base year, with the trajectory carrying forward into the early forecast years before reaching nearly $99.0 billion by the end of the projection window. The implied compound annual growth rate across the forecast horizon stands at 11.05%, a pace that signals more than incremental adoption; it reflects a fundamental restructuring of how enterprises deploy, scale, and monetize customer engagement infrastructure.
Planar ITO Target Market
That growth is not uniform across all vectors. The market is being pulled forward by digital channel adoption, AI-infused routing and automation, and the migration of legacy voice-heavy environments toward cloud-native architectures. At the same time, pricing dynamics, labor economics, and regulatory or licensing shifts are introducing new pressure points that require disciplined analysis. Enterprise decision-makers cannot rely on top-line growth figures alone. They need to understand where value is being created, where margins are being compressed, and which vendor capabilities will matter most as the ecosystem matures.
Our research unpacks these layers without oversimplifying them. Rather than presenting a single aggregated number and calling it strategy, the report maps the growth path against the operational realities that will shape budgeting, vendor negotiations, and internal capability building through the forecast period.
What the Research Delivers: An Operational Blueprint, Not Just a Forecast
A market study earns its place in the C-suite only when it connects numbers to decisions. This report is structured to do exactly that. It combines historical grounding, forward-looking projections, and actionable operational context so that strategy, procurement, and customer experience leadership can align around a shared set of assumptions.
The core content is designed around practical use cases:
- Market sizing and trajectory analysis that anchors planning in a defensible historical baseline and extends it through the full forecast window, giving leadership a coherent view of growth momentum rather than isolated snapshots.
- Segment-level intelligence covering regional footprints, engagement types, and application categories so teams can assess where demand is concentrating and how deployment priorities are shifting across customer-facing and internal operations.
- Competitive landscape profiling that examines the strategic positioning, platform capabilities, and market focus of major vendors, enabling more informed shortlisting, negotiation, and partnership decisions.
- Industry context and disruption signals that translate operational pressures, pricing shifts, and technology-driven cost dynamics into implications for staffing models, workflow design, and total cost of ownership.
- Strategic implications and decision frameworks that help organizations translate market intelligence into procurement timing, vendor evaluation criteria, and internal investment priorities.
Throughout the report, the emphasis is on usability. The goal is not to overwhelm readers with data, but to give them a structured way to ask better questions: Which channels are gaining priority in the next planning cycle? Which vendor strengths map to our industry requirements? How should we evaluate AI-enabled automation against labor cost exposure? Where do concentration risks or pricing shifts alter the value equation?
The Competitive Landscape: Ten Vendors, Distinct Plays, Shared Direction
The contact center market is neither a commodity arena nor a monolithic platform race. It is a competitive field where vendors differentiate through architecture, vertical specialization, AI integration depth, and workforce optimization tooling. The research profiles a broad set of leading players, each pursuing a distinct interpretation of what the modern contact center should deliver.
Five9 positions its offering around a cloud-native Intelligent CX platform built for enterprise scale, emphasizing AI-powered agent assist, predictive routing, and omnichannel orchestration. Genesys leans into its Genesys Cloud CX environment, combining journey orchestration, AI chatbots, and workforce engagement tools within a unified omnichannel framework. NICE contributes the CXone platform, with embedded AI focused on workforce optimization, quality management, and customer journey automation. Talkdesk differentiates through its CX Cloud and industry-specific AI experience clouds designed for vertical contact center solutions.
Dialpad takes an AI-first stance, centering on real-time transcriptions, agent flexibility, and outbound calling capabilities. Verint emphasizes AI-powered workforce management and quality management integrated into contact center operations, appealing to organizations that want tighter control over performance and compliance. Nextiva offers all-in-one unified communications and contact center solutions, pairing AI-driven support with transparent per-user pricing. RingCentral brings omnichannel capabilities and AI-powered customer interactions through its RingCentral Contact Center and RingCX offerings. Vonage targets enterprise clients with custom contact center solutions that blend AI agents and omnichannel integration. Zoom rounds out the field with Zoom Contact Center, focused on AI-first total experience capabilities for unified voice and collaboration.
What matters strategically is not simply that these vendors exist, but how their differentiating bets map to organizational needs. A company prioritizing vertical-specific AI workflows will evaluate the market differently from one optimizing for workforce management granularity or omnichannel journey orchestration. The report examines these positioning strategies in detail, giving procurement and IT leaders a sharper lens for vendor evaluation rather than a generic leaderboard.
The competitive context is also being reshaped by external capital and product momentum. Recent funding activity underscores how aggressively investors are backing AI-native support automation and messaging-centric customer support platforms. In August 2025, Capacity announced $92 million in new investments, bringing total funding to more than $155 million for its AI-powered support automation platform. Around the same time, Pylon secured $31 million in Series B funding for a B2B customer support platform built specifically for business messaging environments. These moves signal a market that continues to attract capital where automation, messaging, and AI-driven support intersect, reinforcing the importance of evaluating not just established incumbents but also fast-moving entrants that may alter service models and pricing expectations.
Market Dynamics at a Glance: Cost, Pricing, Licensing, and the AI Leverage Point
Behind the headline growth figures lies a set of operational dynamics that will directly affect 2026 planning. The most consequential is the economic leverage created by AI-driven automation. Conversational agents and AI-supported workflows are reducing contact center agent labor costs at scale, with sector analysis pointing to a global reduction potential reaching up to $80 billion. That figure is not abstract. It reflects a structural shift in how organizations think about Tier 1 handling, escalation design, and agent utilization. When a single inbound call to a live agent can cost between $6 and $15 while AI can manage comparable Tier 1 queries for roughly $0.30 to $0.50 per interaction, the value case for intelligent automation becomes a central component of contact center strategy rather than a peripheral efficiency project.
At the same time, cost advantages are being offset in part by pricing pressure and licensing shifts across enterprise software portfolios. Vendors across the contact center space have implemented aggressive price increases across portfolios effective in mid-2026. Microsoft’s ecosystem changes introduce additional complexity: Microsoft 365 frontline worker licenses tied to contact center use are rising between 25% and 33% starting in July 2026, while Microsoft business tiers used in contact center workflows are increasing between 12% and 17% over the same window. These changes matter because many organizations run hybrid stacks in which contact center functionality intersects with collaboration, identity, desktop, and productivity tools. Licensing exposure is no longer a back-office detail; it is a variable that can materially alter total cost of ownership.
The strategic implication is clear. Growth in the market does not guarantee easier economics for every buyer. Organizations that evaluate contact center investment through a single lens—platform features or headline price—risk underestimating the combined impact of automation savings, vendor pricing, licensing escalation, and workflow redesign. The research integrates these dynamics so leaders can model scenarios with more realism and avoid decisions built on incomplete cost assumptions.
Why This Research Matters for 2026 Decision-Making
2026 is shaping up to be a year in which contact center strategy is tested on multiple fronts at once. Customer experience expectations continue to rise, AI capabilities are maturing faster than many internal operating models can absorb, and vendor pricing and licensing structures are becoming more complex. In that environment, decision quality depends on clarity. Leaders need to know not just that the market is expanding, but how growth is distributed across channels, applications, and regions; not just which vendors are prominent, but which capabilities align with specific operational priorities; and not just that AI is reshaping labor economics, but how automation savings interact with licensing and vendor pricing.
The full report is designed to answer those questions with enough specificity to support budgeting, sourcing, and roadmap planning. It builds on a historical perspective from 2020 through the base year, extends into the forecast window through the end of the decade and beyond, and frames the discussion around the segmentation splits, competitive profiles, and industry context that matter most to enterprise buyers. Where broad market numbers establish trust, the deeper segmentation and company-level detail provide the leverage needed to make precise commitments.
This preview is intentionally high-level. It establishes the strategic stakes and the analytical rigor behind the study, but it does not reveal the full segmentation values, regional contributions, application-level breakdowns, or detailed company benchmarking that constitute the core intelligence of the report. Those elements are where the difference between a generic market narrative and an actionable decision framework is made. They are also where procurement teams, customer experience leaders, and finance stakeholders will find the comparisons and scenario inputs needed to justify investment choices with confidence.
How to Use This Intelligence
The most valuable contact center research is not the one that simply identifies trends. It is the one that helps teams convert trends into decisions. PW Consulting’s report is structured to support that conversion across several practical pathways:
- Strategic planning: Align long-range customer engagement investment with market growth direction and segmentation signals rather than legacy assumptions.
- Vendor evaluation: Compare platform positioning, AI integration depth, and workforce optimization strengths against actual operational requirements instead of generic feature lists.
- Cost modeling: Incorporate automation economics, vendor pricing trajectories, and licensing escalation into total cost of ownership analysis for more credible financial planning.
- Operating model design: Use channel and application context to inform staffing, workflow, escalation, and automation balance across inbound and outbound interactions.
- Risk management: Monitor market concentration, pricing momentum, and fast-moving entrants so that sourcing decisions reflect not only current capabilities but also future ecosystem shifts.
Each of these pathways depends on access to the underlying segmentation and benchmarking detail that the report provides. The macro trajectory gives the market its shape, but the segmentation and company-level analysis give leaders the resolution they need to act.
A Preview With Purpose
The contact center market in 2026 is defined by momentum, complexity, and opportunity. Revenue expansion measured in the tens of billions, an 11.05% forecast compound annual growth rate, and a competitive field of sophisticated platform vendors all point to a sector in transition. Yet the real strategic challenge is not recognizing that the market is growing. It is understanding how that growth breaks down across regions, engagement types, applications, and vendor plays, and how cost dynamics—from labor savings to licensing increases—alter the value equation for each organization.
This article has outlined the structural forces, competitive context, industry dynamics, and decision implications that make the Contact Center Market research relevant to 2026 planning. What it has not done is expose the full segmentation data, company-specific benchmarks, and granular comparisons that sit at the heart of the report. That detail is reserved for the complete study, where it can be used with the precision it requires.
For executives, procurement leaders, and customer experience strategists preparing for the year ahead, the opportunity is to move from high-level awareness to grounded intelligence. The full report delivers that next layer: the segmented view, the competitive comparisons, and the operational context needed to make contact center investment a source of competitive advantage rather than a reactive cost line.
For detailed analysis of this topic, please visit the official page: Contact Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


