



PW Consulting: Sheet Molding Compound Market Projected to Reach $2.3B by 2032, Growing at 4.22% CAGR

Strategic Horizons in the Sheet Molding Compound Market: Navigating Growth and Complexity Through 2032
The structural landscape of the Sheet Molding Compound (SMC) market is undergoing a quiet but significant transformation. What was once viewed primarily as a cost-effective alternative for complex geometries is now emerging as a critical enabler for weight reduction, design flexibility, and chemical resistance across multiple industrial verticals. For supply chain leaders, procurement strategists, and corporate development teams, this shift carries profound implications for 2026 and beyond. The market is not merely expanding; it is rebalancing around new formulation technologies, capacity realignments, and application-driven demand that reward early visibility and strategic positioning.
Worldwide Gas Powered Cold Water Pressure Washer Market
This article introduces our latest comprehensive market research on the SMC sector, designed to equip decision-makers with the analytical depth required to navigate the forecast period from 2026 through 2032. Rather than offering surface-level aggregates, the study dissects the operational, competitive, and macroeconomic forces shaping the industry, providing a roadmap for capacity planning, product portfolio optimization, and partnership development. The following overview previews the strategic architecture of the research, demonstrating how granular insights can be converted into actionable intelligence.
Frameless Resolvers Market
Market Size Evolution and the Trajectory Anchored for 2026
The SMC market has demonstrated resilience through periods of raw material volatility, shifting end-use demand, and incremental capacity adjustments. Drawing on historical data spanning 2020 through 2025, the industry has experienced a series of nuanced fluctuations that reflect both cyclical pressures and structural shifts in downstream consumption. The base year of 2025 establishes a critical reference point, capturing the market's positioning as it enters a new phase of forecast-driven growth.
Home Theater Recliner Market
Looking forward, the projected trajectory through 2032 reveals a steady, compounding expansion that underscores the material's enduring relevance. The compound annual growth rate underscores a market that is not experiencing explosive disruption but rather a disciplined, application-led ascent. This steady climb is supported by ongoing substitutions in sectors where metal and unreinforced thermoplastics face cost, performance, or weight penalties. The forecast window captures the cumulative effect of incremental capacity additions, formulation refinements, and the gradual penetration of SMC into higher-specification applications that were previously considered marginal.
It is important to recognize that absolute market size alone does not tell the story that matters to 2026 decision-makers. The real value lies in understanding how growth is distributed across formulation types, downstream sectors, and geographic corridors, and how those distributions interact with supply constraints, pricing dynamics, and competitive capacity shifts. Our research isolates these layers, allowing executives to distinguish between headline growth and the underlying drivers that will dictate margin stability, sourcing strategy, and regional investment priorities.
Segmentation: Where Growth Actually Originates
A market of this scale only becomes actionable when its internal architecture is understood. The SMC industry is not a monolith; it is a constellation of formulation families, application verticals, and regional supply ecosystems that each follow distinct logic. The research breaks down the market across these dimensions, mapping how different product categories and end-use sectors contribute to overall momentum and where performance diverges from broad trends.
Formulation Families and Their Differentiated Roles
The composition of SMC demand is shaped by the performance requirements of downstream applications and the cost-performance tradeoffs accepted by manufacturers. Unsaturated polyester formulations continue to anchor a substantial portion of the market, reflecting their versatility, established processing infrastructure, and favorable economics for high-volume structural and cosmetic parts. Vinyl ester-based variants occupy a distinct niche, particularly where enhanced chemical resistance or improved thermal stability is required, making them relevant to demanding industrial and electrical contexts. Epoxy and phenolic systems, while representing smaller shares of the broader mix, are gaining attention in specialized applications where mechanical stiffness, flame performance, or adhesion characteristics justify the premium.
Understanding these formulation dynamics is essential for companies evaluating product roadmap decisions. A supplier expanding its unsaturated polyester capacity, for example, is making a fundamentally different strategic bet than a producer investing in flame-retardant or epoxy-based grades. The research examines how these formulation categories evolve in response to raw material availability, processing improvements, and specification changes in end markets, enabling readers to identify which segments offer the strongest alignment with their own technical capabilities and customer portfolios.
Application Verticals and Demand Velocity
The dispersion of SMC consumption across applications reveals where demand is most resilient and where it is most sensitive to macro conditions. Automotive remains a central pillar of the market, driven by ongoing lightweighting initiatives, the need for corrosion-resistant components, and the growing use of composite materials in both structural and exterior applications. Within this vertical, the rise of electric vehicle architectures has introduced new considerations around panel design, underbody protection, and enclosure materials, prompting both material suppliers and molders to refine formulations for specific performance targets.
Electrical and electronics applications represent another significant channel, where SMC's electrical insulation properties, dimensional stability, and ability to meet flame and tracking requirements support its use in enclosures, components, and infrastructure-adjacent hardware. Building and construction demand is anchored by the material's durability, weatherability, and suitability for molded panels, profiles, and specialty components that must balance aesthetics with long-term performance. Beyond these core verticals, a diverse set of industrial and specialty applications contributes additional demand, often driven by custom engineering requirements and lower-volume, higher-value production runs.
The research profiles these application streams with attention to demand drivers, specification trends, and the interaction between material performance and total cost of ownership. This perspective helps readers assess which verticals offer the most attractive growth profiles for their capabilities, and where competitive intensity or specification barriers may limit rapid share gains.
Regional Supply and Demand Architectures
Geography shapes the SMC market in ways that go beyond simple volume distribution. Regional demand patterns reflect local industrial bases, automotive production footprints, construction activity levels, and the maturity of composite processing ecosystems. At the same time, regional supply dynamics are influenced by the location of resin manufacturers, compounders, and molders, as well as by logistics costs and local regulatory environments.
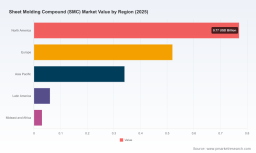
North American demand has been supported by a combination of automotive production, industrial manufacturing, and building product applications, alongside a relatively mature compounding and molding infrastructure. European markets reflect strong demand from automotive suppliers, electrical component manufacturers, and construction-related applications, with an emphasis on engineered formulations and compliance-driven specifications. Asia Pacific represents an important growth axis, shaped by expanding manufacturing capacity, vehicle production, and infrastructure development, though the region's market structure is more fragmented and increasingly influenced by localized formulation strategies. Latin America and the Middle East and Africa contribute smaller but strategically relevant volumes, often tied to specific industrial projects, export-driven manufacturing, or niche applications where SMC's performance profile offers a clear advantage.
Rather than presenting static regional snapshots, the study examines how these geographies interact with formulation availability, lead-time considerations, and competitive capacity. For companies evaluating export opportunities, sourcing diversification, or local production investments, this regional layer is essential for distinguishing between apparent demand and commercially viable demand.
Competitive Landscape: Capacity, Formulation, and Strategic Positioning
The SMC market is characterized by a mix of compounders, resin suppliers, and engineered materials producers, with a notable concentration among the largest participants. The research profiles the companies that shape market dynamics through capacity decisions, formulation innovation, vertical integration, and customer-facing technical support. Understanding this landscape is critical for assessing supplier reliability, partnership opportunities, and the risk of capacity constraints in key segments.
Key Companies and Their Strategic Footprints
IDI Composite International, based in Noblesville, Indiana, operates as a custom-formulated SMC and BMC manufacturer with dedicated production lines and tailored solutions spanning automotive, industrial, and electrical applications. The company's recent expansion underscores the importance of flexible capacity in serving both high-volume and lower-volume runs. In January 2026, IDI Composite International launched a third SMC production line at its new Noblesville facility, reducing lead times to approximately three to four weeks and enabling smaller batch sizes that broaden its appeal for custom and specialized programs.
Core Molding Technologies, headquartered in Columbus, Ohio, is an engineered materials company specializing in compression molding of SMC for automotive, building products, and aerospace applications, relying on proprietary formulations to differentiate its offerings. By March 2026, the company was installing two 4,500-ton presses in Matamoros, Mexico, to expand its SMC production footprint. This capacity expansion coincided with new business wins, including proprietary SMC formulations for building products, signaling the value of combining equipment scale with formulation IP.
In Europe, Menzolit Kunststoffwerk GmbH has established itself as a specialist in high-performance SMC for automotive, electrical, and demanding structural applications, emphasizing part quality and formulation precision. Polynt S.p.A., based in Italy, produces SMC and flame-retardant SMC grades that serve automotive, electrical, and power applications, reflecting the importance of regulatory and performance-driven grades in certain downstream markets.
Japan's Teijin Limited manufactures advanced SMC and carbon-fiber-reinforced SMC for automotive and EV exterior panels, illustrating how reinforcement strategy and panel-specific engineering can create differentiated positions in the mobility sector. LyondellBasell Industries Ltd., operating from the Netherlands, supplies unsaturated polyester and vinyl ester systems for SMC compounding, representing the upstream resin supply layer that directly affects formulation economics and availability. Toray Industries, Inc., also based in Tokyo, provides advanced fibers and resins used in SMC formulations for high-performance composites, reinforcing the link between fiber technology and SMC performance ceilings.
In the United States, AOC Resins formulates resins and additives for SMC production, contributing to the broader ecosystem of compounding inputs. Premix Inc. operates as an SMC compounder offering engineered materials for automotive and industrial use, while Molding Products LLC, based in South Bend, Indiana, serves as a custom SMC and BMC formulator and producer with technical support spanning R&D to production. Together, these companies illustrate a competitive field in which formulation capability, capacity responsiveness, and technical service differentiate participants more than scale alone.
Concentration, Capacity, and the Nature of Competition
Market concentration among the leading participants creates a landscape where strategic moves by a small number of players can influence pricing, lead times, and the availability of specialized grades. At the same time, the presence of regional compounders and custom formulators ensures that niche applications and lower-volume programs can still access tailored solutions. The research evaluates how this concentration interacts with capacity expansion patterns, acquisition activity, and formulation differentiation, providing context for assessing supplier risk and partnership strategy.
For buyers, the key question is not simply which companies are largest, but which are expanding capacity in the right geographies, investing in formulations aligned with upcoming application requirements, and maintaining the technical support infrastructure needed to move programs from development to production. For competitors, the strategic challenge is to identify where scale, where specialization, and where regional presence create defensible positions in a market that rewards both consistency and customization.
Market Dynamics and Operational Realities
Beyond size, segmentation, and competition, the SMC market is shaped by operational dynamics that directly influence profitability, planning certainty, and sourcing decisions. Raw material price volatility remains a significant challenge for manufacturers, particularly in unsaturated polyester resins and fiberglass. Fluctuations driven by oil prices and supply imbalances can compress margins, disrupt quoting accuracy, and complicate long-term planning. The research addresses these dynamics not as abstract risks but as practical factors that shape formulation choices, inventory strategies, and the timing of capacity commitments.
Processing infrastructure also plays a decisive role. The number, tonnage, and flexibility of compression molding presses, together with the availability of skilled technical support, determine how quickly programs can be scaled and how effectively custom formulations can be commercialized. Companies that combine formulation expertise with responsive production capacity are better positioned to win lower-volume, higher-specification work, while those reliant on rigid high-volume lines may face challenges when demand patterns shift toward more customized or region-specific programs.
Regulatory and specification requirements further influence market behavior. Flame performance, electrical properties, weathering resistance, and structural durability are increasingly important in automotive, electrical, and building applications. These requirements create both barriers and opportunities: they raise the technical bar for entry into certain segments, but they also reward suppliers that can demonstrate consistent performance and provide validated grades aligned with end-use standards.
Our study integrates these dynamics into a coherent framework, showing how raw material exposure, processing capacity, specification demands, and regional logistics combine to shape commercial outcomes. This integrated view is essential for companies that need to evaluate not only where the market is growing, but where growth can be captured profitably and reliably.
What the Research Delivers for 2026 Decision-Making
The SMC Market research is structured to move beyond descriptive trends and provide the operational intelligence needed for concrete decisions in 2026 and the forecast period that follows. It is designed for executives, planners, and technical leaders who must reconcile market opportunity with supply reality, specification requirements, and competitive constraints.
The study offers a detailed segmentation architecture that maps formulation types, application verticals, and regional demand patterns, allowing readers to identify which combinations of material, application, and geography offer the strongest strategic alignment. This is not a superficial split of broad categories; it is a working framework for evaluating product portfolios, sourcing strategies, and investment priorities.
The competitive analysis profiles the companies that matter most to market dynamics, examining their capacity footprints, formulation strengths, geographic presence, and recent operational moves. By linking company actions to market implications, the research helps readers assess supplier stability, partnership potential, and the likely direction of capacity and price trends in key segments.
The report also incorporates market dynamics that influence commercial outcomes, including raw material volatility, processing infrastructure considerations, specification drivers, and the interaction between regional demand and local supply. This contextual layer is essential for translating growth forecasts into practical planning, whether the objective is to secure reliable supply, enter a new application, expand into a new region, or evaluate whether a competitor's capacity move affects your own positioning.
For corporate strategy teams, the research provides a basis for scenario planning, helping to frame decisions about capacity investment, product development, and market entry in light of the forecast period's growth curve and the structural forces shaping demand. For procurement and supply chain leaders, it offers context on where concentration, formulation specificity, and raw material exposure may affect lead times, pricing stability, and supplier diversification options. For technical and product leaders, it connects downstream application requirements with formulation characteristics, supporting more informed decisions about material selection and program feasibility.
Why 2026 Is the Pivot Year for SMC Strategy
The SMC market in 2026 sits at a point where multiple forces converge. Capacity expansions are coming online, formulation differentiation is intensifying, and end-use sectors are refining their material requirements in response to product architecture changes, regulatory expectations, and total-cost considerations. At the same time, raw material volatility and regional supply constraints continue to test the resilience of supply chains and the accuracy of long-range planning.
In this environment, decision-makers benefit most from intelligence that connects growth potential with operational reality. Headline market size and CAGR provide necessary orientation, but they do not reveal which formulations are gaining specification traction, which applications are driving durable demand, which regions offer the most commercially viable opportunities, or which competitors are reshaping the supply landscape through capacity and formulation investment. Those are the questions that determine whether a company can act with confidence in 2026 and sustain its position through the rest of the forecast window.
The full report provides the detail, segmentation depth, competitive profiles, and dynamic analysis required to answer those questions. It is built for readers who need to move from general market awareness to specific, defensible decisions about sourcing, product strategy, regional focus, and partnership development.
For leaders who are evaluating SMC as a strategic material, assessing the competitive field, or planning capacity and formulation investments, this research offers the analytical foundation to act with precision. The market is expanding in a disciplined, application-led manner, and the companies that succeed in 2026 will be those that understand where growth originates, how it flows through the value chain, and which operational choices convert opportunity into durable advantage.
To access the complete segmentation architecture, competitive profiles, regional demand analysis, and dynamic assessment that underpin the forecast, we invite you to explore the full report. The detailed intelligence within is designed to support the decisions that matter most in the months and years ahead.
For detailed analysis of this topic, please visit the official page: Sheet Molding Compound (SMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


