



Wheelbarrows Market to Hit $880M by 2032, Growing at 4.3% CAGR: PW Consulting

Strategic Horizon 2026: Unlocking Value in the Global Wheelbarrows Market
The industrial tools sector is rarely characterized by glamour, yet few categories embody the fundamentals of global economic activity quite like the wheelbarrow. From the sprawling infrastructure projects reshaping emerging economies to the quiet corners of residential renovation, this humble equipment category serves as a critical linchpin in material handling logistics. As we move through 2026, the wheelbarrows market presents a complex landscape of steady growth, material innovation, and shifting regulatory pressures. Understanding these dynamics is not merely an academic exercise; it is a strategic imperative for manufacturers, suppliers, and investors aiming to capitalize on the sustained demand projected over the coming years.
Database Management Platform Market
Our latest comprehensive market research report offers an unprecedented look into the mechanisms driving this sector. By analyzing historical data from 2020 through 2025 and projecting forward to 2032, we have identified the key vectors of growth and risk. This article serves as an executive preview of those findings, highlighting the strategic value embedded in the data without divulging the granular intelligence reserved for our full subscribers. In an environment where supply chain volatility and raw material costs can erase margins overnight, access to precise market forecasting is the difference between reactive scrambling and proactive planning.
Pen Making Market
Market Trajectory and Macro Economic Insights
The financial narrative of the wheelbarrows market over the past half-decade tells a story of resilience and incremental expansion. Starting from a consolidated base in 2020, the market has navigated post-pandemic recovery phases, supply chain disruptions, and shifting labor dynamics to reach a stabilized revenue base in 2025. Our analysis indicates that the compound annual growth rate (CAGR) for the forecast period extending to 2032 is positioned at 4.3 percent. While this figure may appear moderate compared to high-growth technology sectors, it represents a robust, underlying demand curve driven by essential industries rather than speculative hype.
Engineering Plastics Grade Nylon 66 Resin Market
The revenue progression from 2020 to the forecast horizon suggests a market that is maturing but not stagnant. Key inflection points in the forecast period, particularly around the late 2020s, highlight where demand spikes are anticipated based on current infrastructure commitments and construction cycles. For decision-makers, this trajectory offers a blueprint for capacity planning and inventory management. Investors looking at long-term asset allocation in the industrial manufacturing space will find that the stability of this growth curve provides a hedge against more volatile market segments. However, the aggregate numbers only tell part of the story. The real strategy lies in understanding where this value is generated and how the composition of that value is shifting over time.
Notably, the market size projections indicate periods of acceleration followed by consolidation. This pattern reflects the broader economic cycles affecting construction and agriculture, the two primary pillars supporting demand. For a business leader, recognizing these cycles allows for the timing of product launches and the negotiation of long-term supply contracts. Our report details the specific revenue milestones expected across the forecast horizon, providing the granularity needed to align operational budgets with market realities. The goal is to move beyond simple top-line growth expectations and understand the volume and value dynamics that underpin them.
Competitive Landscape and Strategic Positioning
The competitive environment in the wheelbarrows market is defined by a mix of established multinational manufacturers and specialized regional players. Our analysis of market concentration reveals a fragmented landscape where the top three players hold a combined share of approximately 32.5 percent, while the top five control around 47.8 percent. This concentration level suggests that while there are dominant incumbents, there remains significant room for niche players to differentiate through specialization, material innovation, or regional service networks.
Key companies such as Tramontina, Walsall Wheelbarrow Company, Ames True Temper, and Gorilla Carts illustrate the diverse approaches to capturing market share. Tramontina, based in Brazil, exemplifies a strategy focused on versatility and sustainability. Their recent launch of the 200-liter Extraforte da Agricultura model, featuring dual solid recycled rubber tires, signals a strong alignment with agricultural endurance needs and circular economy principles. This move is not just about product utility; it is a statement on material sourcing and brand responsibility that resonates with modern procurement standards in the agriculture sector.
In contrast, manufacturers like Walsall Wheelbarrow Company in the UK are doubling down on professional certification and regional prestige. Their recent membership in the EURO CRAFT European buying group and recognition as Family Business of the Year highlight a strategy built on collaboration, quality assurance, and local economic integration. Similarly, Ames True Temper and Brentwood Industries in the USA continue to dominate the construction end of the spectrum with heavy-duty steel trays and wooden handles designed for the rigors of professional building sites. These companies rely on brand legacy and proven durability to maintain loyalty among contractors who cannot afford equipment failure on the job.
Emerging technologies are also reshaping the competitive field. Husqvarna AB from Sweden is pioneering the electrification of material handling. By developing battery-powered wheelbarrows with smart sensors and long runtime, they are addressing labor shortages and ergonomic concerns in professional landscaping and construction. This represents a potential disruptive vector in the market. Companies that rely solely on traditional steel and plastic mechanisms may find themselves overtaken by electrified alternatives if labor costs continue to rise or if regulations push for reduced manual strain in the workplace. Our full report provides a detailed competitive analysis matrix, evaluating each key company's product portfolio, geographic reach, and recent strategic developments to help you benchmark your position against the market leaders.
Market Dynamics: Materials, Regulations, and Demand Drivers
The operational environment for wheelbarrow manufacturers is currently shaped by a triad of forces: raw material volatility, regulatory intervention, and shifting consumer habits. Steel remains the primary raw material for the majority of heavy-duty wheelbarrows, and its price stability is directly correlated with production margins. Post-pandemic recovery in the US steel industry has led to fluctuating prices, creating a challenging environment for cost management. Manufacturers must navigate these fluctuations without alienating price-sensitive consumers or eroding their own profitability. The industry context data we have gathered highlights how sensitive the market is to these raw material shifts, and our report offers strategies for hedging against steel price volatility through design optimization or material substitution.
Regulatory factors are also coming into sharper focus. In April 2025, the UK Steel Industry (Special Measures) Bill addressed primary steelmaking challenges with direct government intervention on raw material purchases. While this legislation is specific to the UK, it sets a precedent for how governments might intervene in industrial supply chains to ensure security of supply. For global manufacturers, such regulatory moves can alter the competitive balance between regions with subsidized steel production and those relying on open markets. Understanding the regulatory landscape in key export and import territories is crucial for compliance and for anticipating shifts in material availability.
Demand-side dynamics are equally transformative. Infrastructure and construction development remain the primary drivers of demand for material handling equipment. As governments worldwide continue to invest in public works, the need for reliable wheelbarrows on job sites remains constant. However, beyond the professional sector, there is a noticeable shift in consumer behavior. Rising DIY and home improvement trends are increasing consumer preference for durable and lightweight options. This segment often prioritizes ease of use and maneuverability over raw load capacity, creating a distinct product requirement profile compared to the construction segment. Manufacturers that can effectively bridge the gap between heavy-duty durability and consumer-friendly ergonomics stand to capture value in both the professional and retail channels.
Sustainability is no longer a peripheral concern but a core component of product value. The incorporation of recycled industrial rubber from tires for durability, as seen in recent product launches, reduces environmental impact and appeals to eco-conscious procurement officers. This trend intersects with the broader push for green construction and sustainable agriculture. Our research delves deep into how sustainability metrics are becoming a differentiator in tenders and large-scale contracts, influencing which suppliers win business in the public sector.
Segmentation Strategies and Growth Opportunities
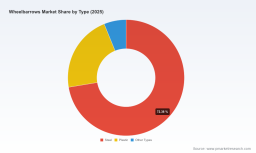
While the aggregate market data provides the macroeconomic view, the true strategic opportunities lie in the segmentation of the market. The division between material types, applications, and geographies creates distinct battlegrounds for competition. Steel continues to hold a dominant position in terms of revenue share, reflecting its preference in heavy-duty construction and industrial applications. However, plastic and other composite types offer specific advantages in terms of weight reduction and corrosion resistance, making them vital for specific agricultural or chemical handling use cases. The balance between these material types is shifting as manufacturing technologies evolve and as customers seek lighter loads for manual handling.
Application-wise, construction remains the largest driver of value, but agriculture represents a significant and resilient revenue stream. The agricultural sector requires equipment that can withstand harsh environments, mud, and heavy loads of produce or feed. The recent product innovations in this space, such as specialized agricultural models with recycled rubber tires, indicate that stakeholders in this segment are actively innovating to meet these specific needs. The third segment, comprising various other applications, often includes landscaping, gardening, and utility tasks. Growth in this area is closely tied to consumer discretionary spending and urban greening projects.
Regionally, the market is distributed across North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique challenges and opportunities. Developed markets in North America and Europe are characterized by high standards for safety and durability, alongside a mature competitive landscape. In contrast, Asia Pacific and emerging regions offer volume growth potential driven by infrastructure expansion and urbanization. However, these markets may also present challenges regarding price sensitivity and distribution logistics. Our report breaks down these regional dynamics without exposing the specific revenue splits, allowing clients to assess where their current footprint aligns with the highest growth potential before making capital allocation decisions.
For businesses looking to expand, the strategic question is not just where the market is growing, but where their specific value proposition fits best. A manufacturer specializing in heavy steel construction tools may find limited synergy in the consumer DIY segment, whereas a company with flexible molding capabilities might find significant growth in the lightweight plastic segment for landscaping. The interplay between type, application, and region creates a matrix of opportunities that requires careful analysis to navigate effectively. Our full segmentation analysis provides the detailed breakdowns necessary to identify these high-yield pockets of demand.
Conclusion and Call to Action
The wheelbarrows market in 2026 is at a crossroads of tradition and innovation. While the fundamental need for manual material handling equipment remains unchanged, the methods of production, the materials used, and the regulatory environment are evolving rapidly. For industry stakeholders, the margin for error is shrinking. The ability to anticipate steel price fluctuations, adapt to new sustainability requirements, and cater to both professional and DIY demand streams will define the winners of the next decade. The projected CAGR of 4.3 percent offers a reason for optimism, but realizing that growth requires more than passive observation.
Our comprehensive market research report goes beyond the high-level trends discussed here. It contains the proprietary data, detailed segmentation splits, and deep-dive competitor profiles necessary to build a robust strategic plan. We invite industry leaders, investors, and strategists to access the full report to gain the complete intelligence picture. By leveraging these insights, your organization can make informed decisions on product development, market entry, and supply chain optimization, ensuring that you are not just participating in the market but leading within it. The tools are simple, but the strategy required to master their market is complex. Let us help you navigate that complexity.
For detailed analysis of this topic, please visit the official page: Wheelbarrows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


