



PW Consulting: Water Analysis Market Hits $372.81M in 2025, Projected to Reach $537.96M by 2032

Strategic Intelligence for a Water-Stressed World: Why the 2026 Water Analysis Instrumentation Market Demands Executive Attention
The global imperative for precise, reliable, and increasingly automated water quality assessment has moved from a technical requirement to a boardroom priority. As municipalities grapple with aging infrastructure, industrial operators face tighter effluent compliance, and environmental agencies mandate real-time ecological monitoring, the instrumentation ecosystem that measures, analyzes, and validates water quality is undergoing a structural transformation. The period spanning 2026 through 2032 will not merely represent incremental growth; it will reward organizations that understand where capital is flowing, which analytical modalities are gaining regulatory tailwinds, and how competitive consolidation is reshaping procurement dynamics. Our latest market research on the Water Analysis Instrumentation Market provides the strategic scaffolding necessary to navigate this shift with confidence.
Zirconia Ceramic Femoral Head Market
The Macro Trajectory: Reading the Numbers as Strategic Signals
The baseline valuation for the global market stood at approximately 372.81 million USD in 2025, reflecting a compounding growth curve that has been consistently upward since 2020. When we trace the historical arc from 288.51 million USD in 2020 through successive annual expansions, a clear inflection pattern emerges: demand acceleration is no longer episodic but structurally embedded. The research projects that this momentum will carry the market to roughly 405.13 million USD in 2026, with sustained compounding that extends the revenue trajectory toward the 537.96 million USD range by 2032. These figures are underpinned by a forecast-period CAGR that anchors the entire analytical framework at 5.4 percent.
Universal CAR-T Cell Therapy Market
For executive decision-makers, this trajectory communicates several non-obvious signals. First, the growth is broad-based rather than dependent on a single geographic or application surge, which reduces portfolio concentration risk but simultaneously raises the bar for differentiation. Second, the steady compounding indicates that capital expenditure cycles in water analysis are transitioning from reactive replacement to proactive capability upgrading. Third, the extended forecast window provides a multi-year planning horizon that allows procurement, R&D, and merger-and-acquisition teams to align roadmaps with verifiable demand progression rather than quarterly speculation.
Aerospace and Defense Fans Market
Competitive Architecture: A Concentrated Landscape With Distinctive Strategic Niches
The market is not a undifferentiated commodity pool. Our concentration analysis reveals a top-three revenue share of approximately 43.0 percent and a top-five share of roughly 54.0 percent, indicating a moderately concentrated environment where scale, brand trust, and integrated solution portfolios matter. Yet concentration alone does not tell the competitive story. The real strategic insight lies in how leading players have carved adjacent capability centers that intersect with the core instrumentation market in highly specific ways.
Hach Company has established a comprehensive line of water quality testing instruments, analytical systems, and chemistries designed to cover laboratory, process, and field applications across municipal, industrial, and environmental water analysis. Their positioning illustrates a full-spectrum strategy where hardware, reagents, and method validation converge into a single procurement relationship. YSI Incorporated has focused its offering on water quality sampling and monitoring meters, sensors, and instruments tailored for environmental monitoring, wastewater, and drinking water treatment, with a recent January 2025 product launch introducing the HydroRIG IoT gateway device for enhanced environmental water quality monitoring. That move signals a deliberate pivot toward connected, field-deployed telemetry rather than standalone measurement alone.
Thermo Fisher Scientific brings ion chromatography systems, discrete analyzers, pH/conductivity meters, and other analytical instruments to drinking water, surface water, groundwater, and wastewater testing, leveraging laboratory-grade precision that resonates with regulated analytical workflows. Xylem Inc. complements this ecosystem by providing analytical instrumentation for water quality, level, and flow measurement across clean water, wastewater, and outdoor environments, including the YSI brand, which embeds a recognized monitoring heritage within a broader water technology suite. Agilent Technologies addresses regulated water testing and pollutant analysis through ICP-MS, LC-MS, and sample preparation systems, positioning at the intersection of trace contaminant detection and compliance-driven method specificity.
HORIBA Instruments Incorporated contributes benchtop and online water quality meters, UV-VIS spectrometers, and sensors for environmental and industrial water monitoring, bridging laboratory reference methods with process-line continuity. Myron L Company focuses on portable conductivity and pH meters for industrial, municipal, and pool/spa water quality testing, emphasizing field-deployable convenience and rapid decision support. CHEMetrics, LLC supplies self-filling ampoules and V-2000 spectrophotometer systems for accurate water testing of multiple parameters, offering a low-barrier, method-standardized approach that appeals to distributed testing networks. Martek Instruments, Inc. rounds out the landscape with ultrapure water quality analyzers and sensors designed for power generation, pharmaceutical, and semiconductor industries, highlighting the critical role of ultra-low-contaminant measurement in high-value manufacturing environments.
Strategically, this company set reveals a market where vertical integration, method ecosystem ownership, and connectivity roadmaps differentiate leaders from followers. Procurement teams evaluating vendors must look beyond sticker pricing to assess whether a supplier can anchor an entire analytical workflow, support digital telemetry, and maintain method alignment with evolving regulatory expectations.
Segmentation As a Strategic Lens, Not a Static Snapshot
A rigorous competitive and procurement strategy requires a nuanced understanding of how the market divides across operating contexts. Our research examines the instrumentation landscape through multiple segmentation dimensions, including geographic deployment patterns, instrument architecture categories, and end-use application environments. These dimensions interact in ways that single-axis views often obscure.
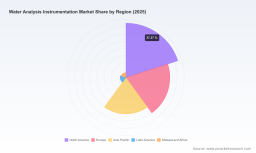
The regional architecture shows how demand is distributed across diverse regulatory, climatic, and infrastructural conditions. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa each present distinct procurement cycles, compliance regimes, and field-deployment challenges. Understanding where capacity is being installed, maintained, and upgraded provides critical input for manufacturing footprint planning, distributor network design, and after-sales service readiness. Industrial and municipal application environments exhibit different instrumentation priorities: one set emphasizes process control, contaminant tracing, and continuous compliance verification, while the other centers on public health protection, distribution-system integrity, and regulatory reporting cadence. Recognizing these operational divergences prevents misalignment between instrument specifications and real-world decision thresholds.
On the instrument-side dimension, the market splits between laboratory-based analytical setups and online, in-situ measurement architectures. Laboratory-based systems anchor method validation, reference-grade accuracy, and complex multi-parameter workflows that support compliance documentation and forensic water quality assessment. Online instruments provide continuous monitoring, early-warning signaling, and process-loop integration that reduce sampling latency and support automated response protocols. The strategic tension between these two modalities is not zero-sum; rather, it reflects an organizational decision about how much analytical authority is retained in centralized laboratories versus embedded within distributed field and process environments. The balance a company strikes directly shapes capital allocation, data architecture, and workforce skill requirements.
Regulatory Pressure as a Demand Catalyst, Not a Compliance Burden
Regulatory evolution is actively reshaping measurement priorities across jurisdictions. In early 2025, the recast EU Drinking Water Directive began requiring monitoring of PFAS Total and Sum of PFAS parameters in drinking water using harmonized methods of analysis. Alongside this mandate, the revised directive updates parametric values and introduces new testing requirements for parameters including bisphenol A, chlorite, and haloacetic acids. These changes do more than add analytes to a checklist; they elevate the performance expectations for detection limits, method robustness, cross-laboratory comparability, and data traceability.
For instrumentation providers and end-users alike, this regulatory environment creates a dual strategic effect. First, it expands the addressable need for instruments capable of meeting stricter analytical specifications, particularly for emerging contaminants where method harmonization is still stabilizing. Second, it incentivizes the adoption of instruments and workflows that can produce defensible, auditable datasets with minimal manual intervention. Organizations that treat regulation purely as a compliance cost will underinvest in measurement capability; those that treat it as a design parameter for instrument selection, validation planning, and data management will convert regulatory pressure into a competitive moat.
Report Scope: What Decision-Makers Gain From the Full Analysis
This research was constructed to move beyond headline market sizing and into the operational intelligence that shapes capital allocation, vendor selection, product roadmapping, and market-entry strategy. The full study integrates historical performance context, forward-looking forecasts, and structural segmentation that maps how instrument types, application environments, and regional deployment patterns interact to define demand.
Readers will find actionable evaluation frameworks that connect instrument capabilities to real-world procurement criteria, including measurement range suitability, calibration burden, reagent or consumables dependency, field serviceability, and digital integration readiness. The analysis addresses how leading companies are positioning their portfolios across laboratory, process, and field contexts, and where capability gaps create opportunistic entry points for new solutions or strategic partnerships. It also examines the purchasing dynamics that govern laboratory-based versus online deployments, the role of regulatory mandates in shifting preferred analytical methods, and the service, calibration, and consumables ecosystems that influence total cost of ownership over multi-year asset lifecycles.
In addition, the report provides a structured view of recent market developments that signal near-term directional shifts. One notable example is the January 2025 introduction of the HydroRIG IoT gateway device by YSI, an initiative that points toward increasingly connected environmental monitoring deployments and the growing importance of telemetry-enabled data flow in water quality programs. Developments like these are not isolated product news; they are indicators of how instrument manufacturers are building toward continuous, networked monitoring architectures that change how data is generated, transmitted, and acted upon.
Strategic Implications for 2026 Decision-Making
As organizations plan their 2026 capital and capability cycles, several strategic priorities emerge from the market structure we have analyzed. Procurement leaders should evaluate instrumentation purchases against total program value rather than unit transaction cost. That means weighing method alignment, calibration frequency, consumables reliability, field-deployability, and data integration potential alongside initial pricing. R&D and product strategy teams should assess where instrument portfolios need to evolve to meet stricter parametric requirements and where connectivity, automation, or multi-parameter consolidation can unlock operational efficiency. M&A and business development teams should watch how concentration trends intersect with portfolio gaps, particularly where suppliers are extending from standalone measurement into integrated data platforms or expanded method ecosystems.
Regional and application diversification also deserves deliberate planning. Because demand is distributed across multiple geographies and operating environments, firms that rely on a narrow deployment footprint may experience uneven revenue resilience. Expanding service coverage, localizing calibration and support capacity, and tailoring instrumentation specifications to regional regulatory expectations can materially improve market responsiveness. Likewise, organizations operating across both municipal and industrial contexts should avoid forcing a single measurement strategy onto fundamentally different operational rhythms; instrument selection, sampling cadence, and reporting architecture should reflect the decision speed and compliance stakes of each environment.
Why This Research Matters Now
The Water Analysis Instrumentation Market is entering a phase where analytical rigor, regulatory alignment, and digital integration converge to determine competitive positioning. The trajectory from 2026 to 2032 will reward organizations that understand not just how large the market is becoming, but how its internal segmentation, concentration dynamics, and regulatory catalysts shape demand for specific instrument capabilities and service models. The figures and structural patterns outlined here establish the strategic context; the complete report builds the detailed operational blueprint.
We encourage executives, product leaders, procurement strategists, and market-development teams to access the full study for the comprehensive segmentation detail, company profile depth, regional demand architecture, and forward-looking scenario analysis that cannot be summarized in a single overview. The full intelligence package is designed to support investment prioritization, vendor evaluation, product roadmap planning, and risk-adjusted growth strategy across the 2026 to 2032 horizon. In a market where measurement precision increasingly underpins public health, industrial compliance, and environmental resilience, the ability to act on granular, well-structured market intelligence is itself a strategic asset.
For detailed analysis of this topic, please visit the official page: Water Analysis Instrumentation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


