



PW Consulting: 10-Deacetylbaccatin III Market Hits $161.5M in 2025, Poised for 5.5% CAGR Through 2032

Strategic Intelligence for the 10-Deacetylbaccatin III Market: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global landscape for oncology-supporting pharmaceutical intermediates is undergoing a structural transformation, driven by sustained demand for taxane-based therapeutics, expanding regional manufacturing capabilities, and an increasingly rigorous regulatory environment. As therapeutic pipelines continue to rely on semi-synthetic routes for paclitaxel and docetaxel production, the upstream supply of 10-Deacetylbaccatin III has evolved from a niche botanical input into a strategically critical node within the broader pharmaceutical value chain. Our latest market research delivers a comprehensive, forward-looking assessment of this segment, positioning corporate strategists, procurement leaders, and investment professionals with the analytical clarity required to make informed decisions across the forecast horizon.
Worldwide Aged Home Care Market
Designed to anchor executive planning for the 2026 strategic cycle and beyond, this study bridges historical performance tracking with multi-year projection modeling. Rather than offering static snapshots, the analysis maps the momentum of market expansion, dissects the structural forces shaping supply and demand, and evaluates how key enterprise players are positioning themselves amid shifting regulatory expectations, botanical sourcing constraints, and evolving purity specifications. The following exposition outlines the strategic rationale behind this research, previews the analytical architecture of the full report, and demonstrates how the intelligence contained within it can be operationalized to strengthen market entry strategies, optimize procurement frameworks, and refine competitive positioning.
Escape Hoods Market
Market Trajectory: Translating Historical Momentum into Forward-Looking Strategy
Market sizing and growth modeling form the quantitative backbone of any credible strategic assessment. Over the historical window spanning 2020 through 2025, the global 10-Deacetylbaccatin III market has demonstrated a consistent upward trajectory, moving from an initial revenue base into progressively higher valuation tiers as pharmaceutical manufacturers scaled production capacity and secured long-term supply agreements for taxane intermediates. The baseline year of 2025 establishes a clear inflection point, after which the forecast period extending to 2032 illustrates a steady compound annual growth rate that reflects both underlying demand expansion and incremental capacity rationalization across key producing regions.
Worldwide Food Foil Market
For corporate planners, this trajectory is not merely a numerical projection; it is a structural signal. A sustained mid-single-digit CAGR across the forecast window indicates a market that is maturing but far from saturated, with growth increasingly dependent on alignment between intermediate availability, downstream API scheduling, and regional regulatory clearance cycles. The projection framework incorporated in our study captures this dynamic by modeling demand propagation through manufacturing pipelines, accounting for capacity ramp-up timelines, and stress-testing scenarios against potential supply interruptions, botanical harvest variability, and shifts in procurement preference toward higher-purity grades.
Decision-makers leveraging this intelligence can translate the growth curve into actionable planning parameters. Procurement teams can map contract renewal cycles against projected supply tightness, manufacturing strategists can evaluate whether to expand in-house extraction or secure multi-source agreements with specialized botanical intermediate suppliers, and investors can distinguish between cyclical demand spikes and structural growth drivers when assessing exposure to taxane-related segments. By anchoring forecasts to scenario frameworks rather than single-point estimates, the research enables organizations to build flexible operating models that withstand market volatility while capturing upside from capacity expansions and regional demand acceleration.
The research deliberately withholds granular segment-level revenue breakdowns in this introductory preview, reserving those precise allocations for the full analytical suite. This approach ensures that prospective clients experience the methodological rigor of the study while recognizing the necessity of accessing the complete dataset to unlock region-specific sourcing strategies, application-driven demand mapping, and formulation-grade commercial prioritization.
Value Chain Architecture and Procurement Implications
The commercial ecosystem surrounding 10-Deacetylbaccatin III is defined by a complex intersection of botanical sourcing, semi-synthetic processing, regulatory documentation, and downstream pharmaceutical demand. Unlike commodity chemical intermediates, this compound requires specialized extraction and purification pathways originating from Taxus species, which introduces inherent volatility related to harvest cycles, geographic sourcing constraints, environmental regulations, and the operational maturity of extraction facilities. Simultaneously, downstream manufacturers depend on consistent intermediate quality and documented compliance frameworks to maintain uninterrupted production of anti-cancer APIs, making supply reliability as critical as cost competitiveness.
Our study maps this value chain in operational detail, providing procurement and supply chain leaders with a structured view of where value is created, where bottlenecks typically emerge, and how supplier capabilities differ across regions and processing standards. The analysis differentiates between standard formulation pathways and enhanced purity grade outputs, recognizing that while standard formulations address broad commercial manufacturing needs, enhanced purity specifications increasingly influence procurement decisions in markets where regulatory scrutiny, downstream process sensitivity, and quality documentation requirements have intensified.
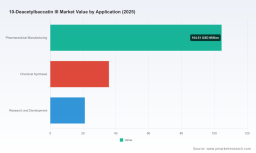
Chemical synthesis and research and development applications further complicate the procurement landscape. While the majority of intermediate demand flows toward pharmaceutical manufacturing, a meaningful share of consumption originates from synthesis programs and R&D initiatives that prioritize availability, documentation, and formulation flexibility over bulk cost optimization. This dual-channel demand structure requires buyers to maintain differentiated sourcing strategies: long-term, volume-oriented agreements for manufacturing-scale requirements, and responsive, specification-sensitive procurement channels for development-stage consumption. The research outlines how leading suppliers structure their commercial offerings to serve both channels, and where structural gaps persist that forward-looking organizations can exploit through targeted supplier partnerships or vertical integration.
For strategic planners, the value chain analysis serves as a diagnostic tool for assessing exposure to supply concentration, evaluating the credibility of supplier certifications, and determining whether existing procurement architectures are aligned with anticipated demand quality and volume trajectories. Understanding how botanical extraction capacity, purification throughput, and documentation readiness interact enables organizations to anticipate lead-time variability, negotiate more effectively, and construct contingency plans that reduce vulnerability to regional disruptions or regulatory hold-ups.
Competitive Landscape: Strategic Positioning of Key Market Participants
The competitive environment for 10-Deacetylbaccatin III is characterized by a fragmented yet increasingly differentiated supplier base, with participants competing across dimensions such as botanical sourcing expertise, regulatory documentation breadth, processing infrastructure, geographic reach, and commercial specialization. Market concentration metrics indicate that while no single enterprise dominates the segment, a cluster of established players has secured meaningful positions through combinations of extraction capability, compliance readiness, and regional distribution networks. The strategic relevance of this landscape lies not in simple market share rankings, but in understanding how each participant’s operational profile shapes their ability to capture demand growth, withstand supply shocks, and expand into adjacent formulation or purity segments.
Indena S.p.A. exemplifies a Europe-based specialist with deep botanical intermediate expertise, leveraging established regulatory documentation and commercial readiness as a pure molecule precursor pathway for docetaxel-related applications. Its positioning reflects a broader strategic archetype: specialized extraction capability paired with compliance-oriented commercial deployment, enabling access to procurement programs that prioritize documented supply continuity and formulation traceability. Phyton Biotech LLC operates from a similar philosophy but with a stronger emphasis on plant-derived pharmaceutical intermediates for semi-synthetic taxane production, reinforcing its role as a globally oriented supplier that bridges extraction capability with downstream manufacturing requirements.
Within the Asia-Pacific region, several producers have built commercial footprints that combine regional manufacturing density with export-oriented distribution. Samyang Biopharmaceuticals Corporation maintains an active supply posture supported by Asia-Pacific manufacturing and distribution infrastructure, making it a relevant reference point for organizations evaluating regional sourcing diversification. ScinoPharm Taiwan, Ltd. brings advanced process control infrastructure to its intermediate production, an attribute that increasingly matters for buyers seeking consistent specification performance and scalable purification capacity. In China, a cluster of producers including Hainan Yew Pharmaceutical Co., Ltd., Fujian South Pharmaceutical Co., Ltd., Chengdu Biopurify Phytochemicals Ltd., Wuxi Taxus Pharmaceutical, and Ningbo Green-Health Pharmaceutical illustrate the breadth of domestic manufacturing capability, ranging from large-scale domestic and export-focused production to GMP-aligned facilities serving pharmaceutical-grade intermediate requirements. Each organization brings a distinct commercial emphasis, whether oriented toward volume leadership, cost optimization for export markets, or compliance and certification readiness.
India-based Alchem International Pvt. Ltd. adds another strategic dimension by combining botanical API manufacturing with a robust certification portfolio, reinforcing its relevance for buyers seeking internationally recognized documentation alongside export capability. Meanwhile, Germany-based PhytoLab GmbH occupies a specialized niche as a reference substance specialist, offering high-purity standards that support research and pharmaceutical benchmarking rather than bulk manufacturing supply. This diversity of strategic archetypes underscores the importance of matching supplier selection to procurement objectives: bulk manufacturing continuity, enhanced purity assurance, regulatory documentation strength, regional proximity, or research-grade standardization.
Our competitive analysis extends beyond individual company profiles to examine how these participants interact within the broader market structure. The study assesses where capacity expansion is likely to alter supply balance, where certification and compliance advantages translate into commercial preference, and where regional manufacturing networks may tighten or loosen depending on export policy, environmental constraints, and downstream demand distribution. For corporate strategists, this competitive mapping provides a framework for evaluating partnership candidates, assessing substitution risk, and identifying which supplier attributes will carry the most weight as regulatory expectations and purity requirements continue to evolve.
Structural Drivers, Regulatory Context, and Emerging Industry Dynamics
The medium-term trajectory of the 10-Deacetylbaccatin III market is shaped by a set of interlocking structural drivers that extend beyond simple demand growth. One of the most significant is the continuing reliance of taxane-based oncology therapies on semi-synthetic pathways that depend on dependable intermediate supply. As downstream pharmaceutical programs scale or sustain production to meet therapeutic demand, the upstream requirement for high-quality 10-Deacetylbaccatin III becomes increasingly embedded in operational planning, contract manufacturing schedules, and API continuity strategies. This structural dependency reinforces the market’s resilience even as pricing, sourcing conditions, and regional production dynamics fluctuate.
Regulatory and quality assurance expectations represent another central force. Buyers in pharmaceutical manufacturing environments are placing greater emphasis on documented GMP alignment, certification breadth, and consistent specification control, particularly when intermediates feed into regulated drug production pathways. In this context, suppliers that can demonstrate robust process control, traceability, and internationally recognized documentation gain a structural advantage, while those competing primarily on price without equivalent compliance readiness face increasing scrutiny. The research captures how these expectations are reshaping procurement criteria and influencing commercial negotiations across regions.
Botanical sourcing dynamics introduce additional complexity. Because the feedstock originates from biologically derived sources, supply planning must account for harvest timing, extraction yield variability, and the operational capacity of specialized processing facilities. Organizations that depend on single-source arrangements or geographically concentrated supply chains face elevated exposure to disruptions, making diversification, buffer inventory planning, and supplier qualification rigor more important than ever. At the same time, suppliers with mature extraction infrastructure, established regrowth or sustainable sourcing practices, and multi-regional distribution capability are better positioned to stabilize availability and support long-term contractual commitments.
In addition to these structural forces, the market is being shaped by evolving procurement preferences around formulation type and purity grade. As manufacturing processes become more sensitive to impurity profiles and downstream yields, demand for enhanced purity grades is gaining strategic relevance, particularly for applications where specification consistency directly influences processing efficiency or regulatory readiness. Simultaneously, standard formulations continue to serve a broad manufacturing base where cost-efficiency and reliable availability remain paramount. The interplay between these demand segments influences pricing behavior, supplier capacity allocation, and the strategic emphasis of intermediate producers as they decide whether to broaden standard-grade output or invest in higher-purity processing pathways.
This preview does not enumerate specific development announcements or transient market events; instead, it frames the analytical lens through which such dynamics are evaluated in the full report. The complete study assesses how operational developments, certification milestones, capacity adjustments, and regional supply shifts alter competitive positioning and procurement strategy, allowing decision-makers to distinguish signal from noise when planning for the 2026 horizon and beyond.
How the Full Research Converts Intelligence into Action
A market research report delivers value only when it converts analytical depth into operational decision support. Our 10-Deacetylbaccatin III study is structured to serve multiple strategic functions simultaneously: as a source of macro-level growth intelligence, as a diagnostic framework for supplier evaluation, as a reference for regional demand distribution, and as a planning tool for procurement, manufacturing, and investment teams. The report integrates historical performance tracking, forecast modeling, segmentation analysis, competitive profiling, and supply chain assessment into a unified analytical system that can be adapted to different organizational use cases.
For procurement and supply chain leaders, the study provides the context needed to design sourcing architectures that balance cost, quality, and continuity. By examining how intermediate supply flows through manufacturing pipelines, where specification sensitivity is highest, and which supplier profiles offer the strongest documentation or capacity advantages, procurement teams can construct more resilient contracts, evaluate multi-source strategies, and prioritize supplier qualification criteria that align with both near-term operational needs and longer-term regulatory expectations.
For business development and market entry strategists, the report offers a structured view of where demand is expanding, which formulation and purity segments present the strongest commercial opportunity, and how competitive intensity varies across sourcing regions. This intelligence supports decisions about partnership selection, distribution channel design, and capacity investment, helping organizations avoid overconcentration in saturated supply pathways while identifying underserved demand pockets that may warrant dedicated commercial engagement.
For investor and corporate strategy teams, the study provides a framework for assessing market maturity, growth sustainability, and competitive differentiation without relying on isolated data points. By linking growth projections to structural drivers, supply constraints, and supplier capability profiles, the analysis enables more disciplined evaluation of opportunities tied to taxane intermediate supply, botanical extraction capacity, and pharmaceutical intermediate manufacturing.
The full report contains the detailed segmentation architecture, regional demand distribution, formulation-grade commercial splits, and company-level capability assessments necessary to execute these strategies with precision. Those core segmentation figures and detailed allocations are intentionally reserved for the complete intelligence package, ensuring that the full depth of the analysis is accessible only to clients who obtain the complete research. This approach preserves the strategic value of the dataset while allowing the preview to demonstrate the rigor, structure, and decision orientation of the study.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a pivotal moment for organizations engaged with pharmaceutical intermediates, botanical extraction supply chains, and taxane-related manufacturing pathways. Demand is not entering a speculative phase; it is continuing along a documented growth path that requires deliberate strategic alignment rather than reactive procurement adjustments. Supplier capabilities are diversifying, regulatory expectations are tightening, and the distinction between standard and enhanced-purity supply is becoming increasingly material to downstream operational outcomes. In this environment, decisions made with incomplete intelligence carry disproportionate risk, while organizations that ground their planning in structured, forward-looking analysis are better positioned to secure supply continuity, optimize cost-quality trade-offs, and build defensible competitive positioning.
This research is designed to support that discipline. It translates historical momentum into forecast orientation, maps competitive capability into procurement and partnership implications, and frames structural drivers in terms that can be directly applied to sourcing strategy, capacity planning, and market development decisions. By engaging with the full study, decision-makers gain access to the segmentation detail, regional demand architecture, company-level capability assessment, and scenario-based planning context needed to move from broad market awareness to executable strategy.
The 10-Deacetylbaccatin III market is not defined solely by its growth rate; it is defined by the strategic choices organizations make in response to supply complexity, regulatory evolution, and competitive differentiation. Our analysis provides the intelligence foundation for those choices. For executives seeking to align 2026 planning with a clear, evidence-based view of market direction and supplier landscape, the complete research offers the depth required to act with confidence and precision.
For detailed analysis of this topic, please visit the official page: 10-Deacetylbaccatin III Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


