



PW Consulting: Screw Press Market to Hit $2.85B by 2032, 7.5% CAGR

Strategic Horizons: Navigating the Screw Press Market Through 2032
The global industrial landscape is undergoing a fundamental shift in how organizations approach wastewater management, sludge dewatering, and resource recovery. As environmental regulations tighten and operational efficiency becomes a primary differentiator, the screw press market has emerged as a critical fulcrum for strategic decision-making. This analysis examines the trajectory of the industry, leveraging comprehensive market intelligence to outline the opportunities and challenges that define the sector from 2026 through 2032.
Worldwide Bellows Pressure Gauge Market
For executive leadership teams and investment strategists, understanding the macro dynamics of this equipment sector is no longer optional. It is a requisite for capital allocation, supply chain planning, and long-term engineering roadmaps. The following insights draw from a detailed market study designed to equip stakeholders with the foresight needed to navigate this evolving environment.
Worldwide Stand-alone Bluetooth Low Energy Modules Market
Market Trajectory and Growth Dynamics
The screw press industry has demonstrated remarkable resilience and expansion over the past half-decade. Historical data indicates a steady climb in revenue generation, moving from approximately 1,200 million USD in 2020 to an estimated 1,720 million USD in 2025. This growth pattern reflects a broader industrial adoption of mechanical dewatering solutions that offer superior solids capture and reduced operational footprints compared to traditional belt press or centrifuge technologies.
Multi-functional Laser Printer Market
Looking forward, the forecast period from 2026 to 2032 suggests a continuation of this positive momentum. The market is projected to reach 1,906.1 million USD in 2026, escalating toward a target of 2,850.0 million USD by the end of the forecast window. This expansion is underpinned by a compound annual growth rate (CAGR) of 7.5 percent. Such a rate signals a mature yet accelerating market, where innovation in design and regulatory compliance are driving incremental gains across multiple verticals.
This trajectory is not merely a function of population growth or increased wastewater volume. It is increasingly tied to the efficiency mandates being imposed on treatment facilities globally. Organizations are recognizing that the total cost of ownership for screw press systems often yields favorable returns over the lifecycle of the equipment, despite higher initial capital considerations. The market intelligence contained in our full report dissects these financial dynamics in detail, offering sensitivity analyses that account for varying energy costs and maintenance schedules.
Regulatory Catalysts and Environmental Compliance
Regulatory frameworks act as one of the most potent accelerators for market adoption. In the United States, data from the Environmental Protection Agency indicates a significant shift in infrastructure strategy. Over 45 percent of municipal wastewater treatment plants upgraded to screw press systems between 2020 and 2023. This migration is largely driven by the dual needs of sludge dewatering efficiency and reduced energy consumption. As utilities face pressure to modernize aging infrastructure without ballooning operational budgets, screw presses offer a compelling value proposition regarding energy per unit of dry solids produced.
Across the Atlantic, the European context presents a similarly robust demand signal. European Environment Agency data shows that screw presses accounted for 41 percent of newly installed sludge handling equipment in EU countries in 2022. This adoption rate is closely linked to stricter wastewater discharge compliance norms under Directive 91/271/EEC. Compliance is no longer just a legal hurdle; it is a strategic imperative that dictates equipment selection.
Furthermore, the European Commission's Circular Economy Action Plan highlights a critical barrier that remains to be addressed. Over 42 percent of small and medium enterprises in wastewater treatment report challenges adopting screw press systems due to high initial capital and installation costs. This statistic underscores a nuanced market dynamic where demand is high, but accessibility remains a friction point for smaller entities. Our analysis explores how financing models and scalable technology configurations might mitigate these hurdles in the coming years.
Technological Differentiation and Efficiency Standards
Engineering advancements are reshaping the competitive battlefield. Manufacturers are increasingly focusing on energy efficiency and material durability to gain market share. For instance, specific screw drive technologies have been developed to exceed current energy efficiency standards of electric motors. These advancements enable maximized electrical efficiency and higher solids throughputs, directly addressing the operational cost concerns that often deter potential buyers.
Material selection also plays a pivotal role in the longevity and performance of these systems. Industry specifications typically utilize stainless steel for wetted parts to withstand corrosive environments, while carbon steel is employed for structural components to balance strength and cost. Understanding the implications of these material choices on maintenance intervals and asset life is a key component of the technical due diligence our report provides.
The emphasis on energy efficiency is not merely a marketing claim but a regulatory and economic necessity. As electricity prices fluctuate and carbon reporting becomes more stringent, equipment that delivers higher throughput with lower kilowatt consumption will command a premium. Stakeholders must evaluate these technical specifications against their local energy contexts to determine the true net present value of their investments.
Regional and Segment Analysis
The distribution of market activity across geographies reveals distinct patterns of maturity and growth. North America holds a significant position in the global landscape, supported by extensive municipal infrastructure upgrades and a robust industrial base. Europe continues to be a stronghold for regulatory-driven adoption, particularly in regions with strict environmental oversight. Meanwhile, the Asia Pacific region represents a substantial volume of activity, reflecting rapid industrialization and expanding wastewater treatment capacities in emerging economies.
Latin America and the Middle East and Africa also contribute to the global total, though their roles often differ in terms of project scale and technology adoption rates. The full market study provides a granular look at how these regions interact with different technology types and application verticals, without relying on simplistic extrapolations.
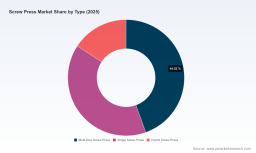
In terms of technology segmentation, the market encompasses various configurations including multi-disc, single screw, and hybrid systems. Each type offers distinct advantages depending on the viscosity of the material and the desired solids concentration. Similarly, application verticals span municipal sludge, industrial wastewater, food processing, and pulp and paper sectors. The interplay between specific technology types and these application verticals creates niche opportunities for specialized providers. Our detailed segmentation analysis prevents decision-makers from averaging out these nuances, ensuring that strategy is tailored to the specific operational context rather than broad industry averages.
Competitive Landscape and Key Players
The market structure is characterized by a moderate concentration of leading players. The top three companies account for 35.2 percent of the market, while the top five represent 52.8 percent. This concentration suggests a competitive environment where established leaders maintain significant influence, but there remains ample room for innovation and niche specialization by smaller or regional entities.
Several key companies define the current competitive architecture. FKC Co., LTD., headquartered in Port Angeles, WA, stands as a worldwide leader in screw press dewatering technology with over 6,000 installations. Their focus on custom-designed solutions for municipal wastewater and thickening applications highlights the importance of customization in this sector. Vincent Corporation, based in the United States, specializes in the design, engineering, and manufacturing of screw presses specifically for squeezing liquid out of organic material, showcasing a focus on organic processing applications.
BDP Industries, located in Greenwich, NY, manufactures the DSP Screw Press dewatering equipment. Their offering emphasizes fully enclosed, USA-constructed units with low energy and water consumption and reduced maintenance, appealing to clients seeking domestic manufacturing and specific efficiency metrics. HUBER Technology, based in Germany, provides the Q-PRESS series for efficient sludge dewatering. Their emphasis on energy efficiency exceeding electric motor standards and high solids capture aligns closely with the regulatory and economic drivers discussed earlier.
On a larger industrial scale, ANDRITZ AG from Austria supplies C-10050 screw press systems for sludge dewatering and liquids/solids separation. Their presence underscores the integration of screw press technology within broader separation technology portfolios. Understanding the strategic positioning, geographic strengths, and technological specializations of these key players is essential for benchmarking and competitive strategy. The full report includes detailed profile analyses that go beyond basic corporate information to assess strategic moves and product pipeline implications.
Strategic Implications for 2026 Decision Makers
As organizations plan for the 2026 fiscal year and beyond, several strategic imperatives arise from this market data. First, capital planning must account for the long-term operational savings versus initial expenditure trade-off. The data showing significant upgrade rates in municipal plants suggests that the industry has already begun voting with its capital, favoring efficiency over lowest upfront cost.
Second, supply chain resilience regarding materials such as stainless steel and specialized drive components should be integrated into procurement strategies. Fluctuations in raw material costs can impact project timelines and budgets, particularly for large-scale infrastructure projects.
Third, the differentiation in technology types implies that a one-size-fits-all approach to equipment selection is suboptimal. Decision-makers must align the specific capabilities of multi-disc, single, or hybrid systems with their unique sludge profiles and regulatory discharge limits. The margin for error in specification is narrowing as performance expectations rise.
Finally, the competitive concentration data suggests that while market leaders are dominant, the barriers to entry in specific niches remain viable for specialized innovators. Partnerships, acquisitions, or targeted R&D investments can allow organizations to capture value in less saturated segments of the application or regional landscape.
Conclusion and Access to Deep Intelligence
The screw press market is poised for sustained growth, driven by a convergence of regulatory pressure, technological efficiency, and infrastructure modernization. However, navigating this growth requires more than a superficial understanding of top-line numbers. It demands a deep appreciation of the interplay between regional regulations, specific technology configurations, and the competitive maneuvers of key industry players.
While this overview establishes the strategic context and highlights the magnitude of the opportunity, it necessarily omits the granular data required for immediate tactical execution. Precise regional revenue splits, specific segment valuations, and detailed company profiles are essential for building robust financial models and operational plans. To access this level of specific intelligence, including the full segmentation breakdowns and comprehensive competitor analyses outlined in this strategy, stakeholders are invited to explore the complete market research document. This resource is designed to transform high-level insight into actionable strategy, ensuring that your organization remains ahead of the curve in a rapidly evolving industrial landscape.
For detailed analysis of this topic, please visit the official page: Screw Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


