



PW Consulting: Organic Rice Market Hits 2100M in 2025 with 8.1% CAGR to 2032

Strategic Intelligence for the Organic Rice Market: Navigating Growth, Regulation, and Competitive Shifts in 2026
Executive Preview: Why This Study Matters Now
The global organic rice market stands at a critical inflection point. Between 2020 and 2025, the sector moved from a niche dietary preference to a structurally embedded component of modern food supply chains. Our latest market research does not merely track historical revenue trajectories; it decodes the operational, regulatory, and competitive forces that will define enterprise strategy through 2032. With a documented compound annual growth rate of 8.1 percent across the forecast horizon, the market is expanding at a pace that demands more than reactive procurement or incremental product adjustments. It requires anticipatory positioning, precise segmentation intelligence, and a clear understanding of how pricing dynamics, certification frameworks, and regional demand signals intersect.
Slide Scanning Microscope Market
This introduction outlines the strategic architecture of the full study. Readers will encounter a synthesis of historical performance, forward-looking revenue modeling, competitive benchmarking, and operational risk mapping. The objective is straightforward: equip executives, category managers, and investment strategists with the contextual framework needed to allocate capital, refine product portfolios, and strengthen supply chain resilience before market conditions shift again. Core segmentation figures, precise regional revenue splits, and granular application-level breakdowns are deliberately withheld here. They are reserved for the complete report, where methodological transparency and data verification protocols ensure that every number can be stress-tested against your internal assumptions.
Automatic Self Cleaning Filters Market
Market Trajectory: From Historical Expansion to Structural Acceleration
The organic rice market has demonstrated consistent upward momentum across the 2020 to 2025 historical window. Revenue progression during this period reflects a combination of consumer health awareness, retail shelf-space reallocation, and growing institutional commitment to clean-label sourcing. What began as a modest base has translated into a substantially larger revenue footprint by 2025, establishing a durable foundation for the forecast period ahead.
Calligraphy Brush and Inkstone Market
Our modeling extends this trajectory through 2032, capturing the compounding effect of sustained demand, channel expansion, and premium pricing viability. The trajectory is not linear across all markets or product categories, but the aggregate growth path remains robust. Executives should interpret this expansion as a signal of structural adoption rather than a short-lived promotional cycle. The market is moving toward a phase where volume growth and margin discipline must be managed simultaneously, and where procurement strategies that worked in earlier growth stages may no longer protect profitability.
Value Pools, Segmentation Logic, and the 2026 Decision Lens
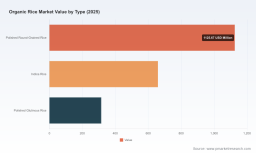
Understanding where value concentrates is essential for portfolio planning, but the real strategic advantage lies in knowing how segmentation boundaries are shifting. The market is organized along multiple axes that influence everything from sourcing contracts to retail pricing architecture. Product-type differentiation, application pathways, and regional demand intensity each create distinct margin environments and operational requirements.
Leaders evaluating 2026 strategy must look beyond headline size and examine the logic that drives segmentation performance. Some categories benefit from established consumer familiarity and streamlined distribution, while others require more sophisticated positioning, certification readiness, or culinary-education support. Likewise, application channels diverge in their sensitivity to input cost volatility, processing complexity, and brand storytelling. Our full study maps these dynamics in detail, allowing decision-makers to identify which segments align with their capability sets and which require partnership, acquisition, or deliberate exit.
The same principle applies to regional demand patterns. Geographic performance is shaped by agricultural capacity, import compliance frameworks, retail maturity, and cultural consumption habits. These variables interact in ways that can amplify opportunity in one market while constraining it in another. Precise regional revenue figures and share distributions are provided in the complete report so that strategic teams can benchmark their exposure accurately and avoid decisions based on generalized assumptions.
Pricing Economics and Raw Material Realities
Pricing is one of the most consequential variables in organic rice strategy, and it cannot be treated as a simple premium overlay on conventional benchmarks. Recent USDA-linked data indicates that organic rice commands a substantial price advantage over conventional equivalents, with premiums reaching a significant multiple of standard market pricing. This differential creates both opportunity and vulnerability. On one side, it supports margin expansion for producers and brand owners who can maintain certification integrity and consistent quality. On the other side, it heightens exposure to input cost fluctuations, yield variability, and consumer price sensitivity during periods of broader inflationary pressure.
Domestic production baselines also matter. Historical output from certified growers provides context for understanding how much supply is generated within key producing regions and how much must be sourced through imports or cross-border supply chains. These structural factors influence lead times, freight exposure, inventory planning, and the feasibility of scaling without compromising certification standards. The full research examine these raw material dynamics in depth, linking pricing behavior to sourcing feasibility and outlining where procurement teams should place greater emphasis on contract structure, supplier diversification, and quality verification.
Regulatory Impediments and Compliance Architecture
Regulation is no longer a background consideration in this market. It now actively shapes trade flow, documentation requirements, and market access timing. Starting October 1, 2025, organic shipments entering the United States require a valid NOP Import Certificate for each consignment. This requirement introduces a new layer of administrative oversight and places greater importance on exporter readiness, documentation accuracy, and customs clarity.
For importers, brand owners, and distributors, the operational consequences are significant. Supply chains that previously relied on streamlined clearance processes must now accommodate more rigorous verification at the point of entry. Delays in certificate issuance, mismatches in documentation, or gaps in audit readiness can disrupt inventory replenishment and weaken retail commitments. The market study addresses these compliance dynamics as part of the broader operating environment, highlighting where risk concentrates and how organizations can build more resilient importation and documentation workflows. Regulatory shifts of this nature often create competitive asymmetry: firms that adapt early secure supply continuity and shelf stability, while late adjusters face avoidable friction.
Competitive Landscape: Positioning, Innovation, and Regional Strengths
The competitive environment is defined by a mix of established North American producers, regional millers, and export-oriented growers who differentiate through certification, variety breadth, and farming philosophy. Strategic positioning in this market increasingly depends on the ability to authenticate sustainability claims, maintain variety diversity, and respond to retail buyer requirements for traceable, clean-label sourcing.
Lundberg Family Farms continues to anchor its offering in renewable and regenerative certification, supported by a broad variety portfolio that spans sushi, basmati, jasmine, arborio, and newer regenerative lines. Its family-operated model and long-standing Sacramento Valley production base provide a recognizable sustainability narrative. Recently, the company expanded its regenerative organic variety presence at a major natural products expo, emphasizing climate-friendly practices and new rice introductions.
Texas Best Organics operates with a different brand architecture, centering on USDA, CCOF, and Kosher certification alongside Non-GMO and gluten-free verification. Its family-owned production and milling structure supports a premium long-grain profile that aligns with consumers seeking verified purity and specialized dietary compatibility. Magnolia Farms, introduced as a premium USDA Organic line from Louisiana farms, brings regional identity, a clean-production emphasis, and a no-synthetic-pesticide positioning to the Southern-grown grain segment. Its launch illustrates how established milling and distribution infrastructure can be leveraged to scale certified organic offerings under a distinct brand identity.
On the export side, Rejaiv Organic represents a different competitive model: chemical-free and residue-free traditional varieties produced through natural farming methods, with distribution oriented toward Central Asia and Europe. Its participation in international trade platforms underscores how authenticity, traditional cultivation methods, and export support ecosystems can be combined to access markets that value provenance and farming transparency.
Recent Developments as Strategic Signals
Recent corporate activity provides useful signals about where the market is heading and how companies are translating positioning into action. Lundberg Family Farms debuted a regenerative organic basmati line alongside its Black Pearl rice variety at a major natural products exhibition, reinforcing its emphasis on climate-aligned farming and differentiated variety extensions. This move suggests continued investment in premium segmentation and sustainability storytelling as growth levers.
In the same period, Farmers Rice Milling Company introduced the Magnolia Farms premium organic rice line as a new USDA Organic offering sourced from Louisiana operations. The launch highlights how established milling enterprises are expanding certified portfolios to capture demand for regionally anchored, clean-label grain products. Meanwhile, Rejaiv Organic engaged in a major international trade show, promoting its organic rice and spice range while emphasizing traditional Indian cultivation methods and export facilitation support. This activity reflects a broader pattern in which export-focused producers are increasingly visible in global sourcing channels and seeking to strengthen recognition among international buyers.
Although each event appears discrete, collectively they point to three recurring themes: expansion of certified variety portfolios, stronger emphasis on regenerative or chemical-free production narratives, and greater attention to export documentation and trade visibility. The complete study translates these signals into competitive assessment frameworks, enabling readers to evaluate how rival strategies may affect shelf access, pricing power, and sourcing availability.
What the Full Study Delivers for 2026 Planning
The complete report is structured to support practical, decision-ready analysis rather than abstract market description. It brings together revenue trajectory modeling, segmentation logic, competitive benchmarking, regulatory impact assessment, and operational sourcing considerations in a single integrated reference. Executives can use it to align product roadmaps, procurement strategies, and market-entry evaluations with the most current structural conditions in the organic rice industry.
Key operational components include:
- Historical revenue context and forward forecast architecture that clarifies the magnitude and pace of growth through the end of the decade.
- Segment-level analysis that explains how product types, application channels, and regional demand patterns shape margin potential and operational complexity.
- Competitive profiling that compares company positioning, certification emphasis, variety breadth, and strategic moves in the recent period.
- Regulatory mapping that addresses import certificate requirements, documentation implications, and compliance readiness for organizations engaged in cross-border trade.
- Source and pricing context that connects premium economics, domestic production baselines, and procurement feasibility to practical sourcing decisions.
The methodology is designed to allow internal teams to test assumptions against verified data, compare scenarios, and identify which variables matter most for their specific business model. Rather than delivering a single static view, the study provides the analytical scaffolding needed to evaluate trade-offs between growth, compliance, and margin protection.
Strategic Implications: Where Leadership Should Focus in 2026
Three priorities emerge clearly when the market evidence is viewed as a whole. First, certification and documentation readiness must be treated as a competitive capability, not a back-office compliance task. With import certification requirements now in force and consumer scrutiny intensifying around authenticity claims, organizations that institutionalize verification, traceability, and audit readiness will gain operational stability and buyer confidence.
Second, segmentation discipline will separate resilient portfolios from overgeneralized product strategies. Not every organic rice category offers the same margin profile, channel fit, or consumer education burden. Companies that match their offerings to segment-specific purchasing drivers and distribution realities are better positioned to manage price sensitivity while preserving premium positioning.
Third, supply chain design must account for both domestic production constraints and import-dependent sourcing pathways. Pricing premiums create attractive economics, but they also amplify the consequences of supply disruption, documentation delays, and quality inconsistency. Diversification, contract structure, and supplier qualification should be reviewed with the same seriousness as product innovation or marketing investment.
Closing Perspective: From Insight to Action
The organic rice market is expanding within a framework that rewards preparation, specificity, and operational discipline. Broad growth signals are valuable, but they are only the starting point for effective strategy. Real advantage comes from understanding where growth is concentrated, how regulation changes market access, which competitive moves alter buying dynamics, and how pricing economics interact with sourcing feasibility.
This introduction has outlined the strategic terrain and the analytical approach of the full study. It has also intentionally withheld the detailed segmentation data, precise regional revenue distributions, and granular application-level figures that are necessary for targeted decision-making. Those elements are available in the complete report, where they are presented with the methodological rigor required for executive planning. For teams responsible for category strategy, procurement, market expansion, or investment evaluation, the full research provides the detailed intelligence needed to convert market momentum into durable commercial advantage.
For detailed analysis of this topic, please visit the official page: Organic Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


