



PW Consulting: Linear Motion Systems Market to Hit $411M by 2032, Growing at 7.7% CAGR

Linear Motion Systems Market Outlook 2026: Strategic Intelligence for Industrial Decision-Makers
Executive Summary
The global linear motion systems sector is entering a decisive phase of expansion, driven by the convergence of advanced automation, precision manufacturing, and next-generation robotics. As industrial ecosystems demand higher throughput, tighter tolerances, and greater energy efficiency, linear motion components have evolved from commodity hardware into mission-critical enablers of operational performance. This introduction outlines the strategic rationale behind our latest market research, framed for executives and engineering leaders who must allocate capital, refine sourcing strategies, and position their portfolios ahead of the 2026-2032 cycle.
ABS Engineering Plastics Market
For organizations navigating complex supply networks and intensifying capability requirements, a structured, forward-looking intelligence framework is no longer optional. The analysis below distills the macro trajectory, competitive architecture, and operational dynamics shaping the sector. It is designed to help leadership teams separate transient market noise from durable growth signals, so they can prioritize investments with confidence.
Worldwide Next-Generation Intrusion Prevention System (NGIPS) Market
Market Trajectory and the Strategic Question for 2026
Linear motion systems have demonstrated consistent expansion over the past half-decade, supported by sustained capital investment in advanced manufacturing and the continuous modernization of automation infrastructure. The market has moved from a base of approximately 200.0 million USD in 2020 to an estimated 250.0 million USD by 2025, reflecting both volume growth and the gradual premiumization of higher-accuracy solutions. Looking ahead, the forecast trajectory extends into the early 2030s, with the sector expected to surpass the 400.0 million USD threshold by 2032.
AI Plush Toys Market
The implied compound annual growth rate across the forecast horizon is 7.7 percent. For strategy teams, that figure is not merely a headline statistic. It signals a market expanding faster than many traditional industrial hardware categories, yet one that remains fragmented enough to reward firms that can distinguish themselves through precision engineering, application-specific integration, and supply chain resilience. The growth path also suggests that annual performance will not be uniform; there will be inflection points tied to technology adoption cycles, end-use capital expenditure patterns, and the pace at which manufacturers translate automation ambitions into production-ready deployments.
This is precisely why 2026 is a pivotal year for decision-making. Companies that rely on backward-looking benchmarks risk misjudging where value will concentrate, especially as product architectures become more integrated and customer expectations shift toward total-cost-of-ownership and lifecycle reliability rather than unit price alone. The market intelligence presented in our full study is built to help executives anticipate these shifts and calibrate their strategic choices accordingly.
Competitive Landscape: Leadership, Differentiation, and the Concentration Equation
The linear motion systems market is characterized by a mix of established multinational manufacturers and highly specialized engineering firms. Concentration levels indicate that a meaningful share of revenue is captured by leading participants, but the market still leaves substantial room for differentiated positioning by region, application expertise, and product architecture. At the same time, the competitive environment is being reshaped by continuous product innovation, geographic expansion, and an increasing emphasis on integrated motion solutions rather than standalone components.
Several companies stand out for their ability to align product portfolios with the highest-value industrial use cases. Bosch Rexroth AG leverages a broad industrial automation heritage, offering precision linear guides, actuators, ball screws, and integrated systems that support robotics and machine tools. Schneeberger Group continues to build reputation around extreme accuracy and durability, targeting demanding applications where repeatability and long-term stability are paramount. Ewellix AB, operating under the Schaeffler Group umbrella, contributes a strong automation and handling portfolio of linear guides and actuators that appeal to manufacturers seeking consolidated engineering support.
In Asia, Hiwin Corporation has become closely associated with linear guides, ball screws, linear modules, and automation solutions tailored to CNC and robotics environments. NSK Ltd. and THK Co., Ltd. anchor strong Japanese engineering traditions in linear motion guides, ball screws, bearings, and LM guide systems, serving both industrial equipment and precision applications. Nippon Thompson Co., Ltd. adds a cost-effective industrial automation dimension with linear guides, bushings, and axis products. In North America, Thomson Industries Inc. and PBC Linear are recognized for spanning precision and heavy-duty use cases, while Parker Hannifin Corporation extends linear actuator and motion control expertise into industrial and aerospace contexts. SKF Group and Rockwell Automation Inc. reinforce the integration angle, with SKF emphasizing linear guides, bearings, and industrial motion products and Rockwell focusing on integrated motion control for factory automation. Additional participants such as Lintech Corporation, HepcoMotion, and Rollon S.p.A. further diversify the landscape with precision slides, robotics-oriented motion systems, and telescopic rails and actuators suited to automation workflows.
Recent market activity underscores how product-level innovation continues to influence positioning. In early 2026, PBC Linear released an updated product catalog and new linear motion technologies, reinforcing a long track record of incremental engineering refinement. Rollon followed with a modular robot transfer unit introduction designed for faster deployment and reliability, and subsequently exhibited at Automate in Chicago during the second quarter of 2026. These moves reflect a broader pattern: competition is increasingly decided by deployment speed, modularity, integration readiness, and the ability to reduce implementation risk for end users.
For procurement and strategy teams, understanding this landscape is essential because supplier selection has become a multi-dimensional trade-off. It now involves precision class, application fit, regional availability, service and customization capacity, and responsiveness to supply-side volatility. Our report develops these competitive dynamics in greater operational detail, enabling readers to benchmark capabilities and identify where strategic partnerships or sourcing shifts can create structural advantage.
Industry Dynamics Shaping Strategy in 2026
Beyond headline sizing and competitive structure, the linear motion market is being shaped by overlapping forces that directly affect cost structures, product development priorities, and customer qualification requirements. These dynamics are not uniform across every application or region, but they collectively define the risk and opportunity environment that executives must manage.
Raw material conditions remain a central concern. Over the 2020-2025 period, rare-earth magnet prices for linear motors climbed sharply, reflecting concentrated supply patterns and tighter environmental permitting requirements for non-Chinese projects. This kind of input cost pressure affects not only bill-of-materials economics but also product roadmap decisions, as manufacturers weigh alternatives, performance trade-offs, and long-term sourcing agreements. At the same time, global linear motion supply chains are exposed to input cost uncertainty from bearing-grade steel, chromium alloys, and specialty polymers, particularly where fixed-price OEM supply agreements limit flexibility. Companies that can anticipate these constraints and model their financial impact will be better positioned to protect margins and maintain delivery reliability.
Regulatory and standards frameworks add another layer of strategic influence. Product development in linear motion systems is increasingly shaped by safety standards and environmental regulations that encourage compliant and energy-efficient designs. For industrial robot systems, safe operation expectations extend to linear motion components used in manipulator and end-effector applications, making compliance a practical requirement rather than a peripheral consideration. In semiconductor-grade environments, the bar is even higher: linear motion systems must meet exacting standards for particle generation, outgassing, and positional accuracy at the sub-micron level. These requirements raise the performance ceiling for qualifying suppliers and reward companies that have invested in process control, cleanliness, and metrology discipline.
Taken together, these dynamics create a market where differentiation is increasingly tied to engineering rigor, compliance readiness, and supply chain transparency. They also help explain why growth is not simply a function of unit volume; it is increasingly driven by the migration of applications into higher-specification classes and the expansion of use cases that demand more capable motion solutions.
What This Research Delivers for Executive Decision-Making
Our full market study is designed as a practical decision-support tool rather than a high-level overview. It connects the macro market trajectory to the operational realities that determine whether a strategy will succeed in execution. The analysis provides a structured view of market sizing and forecast evolution across the 2026-2032 window, allowing leadership teams to test assumptions about demand timing, investment phasing, and portfolio exposure.
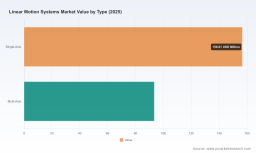
The report also examines segmentation from a strategic perspective, mapping how different type categories and application areas contribute to the broader market architecture. Rather than presenting isolated percentage breakdowns, it contextualizes where capability requirements diverge, where value pools are accumulating, and how product architectures are adapting to application-specific performance demands. This framing is particularly useful for companies evaluating whether to deepen presence in existing segments or reposition toward adjacent opportunities with stronger downstream momentum.
Competitive analysis forms another core pillar. The study profiles the strategies, offering emphasis, and recent movements of key participants, then links those profiles to implications for sourcing, partnership, and positioning. By interpreting recent product launches, catalog updates, and trade-show activity within the broader competitive context, the report helps readers understand not just who is active, but what those moves indicate about future capability priorities and competitive pressure points.
Operational and market dynamics are integrated as well, with attention to material cost exposure, standards-driven design requirements, and the qualification demands that separate general-purpose solutions from application-critical ones. This section is intended to support scenario planning. It gives executives a clearer basis for estimating how input volatility, compliance costs, and performance expectations may affect pricing, lead times, and margin structure over the forecast period.
Importantly, the research is built to be actionable. It supports decisions such as:
- Where to prioritize R&D and product enhancement investments for maximum market relevance
- How to evaluate supplier resilience and qualification readiness in critical applications
- Which end-use adoption trends are most likely to influence demand timing and mix
- How to interpret competitive moves as signals of shifting capability leadership
- Where regional and application dynamics may justify differentiated commercial strategies
Why the Full Report Matters Now
The linear motion systems market is large enough to matter across multiple industrial value chains, yet complex enough that high-level sizing alone cannot guide precise decisions. The difference between a reactive posture and a proactive one lies in understanding how forecast growth translates into segment-specific opportunity, how competitive concentration interacts with fragmentation, and how dynamic cost and compliance pressures alter the economics of product development and sourcing.
The full research report provides the depth required to act on those questions. It offers a comprehensive view of market evolution, competitive behavior, and operational context, structured so that strategy, engineering, procurement, and sales leadership can extract relevant insights without wading through undifferentiated data. It is especially suited to teams that need to align capital planning with market timing, assess supplier landscapes with greater precision, and anticipate the performance thresholds that will define winning offerings in the next phase of industry growth.
Conclusion
As the linear motion systems market advances toward the next stage of its forecast trajectory, the organizations best positioned to capture value will be those that treat market intelligence as a strategic asset rather than a periodic reference point. The macro path suggests continued expansion, but the real opportunities will be defined by application-specific precision, integration capability, supply chain adaptability, and the ability to meet increasingly stringent performance and compliance expectations.
This report introduction is intended to frame the strategic stakes and demonstrate the kind of analytical rigor behind the full study. For executives seeking detailed market sizing, competitive profiling, segmentation context, and forward-looking operational analysis, the complete research provides the comprehensive intelligence needed to support confident decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Linear Motion Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


