



PW Consulting: Sodium Dichromate Market to Hit USD 1,524M in 2025, CAGR 5.2% Through 2032

Strategic Imperatives in the Sodium Dichromate Market: Navigating Growth and Regulatory Headwinds Through 2032
The global sodium dichromate market stands at a critical inflection point. As industrial demand for high-purity chromium compounds continues to anchor critical manufacturing verticals, the interplay between sustained revenue growth and tightening regulatory frameworks will define competitive positioning over the next decade. At PW Consulting, we have just released a comprehensive market intelligence study designed to equip executive leadership teams with the analytical rigor required to navigate this complex landscape. This overview outlines the strategic architecture of the research, distills the macroeconomic trajectory revealed by our models, and demonstrates why disciplined access to granular commercial intelligence is no longer optional for stakeholders operating in the chromium value chain.
Our analysis is anchored in a historical baseline spanning 2020 through 2025 and extends a forward-looking forecast window through 2032. The revenue cadence captured across this period tells a story of steady expansion punctuated by structural transitions. Market valuation climbed from approximately 1,217.0 million USD in 2020 to 1,524.0 million USD by the base year of 2025, reflecting a compound trajectory that underscores the compound's entrenched role in metal finishing, pigment synthesis, wood preservation, and specialty chemical manufacturing. Looking ahead, our forecast models project the market to reach 1,562.75 million USD in 2026 before accelerating toward a terminal valuation of 2,176.14 million USD by 2032. This expansion is underpinned by a forecasted compound annual growth rate of 5.2 percent across the entire projection horizon. Such a growth envelope signals a resilient demand foundation, but it also conceals significant volatility at the segment and regional level that only rigorous primary research can unpack. Executives who rely on aggregated top-line figures alone risk misallocating capital, misjudging regional exposure, and underestimating the strategic urgency of compliance readiness in markets where regulatory architecture is actively evolving. The full study dissects these layers with precision, mapping growth pockets, substitution threats, and pricing elasticity patterns that remain deliberately out of view in this executive summary.
Sodium Dichromate Market
The strategic value of this intelligence crystallizes when placed against the operational realities of the competitive terrain. Our field analysis identifies a concentrated ecosystem of incumbent manufacturers whose technical capabilities, geographic footprints, and supply chain postures will heavily influence pricing dynamics and contract negotiations throughout the forecast period. Leading the field is Vishnu Chemicals Limited, headquartered in Hyderabad, India, which operates as the primary manufacturer of sodium dichromate with a standard specification of 99.5 percent purity. The company's product architecture spans applications in metal passivation, pigments, electroplating, wood preservation, and organic synthesis, delivered through flexible packaging formats including 25-kilogram bags, 50-kilogram bags, and jumbo bags. Its ongoing capacity expansion initiatives are explicitly calibrated to support growing global supply requirements, positioning Vishnu Chemicals as a volume-anchored competitor with established export channels.
Parallel to the Indian manufacturing base sits Nippon Chemical Industrial Co., Ltd., a Japan-headquartered producer that has carved out a differentiated position in high-purity sodium dichromate for metal treatment, aerospace-grade applications, and specialized chemical processes. The company's competitive edge rests on stringent quality standards and a tightly managed Asian distribution network that enables rapid fulfillment for precision-manufacturing clients. Meanwhile, the Chinese supply corridor remains anchored by two substantial integrated players: Hubei Zhenhua Chemical Co., Ltd., an active manufacturer and supplier of sodium dichromate alongside related chromium compounds with a clear focus on competitive Asian market positioning, and Yinhe Group, formally recognized as the China Yinhe Chemical Industry Group, which operates an integrated production model centered on sodium dichromate as a core chromium compound while emphasizing modern production technology and an export-oriented supply architecture. Rounding out the strategic competitive set is Soda Sanayii A.S. of Turkey, a manufacturer that prioritizes production efficiency and product purity to capture both domestic demand and regional market share across Europe and the Middle East.
Our report conducts a structured competitive benchmarking exercise across these entities, examining capacity utilization trends, product grade differentiation, supply chain resilience, and regional distribution leverage. Rather than treating these players as static profiles, the analysis maps their potential strategic responses to the macroeconomic and regulatory pressures outlined in later sections. Which firms are most exposed to feedstock cost volatility? Which competitors are structurally advantaged in markets where procurement teams prioritize certification compliance over unit price? These are the operational questions that procurement directors, commercial strategists, and corporate development teams must answer before negotiating long-term supply agreements or evaluating partnership opportunities. The full publication provides the comparative scoring matrices, competitive positioning maps, and scenario-based procurement simulations that reveal these answers.
No assessment of the sodium dichromate market would be strategically credible without confronting the regulatory inflection that is actively reshaping the chromium value chain. On April 29, 2025, the European Chemicals Agency announced its intent to propose a restriction under the REACH framework targeting hexavalent chromium substances, a category that explicitly includes sodium dichromate. This announcement, coupled with the fact that chromium VI substances are already subject to authorization requirements under REACH Annex XIV, signals that compliance architecture is moving from a background operational concern to a front-line strategic priority. Furthermore, sodium dichromate is included on the EU candidate list of substances of very high concern under REACH, reinforcing the regulatory gravity surrounding the compound's 취급 and end-use pathways.
Basic Chromic Sulfate Market
The ECHA Chromium VI restriction proposal, detailed in the agency's 2025 restriction factsheet, expands the scope of potential market friction across European procurement networks and downstream manufacturing customers. While the restriction framework is still progressing through the formal proposal stage, the directional signal is unambiguous: organizations that depend on sodium dichromate in European-facing supply chains must treat regulatory adaptation as a strategic workstream rather than a reactive compliance exercise. The implications cascade across supplier qualification protocols, alternative chemical evaluation pipelines, inventory management strategies, and long-term contract structuring. Our report dedicates a dedicated strategic dynamics section to mapping the regulatory architecture in detail, translating legislative milestones into actionable business continuity planning frameworks. We examine the interplay between authorization timelines, substitution feasibility windows, and regional compliance divergence, equipping readers with a structured approach to managing regulatory exposure without sacrificing operational continuity.
The strategic landscape cannot be fully interpreted without recognizing the input-side foundations of the value chain. Chromite ore remains the primary feedstock for sodium dichromate production, a structural dependency that links market pricing behavior to mining supply dynamics, geopolitical trade flows, and processing capacity constraints across key producing regions. As highlighted in the USGS Mineral Commodity Summaries 2026, released in November 2025, the availability, grade consistency, and logistics economics of chromite ore exert direct influence on production cost floors and margin sustainability for downstream chemical processors. Our research situates feedstock dynamics within a broader cost-structure framework, exploring how variations in ore availability, regional processing bottlenecks, and energy input costs interact with pricing strategies across the competitive set identified earlier. The report's segment-level analysis examines how feedstock dependency differentiates risk profiles across manufacturers, revealing which companies are structurally insulated through vertical integration or long-term offtake agreements and which remain exposed to commodity-driven margin compression.
The analytical architecture of our sodium dichromate market research is designed to function as an operational decision-support toolkit rather than a static market overview. The publication delivers a multi-dimensional analytical framework that integrates historical revenue reconstruction, forward-looking demand modeling, competitive intelligence synthesis, regulatory scenario mapping, and value chain cost analysis into a cohesive strategic narrative. Readers will gain access to disaggregated market size projections structured around application verticals and geographic corridors, enabling precise allocation decisions for capital investment, capacity planning, and market entry or expansion initiatives. The study provides a structured competitive landscape analysis that benchmarks manufacturer positioning, product-grade differentiation, distribution leverage, and supply chain resilience across the key incumbents shaping the market's trajectory. Alongside these structural analyses, the report embeds a forward-looking regulatory monitoring framework that tracks REACH restriction proposals, authorization requirements, and candidate list inclusions, translating legislative milestones into procurement strategy implications and compliance readiness roadmaps.
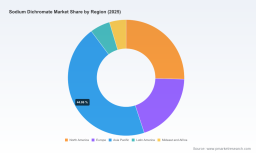
Beyond aggregate and regional market sizing, the research delivers actionable intelligence across several operational dimensions. A dedicated application demand decomposition examines consumption patterns across metal finishing operations, pigment manufacturing, wood preservation formulations, leather tanning processes, and a diversified orbital of specialty chemical applications, revealing where volume growth is structurally anchored and where substitution risk or specification tightening is reshaping procurement preferences. A region-by-region commercial assessment maps demand intensity, supply self-sufficiency levels, import dependency profiles, and regulatory exposure gradients across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The competitive dynamics module integrates capacity expansion signals, technological modernization initiatives, packaging and logistics optimization efforts, and export-market strategies to evaluate which manufacturers are most likely to influence pricing structures and contract terms in the coming five to seven years. Finally, a strategic risk and opportunity matrix synthesizes feedstock dependency, regulatory trajectory, substitution feasibility, and regional compliance divergence into a decision framework that executives can apply directly to supply contract structuring, supplier diversification planning, and R&D prioritization.
The strategic narrative emerging from this research is clear: the sodium dichromate market is not merely expanding, it is restructuring. The convergence of sustained demand growth, a 5.2 percent forecasted CAGR through 2032, and a simultaneous tightening of regulatory architecture across key jurisdictions creates an environment where competitive advantage will be earned through analytical precision and operational preparedness rather than through volume assumptions alone. Organizations that understand where growth is structurally anchored, which manufacturers hold durable supply leverage, and how regulatory timelines will reshape procurement pathways will be positioned to negotiate with confidence, allocate capital efficiently, and mitigate downside exposure before market shifts become operational crises.
PW Consulting's Sodium Dichromate Market research delivers the depth, granularity, and strategic framing required to operate with clarity in this environment. The executive summary above captures the macro trajectory and the analytical architecture of the study; the complete publication unlocks the disaggregated market sizing, regional demand intensity profiles, application-segment growth differentials, competitive benchmarking scorecards, and regulatory scenario frameworks that executives need to translate insight into action. To access the full analyst report, detailed segmentation data, and proprietary strategic models, please visit the PW Consulting research portal. For teams preparing procurement strategies, capacity investment decisions, or market-entry assessments for the 2026 to 2032 horizon, comprehensive intelligence is the difference between reactive adaptation and deliberate advantage.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


