



PW Consulting: Sulphur Recovery Market to Hit $118M in 2025 with 2.51% CAGR Through 2032

Strategic Imperatives in the Global Sulphur Recovery Market: A 2026 Outlook
The global energy and petrochemical landscape is undergoing a profound transformation, driven by tightening environmental regulations, evolving feedstock characteristics, and the relentless pursuit of operational efficiency. Within this complex ecosystem, sulphur recovery stands as a critical operational pillar for refineries and gas processing facilities. As we move through 2026, the ability to navigate the sulphur recovery market with precision is not merely a technical requirement but a strategic imperative for long-term viability and competitive advantage.
PW Consulting is pleased to introduce our latest comprehensive market research study, designed to equip decision-makers with the intelligence needed to thrive in this evolving environment. This article serves as a strategic preview, outlining the macroeconomic trajectory, competitive intensity, and regulatory currents that will define the sector over the coming years.
Macroeconomic Trajectory and Market Resilience
The sulphur recovery market has demonstrated remarkable resilience and volume growth over the past half-decade. Our analysis of historical data from 2020 to 2025 reveals a significant expansion in market revenue, driven by sustained investment in gas processing infrastructure and stricter compliance mandates across major operating regions. The market reached a substantial valuation in the base year of 2025, reflecting the industry's commitment to mitigating sulfur emissions while maximizing resource utilization.
Looking forward, the forecast period from 2026 to 2032 suggests a continued path of measured growth. The projected Compound Annual Growth Rate (CAGR) stands at 2.51 percent, indicating a steady expansion trajectory rather than volatile spikes. This moderate growth rate underscores the maturity of the market while highlighting consistent demand drivers. By the end of the forecast horizon in 2032, the market is expected to reach new revenue milestones, maintaining its status as a vital component of the downstream energy value chain.
It is important to note that market valuation fluctuations observed during the late 2020s reflect broader economic adjustments, supply chain recalibrations, and shifts in capital expenditure priorities among major operators. However, the underlying demand for reliable sulphur recovery solutions remains robust. Investors and stakeholders must understand that while top-line revenue may experience minor contractions in specific interim years, the strategic necessity of sulphur recovery infrastructure ensures long-term market stability.
Regulatory Dynamics and Environmental Pressures
One of the most potent forces shaping the sulphur recovery landscape is the regulatory environment. Governance regarding sulfur dioxide emissions has tightened considerably across key jurisdictions. In the United States, regulations under 40 CFR set specific emission limits for sulfuric acid manufacturing and sulfur recovery operations, compelling facilities to adopt advanced abatement technologies. Similarly, state-level bodies such as the Texas Commission on Environmental Quality govern permitting for sulfur recovery units under strict air quality standards, adding layers of compliance complexity for operators in major production hubs.
Internationally, the impact of International Maritime Organization (IMO) amendments continues to reverberate through the industry. The Mediterranean Sea Emission Control Area mandated a marine fuel sulfur limit of 0.10 percent effective May 2025, reinforcing the need for high-purity sulphur products and efficient recovery processes. Furthermore, the global implementation of IMO 2020 fuel sulfur restrictions and the expansion of Emission Control Areas continue to drive demand for advanced SRU tail gas treating solutions. These regulatory pressures are not temporary hurdles but structural shifts that require ongoing capital investment and technological adaptation.
Feedstock variability also plays a crucial role in shaping operational requirements. Hydrogen sulfide concentrations in acid gas streams range from 5 to 30 percent in gas processing plants requiring sulphur recovery. This variability demands flexible recovery technologies capable of handling fluctuating inlet compositions without compromising efficiency or environmental compliance. Understanding the interplay between feedstock characteristics and regulatory limits is essential for designing future-proof facilities.
Competitive Landscape and Technology Leadership
The sulphur recovery market is characterized by a moderately concentrated competitive structure. Our analysis indicates that the top three companies account for approximately 65.0 percent of market share, while the top five players command around 85.0 percent. This concentration highlights the high barriers to entry associated with proprietary technologies, engineering capabilities, and global service networks required to succeed in this sector.
Leading incumbents continue to leverage their technological portfolios to maintain market dominance. Shell Catalysts & Technologies offers a comprehensive suite of solutions including Claus, SCOT, sulphur degassing, and THIOPAQ O&G sulphur recovery technologies for refineries and gas processing. Similarly, Worley (Comprimo) provides Comprimo SRU and advanced tail gas treatment units designed for high-efficiency sulphur recovery, positioning them as a key partner for large-scale energy projects.
Worldwide Industrial Sulfur Market
European players also hold significant sway in the market. Linde AG supplies LO-CAT sulphur recovery units utilizing low-temperature oxidation processes, while Air Liquide Engineering & Construction licenses the Lurgi Claus process for sulphur recovery from acid gas streams. Technip Energies licenses SmartSulf and Sulphur Recovery processes specifically tailored for the oil and gas industries. These technology licensors play a pivotal role in setting performance standards across the globe.
In the Asia Pacific region, Chiyoda Corporation provides Superclaus and SRU technology with exclusive contracts for advanced sulphur recovery, catering to the region's robust demand. Meanwhile, US-based firms like Fluor Corporation deliver EconoClaus sulphur recovery units integrated with refinery operations, and GTC Technology US offers advanced Claus process and tail gas treating solutions. McDermott engages in SRU design and engineering for gas processing facilities, further diversifying the engineering capability pool.
Specialized players such as Sulfur Recovery Engineering (SRE) in Canada focus on optimization, maintenance, and services for SRU, TGTU, and sour water stripping units, highlighting the growing importance of lifecycle services. Sunway Petrochemical Engineering in Malaysia delivers modular sulphur recovery units for regional refineries, addressing the need for scalable and rapid deployment solutions. KT-Kinetics Technology SpA and Heurtey Petrochem round out the competitive field with their respective low-temperature oxidation units and integrated petrochemical refining solutions.
Recent Industry Developments and Strategic Momentum
Recent project awards and completions illustrate the active engagement of major players in expanding capacity and upgrading existing infrastructure. In December 2025, Worley won a front-end engineering and design contract from ADNOC Gas for the Bab Gas Cap project, including dedicated sulphur recovery units. This underscores the continued investment in large-scale gas processing developments in the Middle East.
In April 2025, KBR-AMCDE secured a Saudi Aramco contract for the modernization of Haradh and Hawiyah Gas Plants, upgrading sulphur recovery efficiency to 99.9 percent. This milestone highlights the industry's focus on maximizing recovery rates to meet stringent environmental targets. Additionally, OMV Petrom completed an investment of 45 million euro in a new sulphur recovery unit at the Petrobrazi refinery in December 2025, signaling strong capital commitment within the European refining sector.
These developments reflect a broader trend where operational efficiency and environmental compliance converge. Companies are not just building capacity; they are upgrading existing assets to achieve higher efficiency thresholds. This shift favors technology providers who can demonstrate proven performance in achieving near-complete sulfur conversion and minimal tail gas emissions.
Operational Segmentation and Strategic Focus Areas
To navigate this market effectively, stakeholders must understand the primary segmentation drivers without getting lost in granular data. The market is broadly defined by technology type, application, and geography. By technology, the Claus Process remains the dominant methodology, accounting for the largest share of recovery operations due to its established reliability and widespread adoption. Tail gas treatment represents a critical complementary segment, increasingly essential as regulatory standards demand near-zero emissions from the overall recovery system.
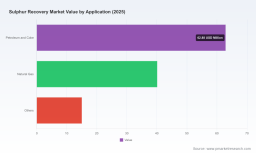
In terms of application, the Petroleum and Coke sector represents the primary demand driver, utilizing sulphur recovery to manage acid gas streams generated during crude oil processing. The Natural Gas segment follows as a significant contributor, reflecting the growth in gas processing activities globally. Other applications also contribute to the market mix, supporting diverse industrial processes that generate sulfur-bearing streams.
Geographically, the market distribution reflects global energy production patterns. Asia Pacific remains a heavyweight region due to its massive refining and gas processing capacity. North America and Europe maintain substantial market presence driven by strict environmental compliance and mature infrastructure. Latin America and the Middle East and Africa regions also contribute to the global footprint, with project activity in these areas often tied to major oil and gas developments. Detailed regional breakdowns and specific application splits are available in our full report.
Value Proposition of the PW Consulting Report
Our latest Sulphur Recovery Market report is designed to be a practical tool for strategic planning. It goes beyond high-level statistics to provide actionable intelligence on market sizing, growth trajectories, and competitive positioning. The report covers the historical period from 2020 to 2025 and offers a detailed forecast through 2032, all expressed in USD millions.
Key contents include a deep dive into market dynamics influenced by regulations, feedstock variations, and techno-economic factors. We analyze the strengths, weaknesses, opportunities, and threats for key market participants, providing a clear view of where value is being created. The study also examines recent developments and contract awards to identify momentum shifts among industry leaders.
Furthermore, the report addresses the nuances of technology licensing, engineering services, and aftermarket support, recognizing that the revenue model in this sector often extends beyond initial CAPEX into long-term OPEX relationships. Understanding the revenue concentration among top players helps inform partnership strategies and competitive benchmarking.
Sulphur Recovery Market
Conclusion: Navigating the Future
As the sulphur recovery market progresses through 2026 and beyond, success will depend on the ability to balance regulatory compliance, operational efficiency, and technological innovation. The steady CAGR of 2.51 percent suggests a market that is stable yet demanding, where incremental improvements in efficiency and reliability can yield significant competitive gains.
Stakeholders must remain vigilant regarding regulatory updates, such as evolving EPA standards and international maritime emission controls, which continuously reshape the operational baseline. Simultaneously, the concentration of market share among top-tier technology providers and engineering firms underscores the importance of selecting the right partners for long-term projects.
This strategic overview provides a foundation for understanding the market's direction, but the full depth of data, segmentation analysis, and competitive intelligence is essential for precise decision-making. We invite industry leaders, investors, and consultants to access the complete PW Consulting Sulphur Recovery Market report to obtain the detailed insights necessary to formulate robust strategies for the 2026-2032 period. The complete intelligence package includes granular segmentation data, detailed company profiles, and comprehensive forecast models that will empower your organization to lead in this critical sector.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


