



PW Consulting: 2-HEMA Market to Hit $704.69M by 2032 with 4.2% CAGR

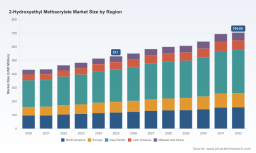
Strategic Intelligence Brief: 2-Hydroxyethyl Methacrylate Market Outlook 2026–2032
The global chemical landscape is undergoing a structural recalibration. For industry leaders operating in specialty monomers, the window for strategic positioning is narrowing as regulatory frameworks tighten and downstream applications demand ever-higher material performance. Our latest market research study on 2-Hydroxyethyl Methacrylate (HEMA) delivers a comprehensive, data-grounded assessment of how this critical building block will evolve through 2032—and what it means for procurement, R&D, and competitive strategy in 2026 and beyond.
This briefing preview synthesises the foundational findings of the full report. It is designed to demonstrate analytical rigor, map the terrain of critical decision variables, and illustrate why a deeper, segmented intelligence package is indispensable for executives navigating the next investment and sourcing cycles. Core numerical breakdowns by region, purity tier, and end-use vertical are intentionally held back; they are available in their complete, modelled form within the published study.
Macro Trajectory: A Market in Steady Expansion
Historical reconstructions from 2020 through 2025 reveal consistent top-line growth for HEMA, with global revenue climbing from approximately 432.19 million USD to a recent base-year level of 531.0 million USD. The momentum does not plateau. Our forecast horizon extends through 2032, projecting a continued upward arc that carries the market past the 700-million-dollar threshold by the close of the period. The compound annual growth rate across this forecast window is modelled at 4.2 percent, a figure that reflects resilient demand across established application sectors and emerging high-value segments.
Several structural forces underpin this trajectory. The shift toward electric mobility has intensified requirements for advanced thermal-management coatings and protective resin systems. Biomedical and dental material innovation continues to drive demand for ultra-high-purity grades that meet stringent regulatory and biocompatibility thresholds. Simultaneously, optical clarity requirements in consumer and medical hydrogels, along with specialty adhesive formulations, create incremental pull from purity-sensitive applications. These demand vectors are not evenly distributed; they concentrate value in specific purity windows and regional supply nodes, a dynamic that is unpacked in granular detail in the full study.
The Purity Paradigm: How Specification Drives Commercial Value
Not all HEMA is commercially equivalent. Purity thresholds act as powerful pricing and demand filters, and the market has bifurcated around three dominant specification tiers. Producers and buyers alike must understand where value accrues, where margin pressure exists, and how technical requirements translate into procurement premiums.
High-purity grades command particular attention in sectors where impurity profiles directly affect end-product performance. Biomedical, pharmaceutical, and optical applications mandate rigorous distillation, repeated testing, and adherence to ISO-aligned quality protocols for material designated at or above 99 percent purity. These specifications are not optional extras; they are preconditions for market entry in regulated verticals. Slightly lower purity bands still hold substantial commercial relevance, particularly in coatings and reactive resin formulations where cost-performance balances differ. The full report maps exactly how each purity tier contributes to value creation and identifies which downstream customers are willing to pay for specification upgrades versus those optimising on grade cost.
Application Segmentation: Where Demand Is Concentrated
HEMA flows into a diverse but unevenly weighted set of end markets. Coatings represent a major consumption hub, leveraging the monomer’s contributions to gloss, adhesion, and film integrity. Reactive resins form another substantial pillar, particularly where cross-linking behaviour and interfacial compatibility matter. Adhesives capture a meaningful share, benefiting from HEMA’s ability to fine-tune tack, flexibility, and bond durability. A residual category encompasses specialised and niche deployment scenarios that, while individually smaller, collectively represent innovation frontiers.
The strategic significance of this segmentation lies in its asymmetry. A relatively small shift in specification requirements within a high-value application can disproportionately impact overall margin profiles. Likewise, regional demand patterns differ markedly, shaped by local manufacturing intensity, regulatory stance, and the maturity of downstream processing clusters. Our analysis isolates the precise contribution of each application vertical and each geography, but the full breakdown—with scenario-tested sensitivities—is reserved for the complete intelligence package.
Competitive Landscape: Capability, Geography, and Moves
The HEMA market is characterised by a moderately concentrated supplier base, with a limited number of players controlling a substantial share of throughput. Competitive positioning depends on a combination of manufacturing footprint, purity capability, application-specific technical support, and responsiveness to regulatory shifts.
2-Hydroxyethyl Methacrylate Market
2-Ethylhexyl Methacrylate (2-EHMA) Market
Several active participants illustrate the current market architecture. Shakti Chemicals, headquartered in Mumbai, operates as a trader and supplier supporting polymer chemistry applications across Asia, emphasising regional distribution reach. Qingdao RENAS Polymer Material Co., Ltd., based in Qingdao, China, focuses on HEMA as part of a broader specialty chemicals and polymer materials portfolio. Nantong Chem-land Co., Ltd., also in China, supplies high-purity grades for industrial and specialty use, aligning product range with specification-sensitive buyers. Yancheng Green Chemicals Co., Ltd., likewise situated in China, manufactures HEMA for polymer synthesis and advanced chemical applications, reinforcing the country’s role as a production anchor.
Beyond these named participants, the competitive field includes larger diversified chemical firms that deploy HEMA in more complex value chains. Recent activity underscores how innovation and compliance shape the battlefield. In mid-2025, Chemical United introduced HEMA HISS, an ultra-pure 99.5 percent grade engineered for high-clarity applications spanning soft contact lenses, 3D-print resins, medical hydrogels, and high-gloss formulations. This launch signals intensifying competition at the premium purity end and the growing importance of application-tailored product architecture.
In October 2024, Dow collaborated with an automotive manufacturer on a new HEMA-based coating for electric vehicle batteries, with demonstrated improvements in thermal management and battery-life extension. Such application-led co-development points toward a future where monomer value is co-created with downstream partners rather than sold as a commodity specification. In January 2024, Evonik launched VISIOMER HEMA-P 100, a phosphate methacrylate monomer derived from HEMA, aimed at enhancing flame retardancy, adhesion, and corrosion resistance in coatings and composites. This type of derivative innovation expands the functional envelope of HEMA chemistry and creates adjacent opportunity spaces.
Regulatory and Environmental Constraints as Strategic Variables
Regulation is no longer a background condition; it is a direct driver of market structure. The EU Cosmetics Regulation (EC 1223/2009) restricts HEMA in nail cosmetics to professional use only, mandating specific labelling and barring non-compliant products from market entry since September 2021. In contrast, the United States continues to permit HEMA in dental adhesives, medical tapes, and wound dressings without equivalent professional-use limitations, preserving broader access for medical and dental applications. This transatlantic divergence creates distinct compliance pathways and affects how multinational suppliers design portfolio strategies for Western markets.
Environmental and safety considerations further embed operational constraints. HEMA is hydrolysed to methacrylic acid and ethylene glycol, and producers are expected to monitor and treat effluent to limit release to roughly 0.02 tonnes per year per plant. These abatement expectations shape capital planning and regional siting decisions. Meanwhile, upstream feedstock exposure remains significant: HEMA production depends on ethylene glycol, with prices exhibiting high volatility linked to crude oil and natural gas cycles. Margin management therefore requires forward-looking procurement strategies and, where feasible, integration or hedging mechanisms that reduce exposure to energy-linked input swings. ISO standards for high-purity grades (99 percent and above) add another compliance layer, mandating rigorous distillation and testing protocols for biomedical and pharmaceutical applications.
Why 2026 Calls for Decision-Ready Intelligence
The coming year will test companies on multiple fronts at once. Feedstock volatility will continue to complicate cost forecasting. Regulatory divergence will force region-specific packaging, labelling, and distribution decisions. Premium-purity demand will accelerate where biomedical, optical, and high-performance coatings converge. At the same time, capital allocation decisions on capacity, purification capability, and technical service infrastructure must be made with a view toward 2032, not merely the next quarter.
Executives need more than headline numbers. They require a decision architecture that connects macro trajectory to segment-level economics, maps competitive capability to application opportunity, and quantifies how regulatory and environmental constraints alter viable market access. The full report is built for exactly this purpose.
What the Full Study Delivers
Beyond the macro arcs and competitive snapshots previewed here, the complete market research package provides:
- A fully segmented revenue model by region, purity tier, and application, capturing both current sizing and forecast evolution through 2032 without exposing sensitive breakdowns until accessed in full.
- Scenario-tested sensitivity analysis around feedstock price volatility, enabling procurement and finance teams to stress-test margin assumptions under alternative energy-price pathways.
- A detailed regulatory matrix covering EU cosmetics restrictions, US medical and dental permissions, environmental effluent expectations, and ISO-grade quality protocols, with implications mapped to product strategy and market entry.
- Company-level profiles and recent development tracking for active market participants, including product launches, application co-development, and derivative innovation that signal where competitive advantage is being built.
- Strategic recommendations aligned to sourcing, capacity planning, specification upgrades, and regional compliance positioning, calibrated to different organisational roles from R&D to commercial leadership.
The complete dataset, including region-by-region and application-by-application contributions along with the precise revenue figures underpinning each segment, is available in the published report. Accessing the full study provides the granular intelligence required to translate market direction into concrete commercial and operational decisions.
Conclusion: Position Now or Pay Later
The HEMA market is expanding, but growth is uneven and increasingly governed by specification, compliance, and application-specific performance requirements. A 4.2 percent compound annual growth rate through 2032 is meaningful, yet the real strategic question is not how large the market becomes—it is which segments, which purity tiers, and which geographies will capture disproportionate value. Companies that act in 2026 with precise, segment-aware intelligence will be better placed to secure feedstock resilience, align product portfolios with regulatory realities, and capture premium demand where performance thresholds create pricing power.
This briefing has outlined the terrain. The full report delivers the detailed map. For procurement leaders, R&D strategists, and commercial executives, the study provides the decision-grade foundation needed to move from awareness to action before the window narrows further.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


