



PW Consulting: Waste Paper Recycling Market to Reach $74.3B by 2032, 5% CAGR

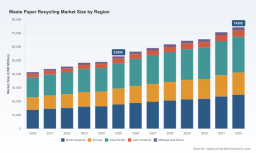
Strategic Intelligence for the Waste Paper Recycling Market: Navigating Growth from 2026 to 2032
The global waste paper recycling industry stands at a critical inflection point. As environmental regulations tighten and corporate sustainability mandates become non-negotiable, the sector is transitioning from a linear waste management model to a circular economy cornerstone. For strategic decision-makers, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning. This analysis draws upon comprehensive market research to outline the opportunities and risks defining the period from 2026 through 2032.
Market Trajectory: From Recovery to Sustained Expansion
The macroeconomic backdrop for waste paper recycling is characterized by robust historical growth and a confident forecast horizon. Tracing the valuation from the base year 2025 through the forecast period ending in 2032 reveals a sector that has successfully weathered economic volatility to establish a strong upward trend. In 2020, the market valuation stood at approximately 41,500 million USD. Over the subsequent five years, the industry demonstrated resilience, climbing to 48,982.3 million USD by 2024 despite supply chain disruptions and fluctuating raw material costs.
The momentum accelerated leading into the current baseline, with the market size reaching 53,000 million USD in 2025. This growth trajectory is projected to continue, with the valuation expected to breach 56,491.54 million USD in 2026. Looking further ahead, the compound annual growth rate (CAGR) is estimated at 5.0 percent throughout the forecast period. By 2032, the market is anticipated to reach 74,300 million USD. This steady expansion underscores a structural shift in how industries view recovered fiber—not merely as waste, but as a valuable commodity integral to manufacturing supply chains.
Key Growth Drivers and Industry Dynamics
Several converging forces are fueling this expansion. First, the global push toward reducing carbon footprints is driving demand for recycled content in packaging and tissue products. Second, regulatory frameworks in key economic zones are increasingly mandating minimum recycled content thresholds, effectively creating a price floor for recovered paper. Third, technological advancements in sorting and pulping efficiency are lowering the operational costs of recycling facilities, improving margins for processors.
Recent industry data highlights the sensitivity of this market to supply and demand fundamentals. For instance, in March 2026, recovered paper prices for Old Corrugated Containers (OCC) increased due to stronger demand for recycled fiber coupled with tightening supply. Such fluctuations indicate a mature market where inventory management and long-term supply contracts are becoming critical strategic levers. Companies that secure reliable feedstock sources will hold a distinct advantage as competition for high-grade waste paper intensifies.
Segmentation Insights: Where Value is Concentrated
Understanding where value resides within the waste paper recycling ecosystem is essential for targeted investment. The market is segmented by type, application, and region, each presenting unique risk-reward profiles. While specific granular data is reserved for the full report, the broader distribution patterns reveal where strategic focus should be applied.
Material Types and Processing Requirements
The market encompasses various grades of waste paper, each requiring distinct processing technologies. Corrugated cardboard remains a dominant stream due to its prevalence in logistics and e-commerce packaging. High-grade paper and old newspapers or magazines also constitute significant portions of the feedstock mix. Mixed paper presents a more complex challenge due to contamination risks but offers volume potential. The choice of processing equipment—whether shredding, pulping, or baling—depends heavily on the specific material stream a company intends to target. Investing in the wrong technology for a specific paper grade can erode margins quickly.
Application End-Uses
The downstream demand is diversified across several key industries. Packaging represents the largest consumption channel, driven by the retail and e-commerce sectors' relentless demand for sustainable boxes and containers. Construction utilizes recycled fiber for insulation and other materials, while printing and writing applications maintain a steady, albeit slower-growing, demand. The tissue and hygiene sector is another critical consumer of high-quality recycled pulp. Understanding the yield rates and quality specifications required by each application is vital for recyclers aiming to maximize revenue per ton of input material.
Regional Nuances
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific, in particular, has shown significant activity due to industrialization and urbanization trends. However, regional regulations regarding waste imports and exports create varying operational landscapes. A strategy that works in North America may not be directly transferable to Latin America or Europe without adjusting for local compliance costs and infrastructure maturity.
Competitive Landscape: Technology Leaders and Strategic Roles
The competitive environment is fragmented but features distinct players who dominate specific niches of the technology stack. The market concentration metrics indicate a moderate level of consolidation, with the top three companies holding a notable share and the top five increasing that presence. This suggests that while there is room for specialized players, scale and technological superiority are becoming increasingly important.
Equipment Manufacturers and Technology Providers
Several key companies define the current equipment landscape, offering solutions that range from primary shredding to complete turnkey recycling lines. WEIMA , based in Germany, focuses on single-shaft shredders such as the WLK 15 and WLK 18 Jumbo models. These are designed for efficient processing of paper, cardboard, and OCC into flakes or pulp, offering customizable configurations for recycling lines. Their technology is critical for initial size reduction and preparation.
In the realm of complete processing facilities, Parason Engineering from India provides turnkey recycled-fiber lines. Their offerings include pulpers, cleaners, screens, and deinking systems for OCC and mixed waste. These lines produce board, liner, newsprint, and tissue at capacities ranging from 8 to 1030 TPD. This breadth allows them to serve both small-scale localized operations and large industrial mills.
For material handling and volume reduction, American Baler Company and Maren Engineering Corporation in the USA are prominent. American Baler specializes in horizontal and two-ram balers engineered for OCC, paper, and cardboard bales, reducing volume and labor in recycling and distribution centers. Maren Engineering complements this with horizontal auto-tie, two-ram, and closed-door balers specifically for OCC and cardboard recycling to flatten material for storage and transport. Efficient baling is crucial for logistics economics, directly impacting the cost of moving recycled fiber to mills.
On the shredding and pre-processing side, BHS-Sonthofen in Germany provides shredders and pre/post-shredding equipment for paper, cardboard, and OCC in recycling applications. Meanwhile, SOYU in China focuses on OCC dry pulping and recycling lines that convert waste paper into recycled pulp with energy-efficient dry processing. This energy efficiency angle is becoming a key differentiator as energy costs rise. Rexon Hydraulics , also based in India, offers automatic horizontal paper balers and recycling machines for cardboard and OCC, catering to the automation needs of modern facilities.
Recent Market Movements
Market activity remains dynamic. In June 2026, ReBAT confirmed its status as an exhibitor at the World of Recycling Expo 2026 in India, showcasing material recycling machinery including waste paper solutions. Such events highlight the ongoing innovation cycle and the importance of industry networking for identifying emerging technologies and partnership opportunities. Participation in major expos often signals a company's commitment to expanding its footprint in high-growth regions.
Waste Paper Reuse Market
Strategic Imperatives for 2026 Decision Makers
For executives and investors looking to navigate this landscape in 2026, several strategic imperatives emerge from the data.
Waste Paper Recycling Market
- Supply Chain Security: With tightening supply noted in recent months, securing long-term contracts with waste generators or establishing owned collection networks is vital. Volatility in OCC prices can impact profitability significantly.
- Technology Alignment: Investing in the right machinery is crucial. Whether it is energy-efficient dry pulping, high-capacity shredding, or automated baling, the technology must match the target material stream and end-use quality requirements.
- Regional Compliance: Navigating the regulatory divergence between regions like Europe, North America, and Asia Pacific requires localized expertise. Compliance costs can vary widely and impact the economic feasibility of cross-border trade in recycled materials.
- Capacity Planning: With the market projected to grow steadily towards 2032, capacity expansion plans must be timed correctly. Overbuilding too early risks underutilization, while delaying risks missing the demand surge driven by sustainability mandates.
Conclusion: The Value of Comprehensive Market Intelligence
The waste paper recycling market offers substantial opportunities for growth, but realizing them requires more than just general industry awareness. It demands a granular understanding of segmentation splits, competitive positioning, regulatory pressures, and technological capabilities. The macroeconomic numbers tell a story of growth, but the operational details tell the story of profitability.
This overview serves as a high-level indicator of the trends shaping the industry. However, the complex interplay between material grades, regional regulations, and specific equipment specifications requires deeper analysis. For organizations aiming to make informed capital deployment decisions or strategic partnerships in this sector, access to detailed segmentation data, company profiles, and risk assessments is indispensable.
To fully leverage the 5.0 percent CAGR opportunity and navigate the competitive landscape defined by key players like WEIMA, Parason, and others, stakeholders need the complete intelligence picture. The full market research study provides the necessary depth on segmentation values, historical trends, and forecast nuances to build a robust strategy for the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Waste Paper Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


