



PW Consulting: Office Storage Market Hits USD 3.15 Billion in 2025, Projected 7.9% CAGR to 2032

Unlocking Strategic Value in the Office Storage & Organization Market: A 2026 Executive Briefing
The modern workplace is undergoing a structural transformation. As hybrid work models solidify and organizations rethink physical footprint efficiency, the Office Storage & Organization Market has emerged as a critical infrastructure layer for operational productivity, compliance, and spatial optimization. For executive leadership, facility managers, and procurement strategists, the question is no longer whether to invest in smarter storage ecosystems, but how to align those investments with long-term growth trajectories, cost containment mandates, and evolving workplace safety mandates.
Our latest market research publication delivers a comprehensive, data-grounded assessment of this sector, mapping historical performance, forward-looking demand signals, competitive positioning, and the macroeconomic forces reshaping procurement decisions. This briefing outlines the strategic architecture of the study and explains why it serves as an essential decision-support tool for 2026 planning cycles.
Macro Trajectory: Scaling Demand in a Shifting Workspace Economy
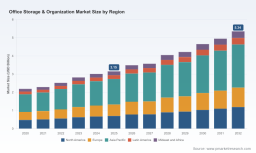
Over the past half-decade, the office storage and organization sector has demonstrated consistent expansion, reflecting broader trends in workplace rationalization, inventory visibility, and the formalization of remote and hybrid work environments. Historical tracking from 2020 through 2025 shows a steady climb in market revenue, with the sector moving from approximately 2.18 billion USD to 3.15 billion USD by the base year. This upward arc underscores a sustained organizational appetite for structured storage solutions that support document management, equipment housing, and spatial decluttering across corporate and decentralized work settings.
Looking ahead, the forecast horizon through 2032 projects continued momentum, with the market anticipated to reach 5.34 billion USD by the close of the period. The implied compound annual growth rate of 7.9 percent signals a sector that is not merely recovering from post-pandemic workspace adjustments, but actively re-architecting how organizations store, access, and manage physical assets. This growth trajectory carries meaningful implications for capital allocation, supplier relationship management, and facility planning. Decision-makers who internalize the pace and shape of this expansion can better time procurement cycles, negotiate volume commitments, and align storage investments with broader workplace modernization roadmaps.
Office Furniture Market
Structural Shifts Driving Buyer Behavior and Product Preference
The sector’s evolution is being shaped by several intersecting forces that alter both demand composition and supplier strategy. First, the proliferation of remote and hybrid work arrangements has expanded the addressable footprint for home office storage and organization products. As professionals convert residential spaces into functional work environments, demand for scalable, aesthetically cohesive, and ergonomically mindful storage units has grown. This shift is not simply a residential trend; it reverberates through corporate procurement as employers extend stipends, equipment packages, and standardized organization kits to distributed workforces.
Second, workplace safety and regulatory expectations are tightening the specification criteria for storage infrastructure. Occupational safety regulations increasingly require storage units to meet defined load-bearing thresholds and fire-resistance standards. These requirements elevate the importance of compliance-ready designs, pushing buyers toward suppliers that can document material certifications, structural testing, and adherence to regional building and fire codes. In practice, this means procurement teams must evaluate not only storage capacity and modularity, but also the evidentiary trail that supports regulatory conformity.
Third, cost dynamics are introducing complexity into margin planning and pricing strategy. Raw material volatility affecting steel, wood composites, and engineered plastics has constrained manufacturers’ ability to absorb cost fluctuations without adjusting product pricing or reprioritizing feature sets. Simultaneously, the wood office-furniture producer price index reached elevated levels in mid-2025, creating cost headwinds that ripple through the broader storage and organization supply chain. For buyers, this environment rewards strategic sourcing, multi-supplier diversification, and specification flexibility that preserves functional requirements while mitigating exposure to input-cost spikes.
Finally, financing mechanisms are shaping deployment timing, particularly for small and mid-sized enterprises. In the United States, Small Business Administration 504 loans provide long-term financing pathways for office storage infrastructure investments. This availability can smooth capital expenditure planning, enable phased rollouts, and help organizations align storage upgrades with broader facility improvement programs. Understanding the interplay between financing options and procurement cadence is increasingly relevant for market participants evaluating total cost of ownership rather than upfront price alone.
What the Report Delivers: Operational Intelligence for Procurement and Strategy Teams
This research is structured to move beyond headline figures and provide actionable intelligence that supports real-world decision-making. The study combines quantitative modeling with qualitative assessment, giving readers a multidimensional view of market behavior, supplier capabilities, and demand-side priorities. Key components of the publication include:
- A detailed historical reconstruction of market performance across the 2020–2025 period, establishing a reliable baseline for evaluating growth consistency, demand elasticity, and segment maturation.
- A forward-looking forecast framework extending through 2032, designed to help organizations stress-test procurement assumptions, plan capacity alignment, and anticipate inflection points in adoption.
- An examination of product-type dynamics, contrasting conventional office storage cabinets with mobile shelving systems, including the operational trade-offs that influence selection in different workspace configurations.
- An application-level analysis that disaggregates demand across corporate headquarters, remote home offices, and other deployment contexts, highlighting how use-case requirements shape specification, throughput expectations, and purchase frequency.
- A regional perspective that maps demand distribution and contextual factors across major geographic markets, supporting multinational planning and localization strategies.
- A competitive landscape assessment that profiles leading participants, evaluates strategic positioning, and tracks recent product and catalog developments that signal where the market is heading.
- An integrated review of market concentration indicators, providing context on supplier consolidation, pricing power, and the degree of fragmentation or consolidation that characterizes the sector.
The report is intended for use by strategic procurement leaders, workplace operations executives, financial planners, and market-entry teams who require a structured, evidence-based foundation for evaluating storage and organization investments. Rather than treating the sector as a commoditized furniture category, the study frames it as a functional infrastructure market where compliance, space efficiency, durability, and total cost of ownership carry decisive weight.
Competitive Landscape: Positioning, Innovation, and Recent Market Signals
The competitive environment in office storage and organization reflects a blend of established manufacturers, specialized systems providers, and broad-access retail players. Each category brings a distinct value proposition to buyers, and understanding these differences is essential for evaluating supplier fit, negotiating terms, and building resilient supply chains.
Companies such as Office Furniture EZ operate through a hybrid distribution model that combines physical showroom access with online catalog availability, offering modular furniture, cabinets, and accessories that appeal to buyers seeking visible product interaction and convenient catalog browsing. SHUTER emphasizes manufacturing capability with a focus on modern office storage cabinets, tool storage, and organizational systems built around innovation and durability, positioning itself for customers who prioritize engineered reliability and product evolution. Livinbox enters the space with a design-oriented approach, crafting stylish home and office storage products, plastic containers, organizers, and modular solutions that resonate with buyers balancing aesthetics and practicality. HNI Corporation contributes high-density storage systems and office organization solutions integrated with broader workplace furniture offerings, making it relevant for organizations pursuing space optimization within a unified furniture strategy. Spacesaver Corporation specializes in high-density mobile storage and organization systems, targeting environments where maximizing accessible storage within limited footprints is a core operational requirement.
Additional participants broaden the market’s reach and purchasing pathways. Montel Inc. provides storage and organization solutions tailored to office environments, while The Container Store extends retail and home office storage options that support productivity-focused organization for distributed professionals. Ikea remains a prominent global retailer of affordable, modular office storage and organization products, offering a value-focused entry point for cost-sensitive buyers and standardized deployment scenarios.
Recent company activities reinforce the sector’s dynamic character. In 2026, Office Furniture EZ released its product catalog featuring office storage and organization solutions, while SHUTER issued a 2026 catalog highlighting modern office storage cabinets and organizational systems. Livinbox meanwhile showcased new product lineups at major trade events, signaling continued product refresh activity and an emphasis on visible innovation in storage design and modularity. These developments illustrate how competitors are using catalog expansion and product showcases to capture attention, differentiate capabilities, and align offerings with evolving buyer expectations.
Market concentration data provides additional context for competitive assessment. With a CR3 of 25.0 percent and a CR5 of 30.0 percent, the sector exhibits a moderate degree of consolidation without full concentration at the top. This structure suggests that while leading players hold meaningful share, there remains ample room for specialized suppliers, regional performers, and design- or price-focused entrants to compete on specification, service, and niche application fit. For procurement leaders, this landscape supports a dual strategy: leveraging scale and consistency from established suppliers while preserving flexibility through secondary sources that can address specialized requirements or cost constraints.
Office Storage & Organization Market
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to connect market structure with operational consequence. In 2026, organizations are making decisions under multiple pressures: the need to optimize real estate and workspace utilization, the imperative to maintain compliance with evolving safety standards, the challenge of managing input-cost volatility, and the expectation to support distributed workforces with consistent, reliable storage solutions. A superficial view of the market can lead to under-specification, reactive purchasing, or over-reliance on single-supplier relationships. A structured, evidence-based view enables more disciplined planning.
For procurement and operations leaders, the report provides a basis for comparing product types against actual usage scenarios, weighting durability and compliance alongside capacity and aesthetics, and evaluating supplier portfolios against recent innovation signals. For financial and strategy teams, the forecast framework supports scenario modeling around demand growth, investment timing, and the potential impact of financing instruments on deployment schedules. For market-entry and business development teams, the segmentation and competitive analysis clarifies where differentiation is achievable and which buyer priorities are most likely to shape purchasing decisions over the forecast period.
Equally important, the study helps organizations avoid misreading the market as purely price-driven. While cost remains a central factor, the sector’s trajectory is increasingly defined by functional performance, regulatory readiness, modular flexibility, and the ability to support both centralized and distributed workplace models. Buyers who evaluate storage and organization investments through this broader lens are better positioned to secure long-term value rather than short-term savings that may compromise durability, compliance, or adaptability.
Conclusion: Moving from Awareness to Actionable Intelligence
The Office Storage & Organization Market is expanding at a measured but meaningful pace, shaped by workspace redesign, regulatory compliance, material-cost dynamics, and the continuing normalization of hybrid work. The sector’s projected growth through 2032 reflects an environment in which storage infrastructure is no longer a peripheral procurement category, but a core enabler of productivity, safety, and spatial efficiency.
This research publication is designed to give executives the depth they need to act with confidence. It integrates historical context, forward-looking modeling, competitive profiling, and industry dynamics into a single decision-support framework. To access the full segmentation detail, regional breakdowns, application-level evaluations, and complete competitive intelligence, we invite stakeholders to review the complete report through our official research portal. The full dataset and proprietary analysis are available there for teams ready to translate market insight into structured 2026 and beyond procurement strategies.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


