



PW Consulting: Synthetic Concrete Fibers Market Set to Hit $344.8M by 2032 at 6.5% CAGR

Navigating the Synthetic Concrete Fibers Market: Strategic Intelligence for 2026 and Beyond
The global construction landscape is undergoing a fundamental transformation, driven by demands for durability, sustainability, and cost-efficient reinforcement solutions. At the forefront of this shift is the Synthetic Concrete Fibers Market, a sector poised to redefine how infrastructure and buildings are reinforced against cracking and structural stress. As we move through 2026, enterprise decision-makers require more than just high-level growth figures; they need granular intelligence on competitive positioning, supply chain volatility, and application-specific adoption rates.
PW Consulting has released a comprehensive market research study designed to serve as a strategic compass for stakeholders navigating this evolving terrain. This article provides a preview of the key dynamics, competitive forces, and market trajectories shaping the industry, while highlighting the critical intelligence contained within the full report.
Market Trajectory and Strategic Context
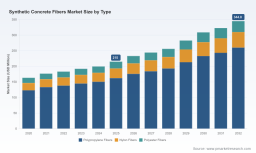
The Synthetic Concrete Fibers Market has demonstrated resilient growth over the past half-decade, reflecting a broader industry move away from traditional steel reinforcement toward advanced polymer-based solutions. According to our analysis, the global market revenue reached approximately USD 215.0 Million in 2025. This figure represents a significant expansion from the 2020 baseline, underscoring the accelerating adoption of synthetic fibers in concrete mixes.
Looking ahead, the growth trajectory remains robust. Our forecasts indicate that the market size will continue to expand through the end of the decade, surpassing the USD 300 Million mark by 2030 and reaching an estimated USD 344.8 Million by 2032. This projection is underpinned by a Compound Annual Growth Rate (CAGR) of 6.5 percent during the forecast period from 2026 to 2032.
For strategists, these numbers signify more than just volume; they represent a maturing market where differentiation becomes key. The consistent upward trend suggests that synthetic fibers are no longer a niche alternative but a mainstream standard in specific high-performance applications. However, capturing this growth requires understanding where the value lies across different product types, end-use sectors, and geographies.
Key Segments and Value Pools
The market is characterized by distinct segmentation across product types, applications, and regions. While the overall market expands, the distribution of revenue across these segments reveals where the immediate opportunities and challenges reside.
Product Type Dynamics
Polypropylene Fibers currently dominate the revenue landscape, accounting for the largest share of the market. This dominance is driven by the material's cost-effectiveness and widespread availability for general crack control and secondary reinforcement. However, the market is not monolithic. Nylon Fibers and Polyester Fibers maintain significant presence, catering to specialized applications where specific mechanical properties, such as higher impact resistance or specific tensile strengths, are required.
The strategic implication for manufacturers is clear: while polypropylene offers volume, innovation in nylon and polyester blends may offer higher margins in niche sectors. Understanding the price elasticity and performance trade-offs between these material types is critical for product portfolio strategy.
Application-Led Growth
In terms of end-use, Industrial Flooring stands out as the primary revenue contributor. The demanding nature of industrial environments, which require floors capable withstanding heavy loads, abrasion, and chemical exposure, makes synthetic fiber reinforcement indispensable. This segment is expected to continue driving volume as warehousing, logistics hubs, and heavy manufacturing facilities expand globally.
Conversely, Residential and Commercial Building applications represent a substantial but distinct opportunity. Here, the value proposition often centers on labor savings, reduced concrete shrinkage, and improved surface quality. Other Applications, including precast and specialized infrastructure, round out the demand profile. A deep dive into these segments reveals varying adoption barriers and procurement cycles that differ significantly from industrial use cases.
Regional Shifts
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America and Asia Pacific currently represent the largest regional markets, reflecting strong construction activity and infrastructure investment in these areas. Europe follows as a mature market with a strong emphasis on sustainable construction practices that favor synthetic reinforcement.
Synthetic Concrete Fibers Market
Emerging regions in Latin America and the Middle East and Africa are witnessing increasing uptake, driven by infrastructure development projects. However, the regulatory environments and supply chain maturity in these regions vary widely, necessitating localized strategies that our report details extensively.
Competitive Landscape and Strategic Consolidation
The market structure is moderately fragmented, though key players are increasingly leveraging scale and technological differentiation to secure market share. Our analysis indicates a competitive environment where concentration levels are evolving. The top three companies hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This suggests that while large incumbents hold significant sway, there is ample room for specialized players and regional leaders to thrive.
Several key companies define the competitive boundaries of this market. Sika AG, headquartered in Baar, Switzerland, remains a formidable force with its SikaFiber® and FiberSave™ product lines. Their strategy focuses on replacing steel reinforcement in slabs, industrial flooring, and precast applications, leveraging a strong global distribution network. Sika's recent capacity expansion at its Tennessee plant in the United States, announced in June 2025, highlights the strategic priority given to industrial flooring and mining applications, as well as the push toward sustainable construction.
MAPEI S.p.A., based in Milan, Italy, competes strongly with its Mapefibre® line. Their offerings, including the ST 42 blend of polypropylene and polyethylene resins, target crack control and steel replacement, positioning them as a go-to for technical concrete solutions. Similarly, Euclid Chemical Company, operating out of Cleveland, Ohio, has carved a niche with its patented TUF-STRAND SF polypropylene/polyethylene macro synthetic fiber. Euclid's focus on replacing welded wire mesh and steel in floors and industrial applications was recently reinforced through a partnership with Terminal Ready Mix and Rudolph Libbe Group in May 2025, supplying fibers for a major auto manufacturing plant in Ohio.
FORTA Corporation, based in Huntingdon Valley, Pennsylvania, offers a dual strategy with FORTA-FERRO® macro fibers for impact resistance and steel replacement, alongside micro and monofilament fibers for plastic shrinkage crack control. GCP Applied Technologies Inc., from Cambridge, Massachusetts, continues to innovate with its STRUX® 90/40 and BT50 synthetic macrofibers. Their update in September 2024, launching version 2.0 of the STRUX mobile app with enhanced cost analysis tools, demonstrates a focus on digital integration and user support to drive adoption.
The landscape also includes agile players such as BarChip Inc. in Houston, Texas, which provides CE-certified high-performance fibers for global infrastructure projects. Fabpro Polymers, a division of Great Lakes Polymer Technologies, specializes in high-performance macro and micro types for construction. Polyfibers® operates with a global manufacturer presence, offering full lines with technical support. Mighty Shield Sdn Bhd in Malaysia contributes with Dunamis™ fibers for shotcrete and pavement applications. Adfil in Spain targets floors, precast, and tunneling, while Belgian Fibers in Belgium rounds out the list with macro and micro reinforcement solutions.
The strategic takeaway for competitors and new entrants is that success relies on a combination of product performance, technical support, and regional presence. Partnerships with ready-mix suppliers and contractors, as seen in recent developments, are becoming standard tactics for market penetration.
Supply Chain Volatility and Raw Material Dynamics
A critical layer of complexity in the Synthetic Concrete Fibers Market is the volatility of raw material costs, particularly polypropylene. As the primary feedstock for the dominant fiber type, polypropylene price fluctuations directly impact margin structures and pricing strategies.
Recent industry data highlights significant volatility. As of April 2026, polypropylene prices rose by approximately 34 percent year-to-date, reaching regional benchmarks of USD 1.43/kg in Northeast Asia, USD 1.52/kg in North America, and USD 2.53/kg in Europe. By May 2026, prices in Northeast Asia stood at 1.43 USD/kg, up 16.3 percent from the prior period, supported by stable supply from propylene monomer feedstock. In North America, prices reached US$1.48/kg in May 2026, up 6.5 percent from the previous period, while European prices stood at US$2.46/kg in April 2026, up 9.3 percent year-to-date.
More recent data from June 2026 shows a slight easing, with Polypropylene benchmark prices falling to 8696 CNY/T, down 0.54 percent day-over-day and 2.39 percent over the past month. However, this remained 24.53 percent higher than one year prior. This persistent elevation in raw material costs underscores the importance of supply chain resilience. Companies must navigate these cost pressures through strategic sourcing, hedging, or value engineering to maintain competitiveness.
The disparity in regional pricing also presents arbitrage opportunities and challenges. Manufacturers operating across multiple regions must account for these cost differentials when planning production allocation and pricing strategies. The full report provides a detailed analysis of how these raw material dynamics intersect with regional demand and competitive pricing.
Content Overview: What the Research Delivers
To support data-driven decision-making in 2026, the PW Consulting Synthetic Concrete Fibers Market report offers a granular examination of the industry. The research is structured to provide actionable intelligence across multiple dimensions, enabling stakeholders to formulate robust strategies.
The report encompasses a comprehensive analysis of market size and growth projections, segmented by type, application, and region. It goes beyond aggregate numbers to explore the drivers, restraints, and opportunities within each segment. Readers will find detailed profiles of key companies, including their product offerings, strategic initiatives, and recent developments. The competitive landscape analysis includes market concentration metrics and an assessment of the strategies employed by leading players to gain advantage.
Furthermore, the study delves into the supply chain dynamics, examining raw material trends, production capacities, and distribution channels. The integration of recent industry events, such as capacity expansions, partnerships, and product launches, provides a real-time view of market momentum. This context is essential for anticipating shifts in supply availability and competitive intensity.
The research also addresses the macroeconomic and regulatory factors influencing the market. Construction trends, sustainability mandates, and infrastructure investment plans are analyzed to forecast how they will shape demand over the forecast period. By connecting these external factors to market mechanics, the report helps stakeholders align their strategies with broader industry currents.
Concrete Fiber Market
Strategic Imperatives for 2026
As the market matures, several strategic imperatives emerge for companies operating in the Synthetic Concrete Fibers Market. First, product differentiation is becoming increasingly important. While cost remains a factor, the ability to demonstrate superior performance in specific applications, such as industrial flooring or high-stress infrastructure, can command premium positioning.
Second, supply chain agility is paramount. Given the volatility in polypropylene prices and regional cost disparities, companies must build resilient supply networks. This may involve diversifying sourcing, investing in local production capabilities, or developing long-term contracts that mitigate price risk. The capacity expansion by Sika in the US serves as a prime example of proactive supply chain management to meet regional demand.
Third, strategic partnerships and ecosystem integration are key growth levers. Collaborations with ready-mix producers, contractors, and engineering firms can accelerate adoption and lock in demand. The partnership between Euclid Chemical and major construction groups for an auto plant highlights the value of aligning with large-scale projects. Additionally, digital tools, like GCP's updated mobile app, enhance customer engagement and provide value-added services that support adoption.
Fourth, geographic expansion requires careful localization. While North America and Asia Pacific offer substantial volume, emerging regions present growth opportunities that require tailored approaches. Understanding local regulatory standards, construction practices, and price sensitivities is essential for successful market entry or expansion.
Conclusion
The Synthetic Concrete Fibers Market stands at a pivotal juncture in 2026. With a projected CAGR of 6.5 percent and a market value expected to reach USD 344.8 Million by 2032, the sector offers significant opportunities for growth. However, realizing this potential requires navigating a complex landscape of competitive dynamics, raw material volatility, and diverse application needs.
PW Consulting's comprehensive market research provides the depth and precision needed to make informed strategic decisions. From detailed segmentation analysis to competitive profiling and supply chain insights, the report equips stakeholders with the intelligence required to capitalize on market trends and mitigate risks.
To access the full scope of data, forecasts, and strategic recommendations, we invite you to explore the complete market research report. The detailed findings contained within will empower your organization to navigate the synthetic concrete fibers market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Synthetic Concrete Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


