



PW Consulting Copper Strips Market Hits $126.6M in 2025; 5.24% CAGR Drives $180M Projection by 2032

Strategic Intelligence for the Copper Strips Market: Navigating Growth, Volatility, and Competitive Shifts in 2026
The global copper strips market stands at a critical inflection point. As industries accelerate electrification, expand automotive connectivity, and modernize electrical infrastructure, demand for high-performance rolled copper products has evolved from a cyclical commodity play into a strategically indispensable component of next-generation manufacturing. For executives, procurement leaders, and strategy teams, understanding where this market is headed—and why—requires more than headline metrics. It demands a structured, forward-looking view of valuation pathways, regional demand architectures, application drivers, and the competitive maneuvers reshaping supply chains.
Our latest Copper Strips Market research delivers precisely that perspective. Spanning historical analysis from 2020 through 2025 and extending with a detailed forecast horizon through 2032, the study is engineered to translate complex market signals into actionable decision frameworks. This overview highlights the strategic rationale behind the report, the operational intelligence it contains, and the market dynamics that will define competitive positioning throughout the remainder of the decade.
Why This Research Matters for 2026 Decision-Making
The copper strips sector is no longer governed by simple supply-demand equilibriums. Price volatility, regulatory interventions, midstream margin compression, and rapid product innovation are converging to redefine how manufacturers, distributors, and end-users plan capacity, negotiate contracts, and allocate capital. In this environment, strategic foresight is not optional—it is a competitive necessity.
Examining the market trajectory from a base year of 2025, the sector has demonstrated consistent expansion, with revenue scaling from approximately 102.45 million USD in 2020 to an estimated 126.6 million USD in 2025. Projections indicate continued momentum, with the market expected to reach 136.64 million USD in 2026 and advance toward 180.0 million USD by 2032. This growth trajectory is underpinned by a forecast CAGR of 5.24 percent, reflecting sustained industrial adoption and incremental push from high-growth applications.
For leadership teams, these figures are more than historical snapshots. They represent baseline scenarios that must be stress-tested against pricing shocks, regional demand reallocation, and technology-driven specification changes. The research is designed to help decision-makers answer critical questions: How should procurement strategies adapt to fluctuating input costs? Which end-use segments will drive volume versus value growth? Where do competitive threats and partnership opportunities emerge as capacity expands across key manufacturing hubs? By mapping these dimensions systematically, the report equips organizations with the analytical rigor needed to build resilient, forward-aligned strategies.
Market Architecture: Segmentation, Growth Drivers, and Structural Shifts
The market’s expansion is not uniform across regions or applications. Instead, it reflects a layered architecture where mature industrial economies, rapidly industrializing regions, and specialized high-performance verticals each contribute distinct demand profiles. Understanding these layers is essential for accurate forecasting, capacity planning, and go-to-market prioritization.
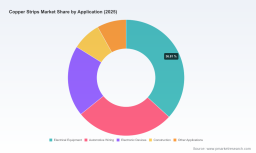
Demand concentration is particularly pronounced across core application categories. Electrical equipment and automotive wiring represent dominant consumption channels, while electronic devices, construction, and diversified industrial uses contribute additional layers of volume and specification complexity. At the end-use level, automotive and electrical segments anchor a substantial share of demand, with electronics reinforcing growth through miniaturization, thermal management, and connectivity requirements. The interplay between these segments shapes pricing dynamics, alloy selection, gauge diversification, and supply chain reliability expectations.
Regional demand patterns further illustrate the market’s evolving structure. Asia Pacific continues to command a leading share of consumption, driven by manufacturing intensity, infrastructure investment, and expanding electrical and automotive production ecosystems. North America and Europe maintain strong industrial baselines, supported by mature electrical grids, vehicle production networks, and ongoing modernization programs. Latin America and the Middle East and Africa contribute incremental but strategically relevant growth, often tied to specific industrial corridors, energy projects, and localized supply chain development.
This segmentation complexity matters because competitive positioning is rarely about total market size alone. It is about where value is captured, which specifications command premium margins, and how regional sourcing strategies interact with trade policy, logistics constraints, and customer qualification cycles. The report dissects these relationships in detail, enabling users to isolate the segments most aligned with their operational strengths and growth objectives.
Competitive Landscape: Leading Players and Strategic Maneuvers
The copper strips market is characterized by a moderately concentrated competitive structure, with a handful of established producers shaping pricing norms, technological benchmarks, and regional supply reliability. Market concentration metrics indicate that the top three firms account for approximately 35.2 percent of industry revenue, while the top five extend their combined share to roughly 52.1 percent. This distribution suggests a landscape where scale, technical capability, and vertical integration matter, yet competitive differentiation is still achievable through product specialization, service reliability, and strategic capacity deployment.
Among the leading participants, Aurubis AG stands out as a global non-ferrous metals producer and recycler whose copper strip offerings form part of a broader portfolio of rolled copper products. Its positioning reflects the increasing importance of recycled feedstock integration, material traceability, and supply continuity in a market sensitive to both cost and sustainability expectations.
KME Germany GmbH & Co. KG operates as a manufacturer of rolled copper and copper alloy semi-finished products, with strip solutions tailored for industrial applications. The company’s recent activity underscores a focus on processing depth and regional capacity reinforcement, aligning production capabilities with demand from demanding industrial customer bases.
Mitsubishi Materials Corporation brings specialized expertise in wrought copper products, including oxygen-free copper strips, multi-gauge strip configurations, and high-performance alloys designed for automotive and electronics applications. Its product strategy emphasizes material performance under thermal and mechanical stress, reflecting the broader industry shift toward higher-specification components in electrified and miniaturized systems.
Wieland-Werke AG serves as a specialist supplier of semi-finished copper and copper alloy rolled products, with dedicated strip, sheet, and plate offerings. Its market role highlights the value of application-focused engineering support, consistent quality assurance, and the ability to serve customers who require tightly controlled material properties across varied geometries.
Copper Strips Market
Worldwide Tin Plated Copper Strip Market
The competitive environment is further shaped by recent strategic moves that signal where industry leadership is being contested. In mid-2025, KME advanced its refining capabilities with the inauguration of a second refining furnace at its Osnabrück site, reinforcing processing capacity and operational flexibility in Europe. Later in the year, Mitsubishi Materials Corporation introduced a new high-strength, high-heat-resistance oxygen-free copper MOFC™-HR multi-gauge strip, designed to enable heat dissipation and contact area production using a single material platform—an innovation that illustrates how product differentiation is increasingly tied to functional performance rather than commodity volume alone. Heading into 2026, Wieland-Werke AG broke ground on a major expansion in Northwest Ohio, signaling continued investment in North American manufacturing presence and supply chain proximity.
These developments are not isolated events. They reflect an industry actively reshaping capacity, specification leadership, and regional footprint in response to demand relocation, customer qualification requirements, and margin pressures across the value chain. The report evaluates these moves within a broader competitive context, helping readers assess which strategies are likely to strengthen positioning and which may expose firms to risk if market conditions shift.
Macroeconomic and Regulatory Dynamics Shaping the Market
No market assessment is complete without addressing the external forces that influence cost structures, trade behavior, and investment timing. In the copper strips sector, recent price action and policy developments have introduced both opportunity and complexity.
Raw material dynamics have been particularly pronounced. Global copper prices reached record levels, briefly surpassing 14,500 USD per tonne in early 2026, supported by strong demand from electric vehicles, renewable energy deployment, and broader electrification trends. Quarter-over-quarter movements have been sharp, with prices rising to approximately 12,822 USD per metric tonne in the first quarter of 2026, following a notable climb from late-2025 levels. Such volatility directly affects input planning, inventory strategy, and contract structuring for downstream manufacturers.
Regulatory and trade measures have compounded these pressures. U.S. tariffs on semi-finished copper products—while exempting refined copper—have influenced pricing behavior across traded markets, contributing to a pronounced rise in benchmark contract values over the course of 2025 and into 2026. At the same time, smelter treatment and refining charges have reached historic lows even as headline copper prices climb, highlighting midstream margin compression and the challenges faced by processors navigating input cost inflation while operating under constrained treatment economics.
These dynamics create a dual challenge for market participants. On one hand, strong demand and elevated pricing can support revenue growth and justify capacity investment. On the other, margin pressure, trade uncertainty, and feedstock volatility can erode profitability if not managed through strategic sourcing, product mix optimization, and regional supply balancing. The research addresses these pressures directly, offering frameworks for interpreting price signals, evaluating procurement risk, and aligning capacity decisions with realistic market scenarios rather than short-term fluctuations.
What the Report Delivers: Practical Intelligence for Execution
Beyond macro analysis and competitive profiling, the study is built around operational usability. It provides a structured foundation for teams that need to translate market intelligence into planning assumptions, investment cases, and commercial strategies.
Key components of the report include:
- A comprehensive market size and forecast model that traces historical performance and projects future revenue pathways across the 2026 to 2032 horizon, enabling scenario planning under varying demand and pricing conditions.
- Segment-level evaluation across regions, applications, and end-use categories, allowing users to identify where demand intensity, specification requirements, and growth momentum differ.
- Competitive benchmarking and company-level analysis of leading producers, with attention to product portfolios, manufacturing focus, and recent strategic developments.
- Assessment of market concentration and structural dynamics that influence pricing power, supplier negotiation leverage, and barriers to entry.
- Contextual analysis of raw material trends, regulatory interventions, and midstream margin conditions, helping stakeholders interpret external volatility within a coherent strategic framework.
- Forward-looking discussion of the drivers likely to shape adoption, capacity deployment, and product innovation throughout the forecast period.
By combining quantitative structure with qualitative strategic interpretation, the report is designed to support a wide range of use cases: market entry evaluation, capacity justification, sourcing strategy refinement, competitive monitoring, and long-range planning. Each section is oriented toward reducing ambiguity and improving decision quality in an environment where assumptions must be tested against evidence.
Conclusion: Position Your Strategy Ahead of the Next Cycle
The copper strips market is being shaped by a rare combination of structural demand growth, material price volatility, regulatory disruption, and rapid product-level innovation. Organizations that rely on outdated assumptions or reactive procurement habits risk misjudging both opportunity and exposure. Those that invest in rigorous, forward-looking market intelligence can align sourcing, capacity, and commercial strategy with the segments and regions where value is most likely to consolidate.
This research is intended to serve as a strategic reference point for exactly that kind of planning. It provides the market sizing, segmentation logic, competitive context, and dynamic analysis needed to make informed decisions in 2026 and beyond. To access the complete dataset, detailed segmentation evaluations, full company profiles, and the complete forecast model, visit the source page and explore the full Copper Strips Market research. In a market moving as quickly as this one, the depth of your intelligence will directly shape the quality of your next strategic move.
For detailed analysis of this topic, please visit the official page: Copper Strips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


