



PW Consulting: Metal 3D Printing Hits $1.79B in 2025, Billion-Dollar Surge Forecast to 2032

Strategic Intelligence for the Decisive Year: Why the 2026 Metal Material Based 3D Printing Market Report Is Essential for Executive Decision-Making
The Momentum Is Real, But the Path Forward Demands Precision
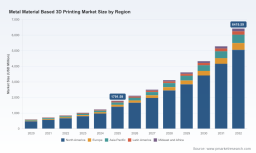
The global landscape for metal material based 3D printing has evolved from experimental prototyping to industrialized production at a pace that has caught many organizational leaders off guard. Over the past half-decade, the market has demonstrated a compounding trajectory that signals a structural shift rather than a temporary cycle. Independent industry tracking indicates that revenue expansion has consistently outpaced earlier projections, with the total market size climbing from approximately $600 million in 2020 to an estimated $1.79 billion in 2025. Looking toward the forecast window spanning 2026 through 2032, the sector is projected to sustain a compound annual growth rate of 20.0 percent, pushing the market toward a multi-billion-dollar valuation by the end of the decade.
Numbers of this magnitude attract attention, yet attention alone does not build competitive advantage. What separates organizations that capture value from those that merely watch it being created is the ability to translate macroeconomic momentum into operational clarity. Enterprise teams need to understand where capital is flowing, which material categories are commanding premium positioning, how regional procurement patterns are shifting, and which certification regimes will determine market access in the coming quarters. This is precisely the analytical gap that our latest market research addresses.
Metal 3D Printer Market
Why 2026 Represents a Binary Year for Strategic Planning
The forecast period opens in a year defined by inflection. Industrial metal additive manufacturing is moving rapidly toward full production rate operations, and the qualification requirements that accompany this transition are reshaping procurement timelines, supplier relationships, and investment priorities. Aerospace and defense organizations are increasingly demanding rigorous material validation, while medical and dental practitioners are navigating new regulatory expectations that directly affect production throughput and component traceability. The convergence of production scaling and standardization is not a theoretical concern; it is a live operational constraint that will determine which manufacturers can fulfill orders, which can maintain yield consistency, and which can secure long-term supply agreements.
At the same time, the supply chain for metal powders and master alloys is undergoing consolidation and vertical integration. Producers are expanding capacity, tightening quality control, and aligning feedstock availability with the specific requirements of laser powder bed fusion and directed energy deposition processes. Organizations that fail to map these supply-side shifts risk encountering bottlenecks precisely when their own production schedules are accelerating. The strategic question for 2026 is not whether metal additive manufacturing will continue to grow, but whether a given enterprise will be positioned upstream, midstream, or downstream of the value capture that this growth generates.
What This Market Research Delivers: Actionable Architecture, Not Static Tables
Our Metal Material Based 3D Printing Market study is built for decision-makers who need to convert industry signals into execution roadmaps. Rather than offering a retrospective summary of past shipments, the report is structured around the operational questions that procurement, engineering, finance, and corporate strategy teams face when allocating resources in a high-growth environment. The analysis spans the historical baseline from 2020 through 2025 and extends forward across the 2026 to 2032 forecast horizon, allowing readers to evaluate both the evidence of what has already occurred and the scenarios that will shape the next several years.
Metal Material Based 3D Printing Market
The report dissects the market through multiple lenses that matter to enterprise planning. Material categories are examined with attention to how different metal systems are being positioned across high-volume production and specialized applications. Application segments are assessed in the context of demand intensity, qualification demands, and the pace at which additive components are moving from prototype approval to serial production. Regional patterns are analyzed to illuminate where demand is concentrating, where supply chain infrastructure is maturing, and where localized production strategies may offer advantages in responsiveness or cost structure. Throughout the analysis, the study tracks how market concentration is evolving among leading participants, offering context for partnership strategy, procurement negotiation, and competitive positioning.
Equally important, the report integrates the regulatory and standards environment that increasingly governs market access. As process validation requirements tighten and certification frameworks such as ISO standards and Nadcap credentials become prerequisites for participation in high-stakes applications, organizations need a clear understanding of the compliance trajectory and its implications for production readiness. The research does not treat regulation as a sidebar; it embeds regulatory dynamics into the competitive analysis so that readers can anticipate where qualification lead times will extend, where supplier consolidation may affect material availability, and where early compliance investment can create durable barriers to entry for less-prepared rivals.
Competitive Intensity and the Emerging Order of the Market
The company landscape reflects both the maturity of established equipment and materials providers and the velocity of recent strategic moves. Participants with headquarters across Europe and North America are competing on multiple fronts: system reliability, build volume scalability, material breadth, software integration, and the ability to support customers through qualification cycles. Manufacturers of laser powder bed fusion platforms continue to expand their materials portfolios and system configurations, while electron beam melting specialists are reinforcing their presence in high-performance alloy segments. Alongside the equipment makers, powder and alloy suppliers are deepening their engagement with end users, often through technical collaboration that ties feedstock development to application-specific performance requirements.
Recent activity among key players underscores how rapidly the competitive environment is shifting. In late 2025, one major system manufacturer introduced an expanded set of metal additive materials optimized for laser powder bed fusion, broadening the material ecosystem available to production users. Around the same period, a separate equipment provider secured a notable order tied to naval applications, reinforcing how defense-driven requirements are pushing manufacturers to develop first-of-their-kind process capabilities in specialized alloys. By early 2026, additional strategic moves included facility investment aimed at improving regional production capacity and delivery speed, as well as the launch of next-generation data preparation software intended to streamline industrial metal additive workflows. These are not isolated announcements; they are indicators of a market in which equipment availability, material access, and software-driven process efficiency are becoming tightly intertwined competitive differentiators.
For enterprise strategists, the practical implication is clear. Sourcing decisions can no longer be evaluated solely on machine price or material cost per kilogram. They must account for the pace at which a supplier can support qualification, the robustness of its materials portfolio against evolving application requirements, the geographic proximity of its production and support infrastructure, and the degree to which its software environment reduces the friction between design intent and finished part. The companies that will prevail in 2026 and beyond are those that treat these dimensions as an integrated value proposition rather than a collection of separate features.
How the Findings Translate into 2026 Decisions
Market research becomes valuable only when it changes behavior. In the context of metal material based 3D printing, the strategic stakes in 2026 fall into several actionable categories:
- Capital allocation for production capability must be aligned with the segments where qualification momentum is strongest and where serial production is already transitioning from pilot scale to repeat manufacturing.
- Procurement strategies need to reflect the consolidation occurring in metal powder and master alloy supply chains, including the trade-offs between single-source dependency and the stability that comes from deeper supplier integration.
- Engineering and quality organizations should map the incoming standards and certification environment against current process validation capabilities, identifying gaps that could delay customer acceptance or restrict participation in high-value programs.
- Partnership and vendor selection should be informed by a realistic assessment of who can support scale-up without sacrificing material consistency, documentation rigor, and process repeatability.
- Geographic expansion or sourcing shifts should be evaluated in light of where demand is intensifying and where local supply chain responsiveness can reduce lead times or mitigate logistical risk.
Our report provides the structural clarity required to make these judgments with greater confidence. It offers the comparative context needed to distinguish transient market noise from durable demand shifts, and it presents the segmentation logic that allows an organization to identify where its own capabilities intersect with the most promising commercial pathways. Readers will gain a sharper sense of which applications are moving fastest toward production normalization, which material families are anchoring value in high-performance sectors, and how the broader competitive field is organizing itself around platform reliability, material qualification, and software-enabled throughput.
What Is Reserved for the Full Report
Depth matters, and disciplined intelligence requires that some of the most decision-relevant figures be delivered in their complete form rather than summarized in a preview. The full market research contains the detailed segmentation values, the precise regional and application-level revenue breakdowns, the material-category projections, and the company-level competitive assessments that executives need for board-level discussion, budget defense, and investment justification. Those specifics are not blunt instruments; they are calibrated to support scenario planning, sensitivity analysis, and cross-functional alignment. Releasing them in isolation would undercut the analytical context that makes them useful.
The complete study also includes the methodology, the historical reconstruction, the forecast assumptions, and the supporting evidence that connect raw market size figures to the operational dynamics shaping customer behavior. It explains how concentration patterns are evolving, how qualification and certification requirements are influencing adoption curves, and how equipment and materials suppliers are positioning themselves relative to one another as the industry moves from expansion to execution.
The Strategic Imperative for 2026
The trajectory of metal material based 3D printing is no longer a matter of speculation. The market has crossed the threshold from early adoption into a phase dominated by production scaling, standardization, and competitive differentiation based on process maturity. With a forecast compound annual growth rate of 20.0 percent over the 2026 to 2032 period and a market size anticipated to expand well beyond the $6 billion mark by 2032, the opportunity is substantial, but the window to align organization, supply chain, and compliance posture is narrowing.
Enterprise leaders who approach this environment with generic market narratives will find themselves making decisions in the dark. Those who ground their choices in rigorous segmentation, competitive intelligence, regulatory mapping, and scenario-aware forecasting will be better positioned to secure supply, win qualification-heavy contracts, and deploy capability where the returns are most decisive. Our Metal Material Based 3D Printing Market research is designed to make that alignment possible. The full report is the instrument for doing the work that 2026 demands, and it is available now for teams that are ready to convert momentum into strategy.
For detailed analysis of this topic, please visit the official page: Metal Material Based 3D Printing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


