



PW Consulting: Capsule Filling Machines Market to Reach $344.8M by 2032 at 6.98% CAGR

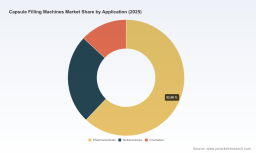
Strategic Intelligence Brief: Capsule Filling Machines Market 2026–2032
Executive Overview
The global capsule filling machines market stands at a critical inflection point as manufacturers navigate tightening regulatory frameworks, evolving product formats, and intensifying capacity demands across pharmaceutical, nutraceutical, and cosmetic sectors. Our latest market research delivers a comprehensive, forward-looking intelligence framework designed specifically for executive decision-makers, procurement leaders, and business development strategists operating within the 2026–2032 forecast horizon.
Drawing on a rigorous historical analysis spanning 2020 through 2025, the study establishes a clear trajectory of sustained expansion. The market has consistently demonstrated resilient growth, with the base year valuation reflecting steady industrial adoption and cross-sector formulation complexity. As we project forward, the forecast period captures a measured but unmistakable acceleration, anchored by a compound annual growth rate of 6.98 percent. By 2032, the sector is positioned to reach a substantially elevated revenue threshold, underscoring the strategic imperative for stakeholders who must align capital expenditure, technology procurement, and regional deployment strategies with verifiable market signals rather than speculative assumptions.
This research is crafted as a decision-enabling instrument. It translates macro-level momentum into actionable intelligence, mapping the structural forces that will define competitive positioning, supply chain resilience, and operational scalability throughout the remainder of the decade.
Market Dynamics & Regulatory Architecture
Regulatory compliance has evolved from a baseline operational requirement to a central driver of equipment specification, vendor selection, and facility design. Pharmaceutical manufacturers continue to operate under stringent current Good Manufacturing Practice mandates that dictate sanitary design, routine calibration protocols, inspection schedules, and maintenance rigor. Dietary supplement and nutraceutical formulators face parallel expectations, with quality management and food safety certifications now serving as non-negotiable prerequisites for market access. Equipment suppliers must demonstrate conformance across multiple certification standards to maintain eligibility for regulated production environments, and procurement teams increasingly evaluate vendor documentation as a primary filter before technical evaluation begins.
Beyond product-grade regulations, equipment transactions themselves are shaped by compliance reporting obligations that affect cross-border procurement cycles, import-export workflows, and domestic supply arrangements. Electronic reporting requirements for specific equipment categories have matured into standardized administrative processes that procurement and logistics teams must integrate into their acquisition timelines. Equipment safety, operator protection, and sanitation protocols further dictate facility layout considerations, environmental controls, and validation workflows. The cumulative effect is a procurement environment where regulatory readiness directly influences total cost of ownership, deployment speed, and long-term operational continuity.
Simultaneously, market concentration remains relatively moderate, indicating a fragmented but actively consolidating competitive field. This structure rewards organizations that can differentiate through dosing precision, format versatility, validation support, and service responsiveness. The research examines how these dynamics shape purchasing behavior, upgrade cycles, and strategic partnerships across production scales, from high-throughput commercial lines to specialized multi-format operations.
Segmentation Intelligence & Structural Shifts
The market is defined by three interrelated segmentation dimensions that collectively determine equipment performance requirements, capital allocation patterns, and end-use deployment logic. The research deconstructs each dimension to reveal how purchasing priorities are shifting and where hidden risk or opportunity may reside.
Equipment Type Architecture
The type-based breakdown captures the balance between fully automated throughput systems, semi-automated hybrid configurations, and manual-scale units. As formulation complexity increases and batch variability demands tighter control, procurement decisions are increasingly influenced by throughput targets, changeover flexibility, and integration with downstream packaging and quality control workflows. The study analyzes how these type-level preferences differ across production volumes and how manufacturers evaluate automation roadmaps relative to labor constraints, validation burdens, and aggregation of multiple fill formats within a single line.
Application-Driven Demand Patterns
Demand across pharmaceutical, nutraceutical, and cosmetic applications continues to diverge in terms of speed, precision tolerance, material compatibility, and compliance documentation. Pharmaceutical applications remain the most demanding in terms of validation, repeatability, and regulatory traceability. Nutraceutical and supplement production has expanded the relevance of formats that support powders, pellets, tablets, mini-tablets, and multi-fill configurations. Cosmetic applications increasingly intersect with broader encapsulation requirements, bringing additional material-handling considerations into equipment selection. The report examines how these application-specific requirements influence technology roadmaps and how manufacturers position their equipment portfolios to capture cross-application demand without compromising compliance or throughput.
Regional Growth Architecture
Regional analysis within the study reveals how geographic demand concentration, manufacturing footprints, and regulatory environments shape deployment strategies. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region each present distinct procurement rhythms, capacity expansion priorities, and localization considerations. The research maps these regional dynamics to help stakeholders anticipate where demand is intensifying, where competitive pressure is building, and where supply chain alignment may require localized service, support, or sourcing strategies. Detailed regional valuations and split-level figures are reserved for the full dataset, where they are presented with the granularity required for territory-specific planning.
Competitive Landscape & Strategic Positioning
The competitive environment is shaped by a diverse set of global and regional manufacturers, each emphasizing distinct technological strengths, compliance credentials, and application coverage. The research profiles leading participants and evaluates how their equipment families, product launches, and market messaging align with prevailing buyer priorities.
Syntegon Technology continues to emphasize high-volume pharmaceutical and nutraceutical production through precision dosing and throughput-oriented capsule filling platforms, reinforcing its positioning for large-scale, validated production environments. IMA Group maintains a strong presence with rotary and suction bowl systems engineered for advanced dosing flexibility and high-speed operation, appealing to manufacturers seeking throughput maximization with adjustable fill control. MG2 S.r.l. has expanded its relevance through multi-format support spanning powders, pellets, tablets, mini-tablets, and capsule-in-capsule applications, while maintaining strong compliance alignment for regulated markets. ACG Worldwide focuses on integrated solutions that prioritize simplicity, safety, and efficiency for pharmaceutical and nutraceutical use, targeting operational reliability and deployment practicality. Harro Höfliger Verpackungsmaschinen GmbH addresses high-efficiency pharmaceutical production lines with integrated capsule filling and packaging system perspectives, supporting end-to-end line optimization. Qualicaps Co., Ltd. provides encapsulation technology solutions for global pharmaceutical manufacturers, reinforcing the importance of technical partnership and application-specific engineering. Torpac Inc. and Index Capsule Fillers continue to serve pharmaceutical and nutraceutical segments with equipment and service offerings that emphasize regional availability and operational support. Capsugel, operating under the Lonza Group, contributes specialized expertise in hard capsule filling and drug delivery-focused encapsulation systems. Dott Bonapace reinforces the automatic capsule filling segment for pharmaceutical and supplement production with dedicated machine families. Finetech Pharmaceutical Equipment and Feton International Ltd. represent important contributions from Asian manufacturing bases, with Finetech advancing semi-automatic and hybrid-automation configurations and Feton covering both industrial and laboratory-scale capsule filling equipment for pharmaceuticals and supplements.
Recent product activity underscores the speed at which vendor portfolios are evolving. Finetech Pharmaceutical Equipment introduced new technology for its NJP-1200 capsule filling equipment to improve precision and efficiency in pharmaceutical manufacturing. MG2 S.r.l. launched the Experta model within its E Series, emphasizing human-centered design, advanced dosing combinations, and weight control systems. MG2 also debuted the IN-CAP SE automatic capsule filling machine at a major trade fair, highlighting support for multiple fill types with strong compliance alignment and practical throughput characteristics for targeted application segments. These developments illustrate how vendors are responding to demand for controlled weight consistency, format versatility, operator ergonomics, and faster integration into modern production environments.
The report situates these company-level movements within a broader competitive framework, allowing readers to assess where differentiation is emerging, where service and validation capabilities may become deciding factors, and how vendor concentration may shift over the forecast period.
Report Architecture & Decision Utility
This market research is structured to support both strategic planning and operational execution. The study integrates historical performance analysis, forward-looking forecasts, segmentation evaluation, competitive profiling, regulatory context, and recent market developments into a unified intelligence package. Readers will find detailed coverage of market sizing across the historical window and forecast horizon, equipment type distributions, application-level demand behavior, and regional deployment patterns. The report also maps the competitive field through company profiles, recent product activity, and strategic positioning analysis, enabling procurement and business development teams to benchmark vendor options against operational requirements.
Capsule Filling Equipment Market
Beyond quantitative coverage, the research provides interpretive frameworks for evaluating equipment selection criteria, compliance readiness, total cost of ownership considerations, and deployment risk. It examines how automation adoption interacts with validation demands, how format flexibility influences multi-product operations, and how regional demand variations shape sourcing and service strategies. The analysis is designed to support capital planning, vendor shortlisting, regional expansion decisions, and technology roadmap development across pharmaceutical, nutraceutical, and cosmetic manufacturing organizations.
Strategic Implications for 2026 Decision-Makers
For leaders making capital allocation, procurement, and expansion decisions in 2026, the market research offers several strategic advantages. First, it converts broad growth momentum into structured evidence that can support internal business cases and investment approvals. Second, it clarifies how regulatory expectations now influence not only product manufacturing but also equipment acquisition, documentation, and long-term compliance sustainability. Third, it reveals how vendor innovation is reshaping buyer expectations around dosing control, format versatility, line integration, and operational ergonomics. Fourth, it provides a competitive map that helps organizations anticipate supplier differentiation strategies and evaluate where service, support, and validation capabilities may become decisive in multi-vendor evaluations.
The research is particularly relevant for manufacturers planning capacity upgrades, multi-format expansion, compliance hardening, or regional sourcing shifts. It also supports suppliers and investors seeking to understand where demand intensity, technology differentiation, and competitive pressure are likely to converge over the next several years.
Conclusion
The capsule filling machines market is advancing through a period defined by regulatory rigor, format diversification, and sustained demand expansion. Organizations that approach procurement and strategy with granular, forward-looking intelligence will be better positioned to manage compliance exposure, optimize throughput, and align equipment investments with long-term production objectives. This report delivers the analytical depth required to make those decisions with confidence.
Capsule Filling Machines Market
For complete market sizing, segmentation breakdowns, company-level assessments, regulatory mappings, and forecast tables, please access the full study on the PW Consulting research portal. Detailed quantitative data and comprehensive segmentation splits are available in the complete report.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


