



P.W. Consulting Reveals Feminine Care Sanitary Napkin Market to Reach $344.8M by 2032, 6.98% CAGR

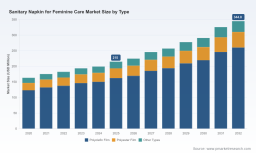
Strategic Intelligence for the Sanitary Napkin for Feminine Care Market Through 2032
The global feminine hygiene sector stands at a critical inflection point. As consumer expectations evolve and regulatory frameworks mature, decision-makers require more than headline figures. They need a structured, evidence-based view of how the sanitary napkin for feminine care market will compound, where competitive pressure will concentrate, and which operational capabilities will separate resilient players from the rest. The newly released PW Consulting market study translates a decade of historical performance and a seven-year forward trajectory into a decision-ready toolkit for 2026 strategy planning.
This overview outlines the analytical architecture of the report, demonstrates how the macro trajectory anchors strategic planning, and previews the competitive and regulatory dimensions that will shape portfolio choices, manufacturing footprints, and go-to-market investments. Detailed segment valuations, regional breakdowns, and company-level scenario models are reserved for the full dataset, ensuring that executives who engage with the complete study gain exclusive access to the full intelligence stack.
Market Trajectory and the Strategic Baseline for 2026
The sanitary napkin for feminine care market has navigated a clear growth corridor over the past half-decade. Historical tracking from 2020 through 2025 shows a steady climb in absolute revenue, reflecting sustained demand, incremental product innovation, and broader distribution penetration across mature and emerging channels. This historical arc establishes the baseline against which forward-looking assumptions are stress-tested in the forecast window extending to 2032.
The forward trajectory projects continued expansion at a compound annual growth rate of 6.98 percent across the forecast period. Such a rate signals more than incremental volume accumulation; it points to structural tailwinds that reward companies able to align product architecture, supply chain agility, and compliance readiness with shifting consumer preferences. For 2026 planning teams, the key implication is that growth will not accrue uniformly. Revenue will concentrate around specific value propositions, manufacturing capabilities, and regional execution quality, making segmentation intelligence indispensable for capital allocation.
PW Consulting’s analysis converts this trajectory into a planning framework. Instead of treating the forecast as a single line item, the study maps how different product architectures, application contexts, and operational models contribute to the cumulative outcome. This approach allows leadership teams to test sensitivity around pricing, mix shifts, capacity utilization, and regulatory compliance costs without relying on blunt averages. The result is a clearer picture of where margin potential exists and where execution risk is most likely to erode returns.
Because the market’s expansion is coupled with tightening oversight and intensifying brand competition, the strategic question for 2026 is no longer whether the sector will grow, but how to position within that growth. The report is built to answer that question through disciplined segmentation, competitive benchmarking, and scenario planning that can be operationalized across commercial, procurement, and regulatory functions.
What the Report Delivers: Architecture of Actionable Intelligence
A market study earns its place in the executive workflow only when it converts data into decisions. The PW Consulting report is organized around practical deliverables that support strategy formulation, investment prioritization, and risk management. The content is designed to be referenced directly in planning cycles rather than read once and shelved.
Core Analytical Components
- Historical market reconstruction that ties observed performance from 2020 to 2025 to the assumptions driving the forecast through 2032
- Segment-level assessment of product-type dynamics and application contexts, enabling a precise reading of where demand intensity and competitive overlap are highest
- Market concentration analysis that quantifies how revenue is distributed across leading players and what that implies for entry barriers, pricing power, and partnership strategy
- Competitive profiling of key enterprises, including headquarters positioning, brand portfolios, and recent strategic moves that signal future capability builds
- Regulatory and standards monitoring that tracks classification, testing expectations, labeling guidance, quality management alignment, and emerging global standardization activity
- Scenario-ready framing that lets teams evaluate how shifts in compliance cost, raw material strategy, channel mix, and brand positioning could alter outcomes within the forecast horizon
Each component is interlinked. Historical performance informs segment assumptions; segment dynamics clarify competitive positioning; competitive positioning shapes partnership and private-label decisions; and regulatory trajectory defines the compliance ceiling that every manufacturer must accommodate. By presenting these layers together, the report gives executives a coherent map rather than isolated data points.
Importantly, the study preserves analytical rigor without overwhelming the reader with raw tables. Narrative interpretation accompanies the numbers so that teams can understand not only what the figures are, but why they matter and how they should influence resource allocation. For confidentiality and commercial focus, granular regional shares and application-level monetary splits are disclosed in the full report, ensuring that subscribers receive the depth required for precise planning while this overview maintains the strategic preview format.
Competitive Landscape: Convergence, Differentiation, and Strategic Moves
The sanitary napkin for feminine care market is shaped by a mix of global multinationals, regional specialists, and manufacturing partners serving private-label and OEM/ODM channels. The competitive field reflects differing strategic priorities: some companies compete through brand heritage and broad distribution, others through product technology and softness claims, and still others through cost-efficient manufacturing and regulatory readiness for specific markets.
Key Enterprise Positioning
- Kimberly-Clark Corporation, based in Irving, Texas, maintains a prominent brand presence through Kotex sanitary napkins and panty liners, with distribution and partnership activity that extends into essential-care initiatives
- Unicharm Corporation, headquartered in Ehime, Japan, competes through the Sofy line of sanitary napkins and panty liners, reinforcing its position in markets where comfort, fit, and consumer trust are decisive purchase drivers
- Kao Corporation, located in Tokyo, Japan, advances the Laurier brand and has emphasized product refinements aimed at improving softness and breathability, aligning innovation with everyday usage expectations
- Hengan International Group Company Limited, operating from Jiangxi, China, manages brands such as Space7 and Anerle, reflecting a portfolio approach that targets value-conscious and mid-tier consumer segments
- Family Cares Group, based in Fujian, China, produces Ecolivia sanitary napkins and maintains quality-system and registration credentials that support traceability and compliance-oriented positioning
- Premier Care Industries, headquartered in Winnipeg, Manitoba, Canada, manufactures sanitary napkins and liners under the Bodyform brand for private-label and national-equivalent channels, highlighting the strategic role of contract and brand-transfer models
- Ontex Group NV, based in Aalst, Belgium, participates across feminine hygiene sanitary napkins and liners, with a footprint that supports multi-market execution and product range breadth
- Haoyue Personal Care Co., Ltd., from Hangzhou, Zhejiang, China, operates in the OEM/ODM space, serving as a manufacturing partner for brands that require flexible production and specification customization
The competitive story is not simply a ranking of scale. It is a study in how companies allocate effort across brand building, product engineering, channel access, and manufacturing efficiency. In this market, a player with strong brand recognition may still face pressure if regulatory expectations rise or if a competitor secures a meaningful advantage in comfort, absorbency, or cost structure. Likewise, manufacturers serving private-label and OEM/ODM customers have a different risk profile: they must align with client specifications, quality expectations, and compliance documentation while maintaining production reliability.
Recent Strategic Signals
Recent activity among leading participants illustrates how the competitive field is being shaped in real time.
- In October 2025, Kimberly-Clark Corporation expanded global partnerships with Baby2Baby, Plan International, Project HOPE, and UNICEF to advance essential care for women and girls, signaling a broader corporate commitment that intersects with brand visibility and social-impact positioning
- In April 2024, Unicharm Corporation entered a strategic partnership with Kao Corporation, a move that underscores how collaboration can reshape distribution leverage, product development velocity, and market access
- In 2024, Kao Corporation introduced advanced Ultra-Soft Technology in Laurier products, enhancing softness and breathability, an example of product-level differentiation intended to reinforce consumer preference in a crowded category
These developments matter because they show where competitors are investing attention. Partnerships can accelerate reach and credibility. Product innovations can shift purchase criteria. Regulatory and quality milestones can define who is eligible to compete in more demanding channels. The report uses these signals to build a living picture of competitive momentum rather than a static list of players.
Tampons Market
Regulatory Evolution and Quality Infrastructure as Strategic Variables
Regulatory dynamics are no longer peripheral to commercial strategy in feminine care. They influence product design, testing protocols, labeling clarity, quality management systems, and market access. For 2026 and beyond, compliance readiness is a competitive variable, not just a legal checkbox.
Classification and Testing Expectations
Sanitary napkins are classified by the FDA as Class II medical devices, and in October 2025 the agency issued draft guidance for performance testing and labeling. The guidance includes recommendations for pads to ensure safe absorption and to provide clear directions for use. This development points to an environment where substantiation, transparency, and consistent product performance are increasingly central to market acceptance.
Sanitary Napkin for Feminine Care Market
Quality Management Alignment
Effective February 2, 2026, the FDA QMSR incorporates ISO 13485:2016 into 21 CFR Part 820, extending its relevance to menstrual products including sanitary napkins. For manufacturers, this alignment raises the importance of documented quality processes, traceable controls, and system-level consistency. Companies that already operate mature quality frameworks will face a different adaptation burden than those building compliance capability from the ground up.
Certification and Standards Momentum
Standards activity is also advancing. ISO/TC 338 is developing global standards for single-use menstrual pads, including sanitary napkins, with expected completion in December 2026. In parallel, certain manufacturers maintain ISO 9001:2015 certification and FDA establishment registration credentials that support export readiness and buyer confidence. These elements collectively indicate that the market is moving toward more formalized expectations around product consistency and documentation.
Strategically, the implication is clear. Product claims, absorption performance, and user instructions will be judged against a more defined oversight environment. Supply chains, manufacturing sites, and product-development timelines must account for the time and cost of validating performance and maintaining compliant quality systems. The report integrates these regulatory currents into the forward assessment so that strategy teams can anticipate operational impact rather than react after the fact.
How to Use This Study for 2026 Decision-Making
The value of a market study lies in its deployment. For 2026 planning, the PW Consulting research is structured to support several concrete uses.
Portfolio and Product Strategy
Leadership teams can use the segmentation architecture to determine where to reinforce existing offerings, where to introduce product refinements, and where to avoid overinvestment in crowded or low-differentiation positions. The forward trajectory and segment interpretation help frame whether resources should tilt toward comfort and breathability, absorption reliability, sustainability positioning, or channel-specific packaging and sizing.
Competitive and Partnership Planning
The competitive profiles and recent moves provide a basis for assessing partnership opportunities, private-label potential, and brand-transfer dynamics. Companies evaluating collaboration can better understand which partners bring distribution strength, which bring product technology, and which bring manufacturing flexibility. This is particularly relevant in a market where OEM/ODM capabilities and national-equivalent branding both play meaningful roles.
Compliance and Operational Readiness
With evolving guidance, QMSR alignment, and international standards development, the study gives teams a structured basis for compliance planning. Product, quality, and regulatory functions can use the framework to anticipate documentation needs, testing expectations, and system updates, thereby reducing the risk of late-stage remediation.
Scenario and Investment Planning
Because the forecast spans to 2032, executives can test investment horizons against multiple assumptions. Capacity expansion, geographic focus, brand investment, and compliance spending can all be evaluated in the context of a compounding market trajectory rather than a single-year snapshot. That longer lens helps distinguish short-lived opportunities from durable structural growth.
Why the Full Dataset Matters
This overview has intentionally presented the strategic scaffold while reserving the detailed segment magnitudes, regional distributions, and application-level monetary splits for the complete report. That design reflects how executive intelligence should work: enough transparency to establish credibility and demonstrate analytical depth, while preserving the full economic granularity that drives precise planning.
Subscribers to the full study gain access to the complete segmentation values, market concentration detail, competitive profiling, and scenario framing needed to convert the 6.98 percent compound trajectory and the broader 2020-to-2032 arc into actionable investment decisions. For teams responsible for 2026 budgeting, channel strategy, product roadmaps, or regulatory readiness, the full dataset provides the resolution required to move from directional confidence to specific commitment.
Closing Perspective
The sanitary napkin for feminine care market is expanding within a context defined by consumer-refinement pressure, intensifying brand and manufacturing competition, and a maturing regulatory environment. Growth is real, but its value will be captured by organizations that can align product differentiation, compliance discipline, and competitive positioning with a clear view of where demand and margin will concentrate.
PW Consulting’s study is designed to make that alignment practical. It connects historical evidence, forward projections, competitive behavior, and regulatory direction into a single planning framework. For executives preparing 2026 decisions, the report offers both the strategic narrative and the operational detail needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Sanitary Napkin for Feminine Care Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


