



PW Consulting: POCT Market Hits $215M in 2025, Projects $377.98M by 2032 at 8.5% CAGR

Navigating the Point-of-Care Testing Landscape: Strategic Insights for 2026 and Beyond
The global healthcare delivery model is undergoing a fundamental structural shift, moving diagnostics from centralized laboratories to the patient's side. As we enter 2026, Point-of-Care Testing (POCT) is no longer merely a convenience but a critical infrastructure component for resilient health systems. PW Consulting's latest comprehensive market research provides a definitive roadmap for stakeholders navigating this high-growth environment. This analysis synthesizes historical performance with forward-looking projections to underscore the strategic imperative of understanding this market's trajectory.
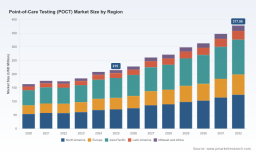
The market has demonstrated remarkable resilience and growth over the past half-decade. Valued at approximately 163 million USD in 2020, the industry navigated volatility before establishing a robust upward trend. By 2025, the market size stabilized around 215 million USD, setting the stage for accelerated expansion. Our forecast period, spanning from 2026 to 2032, indicates a compound annual growth rate of 8.5 percent. This growth suggests the market could approach close to 378 million USD by the end of the decade, driven by aging demographics, the prevalence of chronic diseases, and the enduring demand for rapid diagnostic results.
Lateral Flow POC Reader Market
Strategic Value for Enterprise Decision-Making
For executives and investors, understanding the aggregate numbers is only the first step. The true value of this research lies in dissecting the underlying drivers that will dictate capital allocation and product development strategies in 2026. The transition to decentralized testing is creating new value chains, altering reimbursement landscapes, and reshaping competitive dynamics. Our report moves beyond surface-level statistics to offer actionable intelligence on where value is being created and how market share is being contested.
Decision-makers need to anticipate regulatory shifts that could alter compliance costs and market access. Similarly, understanding the concentration of power among top-tier vendors is essential for assessing supplier risk and partnership opportunities. The following sections detail the operational depth included in the full study, designed to mitigate risk and identify high-probability growth avenues.
Operational Scope and Analytical Depth
This market research is constructed to serve as a practical toolkit for strategy formulation. It bridges the gap between high-level market sizing and on-the-ground commercial execution. Readers will find granular analysis covering the entire ecosystem, from manufacturing inputs to end-user adoption patterns.
-
Technology Segmentation Analysis: The report categorizes the market by testing type, including glucose monitoring, infectious disease testing, cardiometabolic testing, and other emerging categories. We analyze the adoption curves and technological maturity of each segment to predict future revenue mix shifts.
-
End-User Application Drivers: Special attention is given to the settings where testing occurs, such as hospital bedside, physician offices, and home self-testing environments. Understanding the unique procurement cycles and regulatory requirements of each application is vital for market entry strategies.
-
Regional Market Dynamics: We examine performance across key geographic territories, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This analysis highlights varying levels of market maturity and infrastructure readiness without limiting the scope to static regional snapshots.
-
Supply Chain and Manufacturing Insights: The study evaluates the operational capabilities required to scale POCT devices and consumables, considering reagent stability, device portability, and connectivity requirements.
Competitive Landscape and Key Player Strategies
The POCT market is characterized by a mix of established diagnostics giants and specialized innovators. Our analysis provides detailed profiles of the core companies shaping the industry, evaluating their product portfolios, strategic positioning, and recent market activities. The competitive intensity is notable, with a significant portion of revenue concentrated among the top firms, indicating high barriers to entry and strong brand loyalty.
Major Incumbents and Product Portfolios
Leaders in the space are leveraging diverse technological platforms to capture share across multiple testing categories. Abbott Laboratories, headquartered in Abbott Park, Illinois, continues to strengthen its position with the i-STAT system and the ID NOW rapid molecular platform, alongside the Alinity i for various markers. These offerings span cardiac, infectious, and metabolic testing, providing a broad suite for clinical settings.
F. Hoffmann-La Roche Ltd, based in Basel, Switzerland, is focusing on molecular precision with the cobas liat system. Their recent activities highlight a push toward multiplex testing capabilities at the point of care, enabling rapid detection of multiple targets simultaneously. Siemens Healthineers AG from Erlangen, Germany, offers comprehensive solutions for blood gas, cardiac, and routine testing, utilizing high-throughput analyzers that bridge the gap between central lab efficiency and point-of-care speed.
Danaher Corporation, located in Washington, D.C., leverages its subsidiary strengths through Cepheid GeneXpert and Beckman Coulter platforms. These tools address molecular and immunoassay needs, catering to complex diagnostic requirements in varied care settings. QuidelOrtho Corporation in San Diego, California, maintains a strong presence with Sofia fluorescent analyzers and QuickVue lateral flow tests, focusing on rapid immunoassay POCT for infectious diseases. Becton, Dickinson and Company (BD), based in Franklin Lakes, New Jersey, provides the Veritor system and other rapid diagnostic platforms, covering both molecular and immunoassay tests to support decentralized testing initiatives.
bioMérieux SA, headquartered in Marcy-l'Étoile, France, contributes with the BIOFIRE and VITEK 2 systems, emphasizing rapid molecular and automated solutions for critical care environments. Thermo Fisher Scientific Inc., from Waltham, Massachusetts, rounds out the key player list with rapid diagnostic and molecular test solutions tailored for infectious diseases and clinical POCT applications.
Point-of-Care Testing (POCT) Market
Recent Strategic Moves and Regulatory Milestones
Market velocity is often dictated by regulatory approvals and strategic consolidations. Our report tracks these events to provide context on market readiness. In early 2025, Roche received FDA clearance with a CLIA waiver for cobas liat STI multiplex panels, expanding the utility of their platform for point-of-care use in sensitive testing scenarios. Later that year, in July 2025, BD received FDA 510(k) clearance for the BD Veritor System for SARS-CoV-2 rapid point-of-care testing, transitioning from emergency use authorization to standard clearance, which signals a maturation in the regulatory pathway for respiratory diagnostics.
Strategic consolidation is also reshaping the landscape. In June 2025, QuidelOrtho announced its intent to acquire LEX Diagnostics, contingent on U.S. FDA clearance for the VELO respiratory POCT system. This move included plans to discontinue the Savanna platform, indicating a strategic pivot toward next-generation respiratory testing technologies. Additionally, independent developments such as SEKISUI Diagnostics launching new rapid diagnostic tools for RSV detection in professional healthcare settings during May 2025 highlight the ongoing innovation pipeline beyond the major conglomerates.
Regulatory Dynamics and Industry Standards
The operational environment for POCT is heavily influenced by regulatory frameworks that ensure test accuracy and reliability. A significant update occurred in January 2025, when full effects of CLIA regulatory updates for point-of-care testing went into place. These updates included enhanced proficiency testing requirements with a performance range of plus or minus 8 percent for analytes like hemoglobin A1C. Such regulations directly impact device validation, quality control protocols, and the cost structure for providers implementing POCT solutions.
Understanding these regulatory nuances is critical for any organization planning to introduce new tests or expand existing ones. Our research details how these compliance requirements affect different testing types and regions, offering guidance on navigating the approval processes and maintaining operational compliance without stifling innovation. The interplay between regulatory bodies and market innovation defines the pace at which new technologies can be deployed to patients.
Market Concentration and Future Outlook
The competitive structure of the POCT market suggests a consolidated environment where scale and technological breadth are key advantages. Our data indicates a concentration ratio among the top three and top five firms that underscores the dominance of established players. This concentration influences pricing power, supply chain negotiations, and the ability to invest in R&D for next-generation platforms.
Looking toward 2032, the trajectory points toward increased integration of digital health solutions with physical testing devices. Connectivity, data interoperability, and automated result reporting will likely become standard expectations rather than differentiators. The growth from 228 million USD in 2026 to nearly 378 million USD by 2032 represents not just revenue expansion but a transformation in how healthcare data is generated and utilized.
Investors and corporate strategists must consider how these long-term trends align with their portfolios. The shift toward home self-testing and physician office-based testing continues to rise, challenging traditional hospital-centric models. Each segment presents unique challenges regarding reimbursement, user education, and device usability. Our full report provides the segmented data necessary to model these scenarios accurately.
Unlock the Full Intelligence
This overview serves as a strategic preview of the comprehensive intelligence available in PW Consulting's full Point-of-Care Testing Market Report. While the macro trends and competitive dynamics outlined here provide a strong foundation, the detailed segmentation data, specific regional revenue estimates, and granular application breakdowns are essential for precise planning. The specific numerical splits across regions, testing types, and applications reveal the nuanced opportunities that aggregate data obscures.
Access to the complete dataset allows stakeholders to benchmark their internal targets against market realities, identify underserved niches, and anticipate competitor moves with greater accuracy. The detailed profiles of key companies, including specific product positioning and recent development timelines, offer a clear view of the battlefield. For procurement teams, the insights into supplier concentration and regulatory requirements inform risk management strategies.
To leverage these insights for your 2026 planning cycle, we invite you to access the full report web page. There you will find the complete quantitative models, deep-dive case studies, and actionable recommendations tailored to drive growth in the evolving POCT landscape. Do not rely on partial data for critical strategic decisions; obtain the complete intelligence package to secure a competitive advantage in this high-growth market.
The window for strategic positioning in the Point-of-Care Testing market is open, but the landscape is shifting rapidly. Armed with the right intelligence, organizations can navigate regulatory changes, capitalize on technological advancements, and capture value in a market poised for significant expansion. PW Consulting remains committed to providing the clarity needed to turn market complexity into strategic opportunity.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


