



PW Consulting: Flooring Underlayment Market to Reach $2.7B by 2032 with 4.8% CAGR

Strategic Intelligence for a Resilient Floor: Inside the 2026 Flooring Underlayment Market Outlook
The flooring underlayment market is entering a decisive phase of commercial maturity, where incremental growth hides complex structural shifts. For executives navigating procurement, product development, or channel strategy in 2026, surface-level demand signals are no longer sufficient. What matters now is the interaction between raw-material volatility, regional manufacturing footprints, warranty-driven performance standards, and the quiet consolidation shaping competitive positioning. Our newly released market research distills these forces into an actionable framework, giving leadership teams a reliable basis for capital allocation, pricing discipline, and portfolio planning through the end of the decade.
The numbers tell a story of steady expansion rather than explosive disruption. Between 2020 and 2025, the global market climbed from roughly $1.53 billion to $1.94 billion, reflecting a cumulative push built on residential renovation, commercial retrofit programs, and a broader shift toward performance-oriented floor systems. Heading forward, the forecast period from 2026 to 2032 points to continued upward momentum, with the market trajectory implying a compound annual growth rate of 4.8 percent. That pace is significant not because it is dramatic, but because it is durable: it signals an industry where growth is increasingly tied to specification quality, installer behavior, and material innovation rather than simple volume replacement.
Yet durable growth creates a more demanding decision environment. A market expanding at this speed still remains structurally fragmented at the top. Concentration metrics indicate that the three largest players account for approximately 42.5 percent of revenue, while the top five hold around 58.2 percent. In practical terms, that means scale advantages exist, but they are not yet absolute. Regional demand patterns, application-specific requirements, and material preferences continue to create differentiated opportunity zones. Our research maps these zones without reducing them to oversimplified rankings, allowing decision-makers to see where intensity is rising and where margins are most exposed.
The strategic value of this report lies in its operational focus. Rather than stopping at top-line forecasts, it integrates the market numbers with the mechanics that actually shape profitability: raw-material input dynamics, regulatory and warranty constraints, labor and installation practices, and the pricing pressures emerging from trade and transportation costs. These are the variables that determine whether a company can convert demand into margin. In 2026, that conversion is anything but automatic.
What the Research Delivers
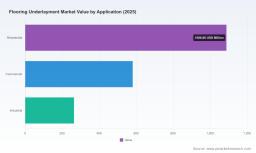
This study is designed as a decision-grade reference for executives who need to anticipate shifts before they become visible in quarterly results. The analysis combines historical performance tracking with forward-looking scenarios, allowing readers to test assumptions against a structured baseline. The report examines how demand is forming across residential, commercial, and industrial applications, and it evaluates how material types are competing for share in increasingly specification-driven environments.
Beyond segmentation, the research digs into the operational realities that separate resilient operators from those simply riding market growth. It assesses how manufacturers are responding to raw-material cost sensitivity, especially where polyethylene-based foam remains central to dominant product categories and pricing tracks closely with crude oil movements and refinery capacity conditions. It also examines how recycled rubber and natural cork formulations are being rebalanced after the supply disruptions of 2022 and 2023, enabling a number of producers to revisit capacity expansion with greater confidence.
Equally important, the report addresses the commercial constraints that define product viability. Underlayment performance is not merely a technical question; it is a warranty question. For resilient flooring, manufacturers commonly require underlayment to remain within strict thickness limits, often capping total build at around 3 millimeters to prevent stress on locking joints and avoid voiding warranties. This constraint shapes product design, installation guidance, and competitive differentiation in ways that many market summaries overlook. Our analysis places these limitations in context so that strategy teams can evaluate where performance claims are credible and where they risk creating downstream friction.
Flooring Underlayment Market
The research also incorporates the cost pressures that are reshaping sourcing and import planning. Tariffs are increasing expenses tied to imported foam materials, rubber components, and cork, while transportation surcharges continue to influence landed costs. For companies operating across multiple regions, these pressures do not simply raise prices; they alter the economics of channel selection, inventory positioning, and supplier diversification. By mapping these dynamics alongside regional demand intensity, the report helps leaders identify where cost absorption is feasible and where it is not.
Competitive Landscape: Scale, Specialization, and Recent Moves
The competitive environment reflects a blend of broad-capability incumbents and smaller specialists competing on acoustics, moisture control, sustainability, and application-specific performance. The market is not defined by a single product philosophy. Instead, it is shaped by manufacturers who are pursuing different answers to the same core question: how to deliver sound reduction, moisture protection, and installation reliability without breaking warranty constraints or exposing the buyer to excessive cost volatility.
Several companies illustrate the strategic range now visible in the sector. MP Global Products, based in Norfolk, Nebraska, has built recognition around acoustic fiber underlayments marketed under the QuietWalk brand for hardwood, laminate, and vinyl flooring. Its emphasis on noise reduction, moisture protection, and recycled content reflects a broader industry push toward environmentally conscious formulations that still meet performance expectations in residential and commercial settings. Leggett & Platt Flooring Products remains a major U.S. force in carpet cushion and hard-surface underlayment, offering foam, rubber, and other formulations tailored to laminate, vinyl, and engineered wood applications. Its breadth positions it as a supplier that can address multiple floor types within a single procurement relationship.
Pak-Lite, Inc. occupies a distinctive niche as a large private-label manufacturer of floating wood and laminate flooring underlayment in North America, with customized products structured around IIC, STC, and Delta performance ratings. That rating-centered approach matters because it aligns product selection with measurable acoustic outcomes, an increasingly important factor for specification-driven projects. Wise Flooring Products LLC, in Old Hickory, Tennessee, focuses on recyclable, American-made underlayment for residential and commercial applications, reinforcing a domestic-production value proposition that resonates in certain procurement environments. FloorMuffler contributes a portfolio spanning XLPP foam, rubber, and recycled-fiber underlayments, including product lines such as FloorMuffler UltraSeal, Natura, and FloorMat, all oriented toward sound insulation and moisture protection beneath vinyl, laminate, and hardwood.
Regional manufacturing presence is also expanding the field. Cyg Tefa, based in Vietnam, supplies high-density IXPE foam underlayment for luxury vinyl plank, laminate, and wood flooring, with an emphasis on soundproofing and moisture resistance. Hubei Xiangyuan New Material Technology Inc. operates as a professional manufacturer offering multiple underlayment types for different flooring applications, reflecting the broader diversification of Asian material supply capacity. RSP Industries, Inc. rounds out the competitive picture as a manufacturer of acoustic underlayment products, adding another voice to a market where sound performance is becoming a primary purchase criterion.
Roofing Underlying Materials Market
Recent activity in 2026 underscores how actively companies are trying to reshape category expectations. In May 2026, Floordi introduced F-Shield Underlayment, a premium acoustic solution intended to improve floor stability, enhance acoustic comfort, and add moisture protection for modern flooring systems. The launch signals continued investment in higher-performance formulations rather than basic cushioning. In April 2026, MP Global Products promoted its range of eco-friendly acoustic underlayments, emphasizing recycled material usage alongside noise reduction and moisture control. Earlier, in January 2026, Cyg Tefa showcased advanced IXPE and XPE foam underlayment solutions at Vietbuild Hanoi 2025, highlighting soundproofing, moisture resistance, and suitability for LVP, laminate, and wood flooring, with reported interest from manufacturers and distributors.
These moves matter because they reveal where the market is trying to earn higher margins: through better acoustic performance, stronger moisture management, and clearer sustainability storytelling. They also show that competition is no longer confined to price per square foot. As specifiers and installers become more attentive to warranty compatibility and long-term floor stability, companies that can credibly demonstrate performance across multiple criteria are better positioned to defend pricing and win repeat business.
Market Dynamics Shaping 2026 Decisions
The operational context of the underlayment market is being reshaped by a small number of powerful forces. Raw-material sensitivity remains one of the most important. Polyethylene foam continues to serve as a primary input for the dominant foam-based underlayment category, which means pricing exposure is closely linked to crude oil swings and refinery capacity constraints. In a market growing at a mid-single-digit pace, input volatility can quickly alter the profitability of otherwise successful product lines. Companies that rely on a narrow material base face greater risk than those with diversified formulations or stronger hedging and sourcing strategies.
At the same time, supply chain normalization is creating new strategic room. Recycled rubber and natural cork remain common in underlayment formulations, and the stabilization of supply after the disruptions of 2022 and 2023 has allowed some manufacturers to move more confidently toward capacity expansion. That shift is not merely operational; it has strategic implications for lead times, regional fulfillment, and the ability to support product launches with reliable inventory. In practical terms, normalized supply can become a competitive advantage when paired with the right application focus.
Regulatory and warranty constraints are equally important. Underlayment must meet manufacturer warranty requirements for resilient flooring, and those requirements often include strict limits on total thickness, typically capping build at about 3 millimeters to avoid excessive stress on locking joints and the risk of voiding warranties. This reality limits the scope for oversized product claims and pushes differentiation toward material density, acoustic ratings, moisture behavior, and installation consistency. For strategy teams, it means that the most defensible product narratives are those aligned with accepted installation parameters rather than speculative performance extremes.
Trade exposure is another pressure point. Tariffs are increasing costs for imported foam materials, rubber components, and cork used in underlayment production, while transportation surcharges add further complexity to landed-cost calculations. These effects vary by sourcing footprint, but they consistently influence the relative attractiveness of domestic production, regional sourcing, and inventory buffering. Companies that treat these costs as static will likely misjudge margin durability. Those that incorporate them into scenario planning will be better prepared to adjust pricing, revise supplier mixes, or shift demand toward less exposed product lines.
Labor and installation dynamics also deserve attention. In the U.S. market, moisture mitigation systems and installer-focused innovation are influencing labor requirements for floor prep and underlayment installation. This matters because installation friction can determine adoption rates just as much as product specification. If a solution is technically strong but difficult to deploy consistently across job sites, its commercial advantage may be limited. Conversely, installer-friendly designs can improve throughput, reduce rework, and strengthen end-user satisfaction, all of which support repeat demand and specification lock-in.
How to Use This Research in 2026
The report is structured to support several high-value decisions at once. For product and innovation teams, it provides a baseline for assessing which performance attributes are gaining commercial weight and where claims must remain closely aligned with warranty and installation constraints. For sourcing and operations leaders, it connects material volatility and trade exposure to practical choices about supplier diversity, inventory posture, and regional fulfillment. For commercial and sales leadership, it helps explain why the market is increasingly rewarding specification credibility, acoustic performance, and moisture management over simple cost positioning.
Most importantly, the research is built to support scenario-based planning. A market expanding at a 4.8 percent CAGR over the 2026 to 2032 forecast period is not a market where a single strategy will remain optimal for long. Different regions, applications, and material types will respond unevenly to cost pressures, demand shifts, and competitive launches. The report helps leadership teams anticipate that unevenness, identify where concentration and fragmentation intersect, and evaluate which moves are likely to strengthen positioning versus merely preserve share.
This overview is intended as a strategic preview, not a complete substitute for the full analysis. The underlying report contains the detailed segmentation structures, competitive benchmarking, and operational insights needed to translate market direction into executable plans. For organizations preparing budgets, expansion choices, or product roadmaps for the remainder of the decade, that deeper intelligence is where uncertainty becomes manageable and strategy becomes durable.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


