



PW Consulting: Thyristors Market Hits $1,461M in 2025, Driven by 4.1% CAGR to 2032

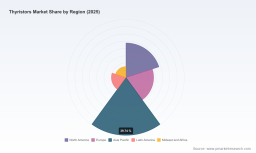
Powering Critical Infrastructure: The Strategic Imperative of the Global Thyristors Market Outlook 2026–2032
In the architecture of modern electricity, few components are as quietly indispensable as the thyristor. From grid stabilization to high-power industrial drives, these semiconductor switches dictate the reliability of systems that societies and economies depend on daily. As we enter 2026, the thyristors market stands at a decisive inflection point, shaped by evolving power demands, supply chain recalibrations, and accelerating deployment in renewable energy and mobility. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the difference between reactive planning and competitive advantage lies in rigorous, forward-looking intelligence.
This insight introduces our latest thyristors market research, a comprehensive study designed to equip decision-makers with the analytical depth required to act confidently across the 2026–2032 forecast horizon. Rather than offering static snapshots, the report translates macroeconomic signals, technology shifts, and competitive maneuvers into actionable strategic frameworks.
Market Trajectory: From Recovery to Sustained Expansion
The global thyristors market has demonstrated consistent growth over the past half-decade, reflecting the ongoing electrification of industrial processes, the modernization of power transmission networks, and the proliferation of power electronics across consumer and automotive applications. Historical data from 2020 through 2025 reveals a market that has steadily expanded, reaching approximately USD 1,461.0 Million in 2025. This trajectory underscores not only demand resilience but also the component's entrenched role in mission-critical power control environments.
Looking ahead, the forecast period from 2026 to 2032 projects a robust expansion pathway, with the market anticipated to reach approximately USD 1,936.5 Million by 2032. This growth corresponds to a compound annual growth rate of 4.1 percent, a pace that signals steady, structurally supported demand rather than a short-lived cyclical spike. The implication for strategic planners is clear: thyristor-enabled solutions are being woven more deeply into long-cycle infrastructure and industrial automation investments, creating multi-year revenue visibility for suppliers and system integrators alike.
Yet, headline figures only tell part of the story. The real strategic value lies in understanding where growth concentrates, which applications drive incremental volume, and how regional dynamics influence sourcing and localization. Our analysis unpacks these layers without oversimplifying them, giving leaders a nuanced map of opportunity rather than a single aggregated number.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
Our thyristors market study is structured to address the practical questions that arise in boardrooms, engineering reviews, and procurement discussions. The report provides a multidimensional view of the market, combining quantitative forecasting with qualitative analysis of technology roadmaps, demand catalysts, and competitive positioning. Key areas of coverage include:
- Macro-market sizing and growth projections across the base year and forecast horizon, anchored in a transparent methodology that allows for scenario testing.
- Segment-level analysis by product type, application, and geographic region, illuminating which categories are expanding fastest and why.
- Demand driver assessment covering grid modernization, industrial automation, renewable integration, e-mobility, and power conversion needs.
- Supply-side dynamics, including manufacturing capacity trends, raw material trajectories, lead-time behavior, and cost structure sensitivities.
- Competitive landscape profiling that maps the strategic moves of leading incumbents and emerging challengers across the value chain.
- Technological and regulatory context, highlighting how material availability, wafer economics, and policy shifts affect downstream planning.
The objective is not to overwhelm with data but to distill complexity into decision-ready formats. Executives can use the study to evaluate market entry assumptions, benchmark regional exposure, refine product portfolio priorities, and anticipate supply continuity risks. For procurement and operations leaders, the report surfaces practical indicators that inform contracting, inventory strategy, and supplier diversification.
Competitive Landscape: Establishing Position in a Concentrated Arena
The thyristors market is characterized by a notably concentrated competitive structure, with a small group of established players commanding a substantial share of total revenue. This concentration has important strategic implications. It suggests that scale, technological breadth, application-specific expertise, and long-standing customer relationships remain powerful moats. At the same time, it signals that competitive differentiation increasingly comes from portfolio completeness, performance in extreme operating conditions, and the ability to support specialized end markets.
Leading participants reflect a diverse set of strategic orientations. Some competitors focus on high-power solutions spanning thyristors, GTOs, IGCTs, and diodes, serving grid, traction, renewables, and e-mobility applications with broad current and voltage ranges. Others specialize in bipolar thyristor discs and pulse-power devices manufactured in-house, emphasizing low thermal resistance and high-voltage capability for demanding industrial and pulsed-power environments. Additional players concentrate on mission-critical power modules for aerospace, defense, and space applications, or on discrete SCR and TRIAC devices for motor control, lighting, heating, and general industrial systems.
The field also includes semiconductor manufacturers integrating thyristors and related modules into broader power conversion and automotive portfolios, alongside specialists providing SCR thyristors and AC switches for industrial and consumer power control. Discrete device producers serving alternative energy, lighting, and industrial use cases further round out the landscape, while companies focused on power discrete thyristors and TRIACs address automotive, consumer, and industrial power management needs. Collectively, these players demonstrate that the market is not monolithic; it is a mosaic of overlapping capabilities, each shaped by distinct technological strengths and customer segments.
Importantly, competitive dynamics are not static. Recent developments illustrate how capital commitments and policy support can reshape production capacity and innovation pacing. For example, a significant funding agreement finalized in mid-2026 provides targeted investment to expand domestic manufacturing and R&D for power modules, including thyristors. Such moves matter because they influence regional supply resilience, cost trajectories, and the speed at which new capabilities reach the market. In a concentrated environment, even a single major capacity or R&D announcement can alter bargaining dynamics and competitive expectations across the value chain.
Industry Dynamics: Lead Times, Raw Materials, and Cost Signals
Beyond company-level activity, broader industry dynamics are shaping how organizations plan for 2026 and beyond. One critical factor is lead-time behavior for discrete components. In the second quarter of 2025, lead times for discrete components, including thyristors, held steady or increased slightly, reaching approximately 26 weeks. For sourcing teams and system designers, this is more than a logistical statistic; it affects inventory buffers, project timelines, and the feasibility of just-in-time models in high-reliability applications. The persistence of extended lead times reinforces the importance of supplier collaboration, demand forecasting accuracy, and multi-source strategies where technically feasible.
Worldwide Thyristor Protectors Market
On the materials side, silicon wafer shipments rose 5.4 percent in 2025, with new record shipments forecast for 2028. This trend is supportive for the supply of foundational inputs used in thyristor production, helping to moderate certain cost pressures over the medium term. However, material availability does not automatically translate into stable end-device economics. Upstream costs remain sensitive to node-specific manufacturing economics and specialized wafer pricing. In 2026, advanced-node wafer costs increased by 3 to 10 percent, with 2 nm wafers reaching approximately USD 30,000 per wafer. While thyristor technologies do not uniformly depend on leading-edge nodes, these broader semiconductor cost dynamics influence overall material expense expectations, capital investment decisions, and pricing strategies across the power semiconductor ecosystem.
Together, these dynamics highlight a market where planning must account for both demand-side momentum and supply-side friction. Effective strategy requires a holistic view: aligning product roadmaps with likely lead-time envelopes, evaluating how wafer and material trends affect cost assumptions, and monitoring capital investments that could alter regional supply balances. The report integrates these factors to help leaders stress-test their assumptions under realistic operating conditions.
Strategic Takeaways for 2026 and Beyond
As organizations set priorities for the coming years, several strategic themes emerge from the market landscape:
- Demand durability is anchored in infrastructure and industrial use cases. The thyristors market's growth is closely tied to long-cycle investments in power transmission, industrial automation, and renewable integration. Teams should evaluate how these durable demand streams align with their sales coverage, service capabilities, and product support models.
- Portfolio breadth and application specialization create differentiation. With a concentrated competitive field, firms that can combine high-power capabilities, thermal performance, and application-specific support are better positioned to defend margins and capture complex requirement sets.
- Supply continuity is a strategic variable, not just an operational concern. Lead-time persistence and material cost movements require proactive planning, including scenario-based inventory policies, supplier diversification, and close monitoring of capacity investments.
- Regional context matters for sourcing and market access. Different regions present distinct demand profiles and supply dynamics. Understanding where demand is intensifying and how local production or policy initiatives may evolve can inform market prioritization and risk management.
- Capital and policy developments can shift competitive expectations. Major funding commitments and domestic production expansions can affect cost structures, lead times, and supplier relationships. Keeping pace with such developments helps organizations anticipate changes rather than react to them.
Why This Research Matters Now
The 2026–2032 outlook period is not a routine forecast window; it is a planning horizon in which today's assumptions will shape tomorrow's competitive position. The thyristors market is expanding at a measured but meaningful pace, supported by broad-based application demand and an increasingly strategic view of power electronics across industries. In this environment, theorganizations that excel will be those that pair market awareness with disciplined execution: selecting the right segments, anticipating supply constraints, and aligning product and sourcing strategies with where value is actually created.
Our study is designed to support exactly that kind of decision-making. It offers the analytical rigor required to justify investment choices, the segmentation detail needed to prioritize resources, and the competitive context necessary to understand where pressure points and opportunities lie. Most importantly, it is built to be practical—translating complex market forces into clear implications for product planning, procurement, sales strategy, and risk management.
Thyristors Market
Explore the Full Intelligence
The information summarized here is intended to provide a credible preview of the depth and direction of our research. Many of the most actionable insights—the detailed segmentation values, region- and application-level breakdowns, company-specific strategic assessments, and scenario-based projections—are reserved for the full report. Those details are essential for translating high-level trends into precise operational decisions, and they are available in the complete study.
To access the full thyristors market research, including comprehensive sizing, segmentation analysis, competitive profiles, and forward-looking strategic recommendations for 2026 and beyond, please visit the report page on our website. There you will find the complete dataset and analysis needed to support confident, evidence-based decisions in a market where timing, positioning, and supply awareness matter more than ever.
For detailed analysis of this topic, please visit the official page: Thyristors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


