



PW Consulting: Low Voltage DC-DC LED Drivers Market to Reach $458.6M by 2032, Growing at 6.2% CAGR

Navigating the Low Voltage DC-DC LED Drivers Market: Strategic Foresight for 2026 and Beyond
Executive Summary
The global landscape for low voltage DC-DC LED drivers is undergoing a structural transformation. As lighting systems migrate toward higher efficiency, smarter controls, and lower power architectures, the demand for precision power conversion has intensified across residential, commercial, industrial, and mobility sectors. Our latest market intelligence report maps this evolution with granular rigor, offering enterprise decision-makers a clear vantage point to align product roadmaps, supply chain strategies, and capital allocation with the trajectory set for 2026 and the following years.
This study is not a static snapshot of historical sales figures. It is a forward-looking strategic compass designed for executives who must navigate component shortages, regional regulatory shifts, and intensifying competition among semiconductor and module manufacturers. By weaving together historical performance, medium-term forecasting, and competitive positioning, the report equips stakeholders with the analytical foundation required to make confident, time-sensitive decisions in an increasingly fragmented ecosystem.
Market Trajectory and Macro Dynamics
Between 2020 and 2025, the low voltage DC-DC LED driver market demonstrated a steady expansion profile, recovering from a temporary contraction in 2024 before resuming upward momentum. The baseline data confirms that revenue reached approximately 245.8 million USD in 2020, climbed through successive years, and crossed the 309.5 million USD threshold by 2025. Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.2 percent, with estimated revenue scaling from 337.58 million USD in 2026 toward 458.6 million USD by the end of the forecast window.
This growth trajectory is underpinned by several interlocking forces. First, the ongoing replacement of legacy lighting infrastructure with energy-efficient LED solutions continues to drive baseline demand, particularly in retrofit and new-build scenarios where low-voltage topologies offer advantages in thermal management and system integration. Second, the proliferation of intelligent lighting ecosystems—requiring precise current regulation, dimming compatibility, and compatibility with microcontroller-driven control planes—has elevated the functional bar for DC-DC driver components. Third, supply chain normalization and localized sourcing initiatives are gradually reshaping procurement patterns, influencing both cost structures and time-to-market expectations.
Low Voltage DC-DC LED Drivers Market
Crucially, the 6.2 percent CAGR is not a uniform assumption across all sub-segments. The report dissects where growth concentrates, which drivers face margin compression, and how end-use adopters recalibrate their purchasing cycles in response to component availability and total cost of ownership calculations. Enterprise readers will find particular value in the way these macro trends are mapped to actionable procurement and engineering strategies rather than treated as abstract numerical outputs.
Segmentation Architecture and Demand Drivers
The study segments the market along three primary dimensions—geography, converter topology, and end-use application—providing a layered view of where volume flows and where differentiation becomes decisive. Rather than presenting isolated percentage breakdowns, the analysis emphasizes the relative weight, growth rhythm, and strategic implications of each segment.
From a regional perspective, the Americas, Europe, and Asia Pacific collectively anchor the bulk of global demand, each shaped by distinct regulatory frameworks, construction cycles, and manufacturing footprints. Latin America and the Middle East and Africa represent smaller but structurally evolving bases, where infrastructure modernization programs and import substitution efforts are beginning to alter demand patterns. The report explores how supply logistics, certification requirements, and local partnership ecosystems influence competitive positioning across these regions without reducing the narrative to static share figures.
On the technology side, the market divides between isolated and non-isolated DC-DC converter architectures. Isolated solutions remain critical in applications demanding galvanic separation for safety, noise immunity, or system-level grounding strategies, while non-isolated topologies continue to gain traction in cost-sensitive, space-constrained, and efficiency-optimized designs. The analysis evaluates how design-in preferences shift as engineers balance bill-of-materials constraints against reliability and compliance mandates, and how component suppliers tailor reference designs, evaluation boards, and support materials to capture design wins early in the development cycle.
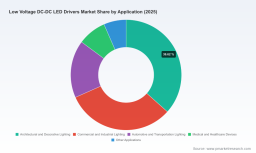
Application-side segmentation reveals equally nuanced dynamics. Architectural and decorative lighting continues to serve as a substantial volume center, driven by interior retrofit programs, hospitality upgrades, and retail refresh cycles. Commercial and industrial lighting contributes a significant share, with growth fueled by warehouse modernization, smart-building integrations, and energy-code compliance initiatives. Automotive and transportation lighting represents a specialized but expanding frontier, where low-voltage DC-DC drivers must meet stringent thermal, vibration, and electromagnetic compatibility expectations. Medical and healthcare devices form a smaller yet high-spec segment, emphasizing reliability, noise performance, and long lifecycle support, while miscellaneous applications round out the demand base with niche but strategically relevant use cases.
For decision-makers, the strategic takeaway lies in recognizing that no single segment behaves uniformly. Growth pockets emerge where application requirements, regulatory tailwinds, and component readiness intersect, and the report provides the contextual scaffolding needed to prioritize those intersections.
Competitive Landscape: Strategies, Positioning, and Design-Win Dynamics
The market features a concentrated set of influential participants, with the top three firms collectively accounting for roughly 37.2 percent of total revenue and the top five reaching approximately 47.8 percent. This level of concentration signals a landscape where scale, portfolio depth, and ecosystem support materially influence competitive outcomes, even as specialized players carve out defensible niches through application-specific engineering and agile customization.
Texas Instruments maintains a prominent position through its DC-DC LED driver controllers and reference designs aimed at flicker-free low-voltage LED lighting in both portable and fixed installations. Its strategy emphasizes design-in enablement, offering evaluation platforms and application notes that accelerate integration for engineering teams seeking predictable performance. Analog Devices competes with a strong analog IC heritage, co-developing next-generation low-voltage DC-DC LED driver ICs tailored for automotive and consumer lighting applications. Its approach underscores the importance of co-engineering relationships and application-specific optimization in high-performance segments.
STMicroelectronics contributes PWM-dimmable LED driver ICs and complementary power management solutions, supporting DC-DC LED lighting systems where signal integrity and dimming compatibility are paramount. Infineon Technologies focuses on the ILD family of hysteretic buck DC-DC LED driver ICs, which support high currents up to 1.5 A and efficiencies up to 98 percent for general lighting applications—a profile that appeals to efficiency-driven designs and thermally constrained layouts. Diodes Incorporated provides medium- and low-voltage DC-DC LED driver ICs, including the AL8871Q and AL8862QEV2 for driving high-current LEDs, reinforcing its role in cost-conscious yet performance-aware designs.
Molex differentiates through CoreSync and Transcend Smart low-voltage DC/DC LED drivers built for constant current LED engines in lighting fixtures, positioning itself at the intersection of driver electronics and fixture-level integration. LEDdynamics offers the BuckToot low-voltage DC/DC LED driver for constant-current LED applications in fixtures, emphasizing simplicity and reliability for targeted use cases. ON Semiconductor supplies both discrete and IC solutions supporting DC-DC LED driver applications in lighting power management, broadening its addressable design scenarios across multiple system architectures. Monolithic Power Systems rounds out the competitive set with MP2489 and similar hysteretic control buck LED drivers featuring DC and PWM dimming for low-voltage LED systems, highlighting efficiency and control flexibility as recurring themes in this segment.
The strategic implication for market participants is clear. Differentiation increasingly depends on more than raw component specifications. Reference quality, application support, compliance documentation, lead-time reliability, and collaboration with fixture or system designers all affect win rates. The report examines how these players position themselves across the design-in funnel, where they face margin pressure, and how they navigate the tension between standardized product lines and customized engineering engagements.
Report Scope: What Decision-Makers Will Find Inside
This study is structured to translate market intelligence into operational guidance. It combines a rigorous quantitative backbone with qualitative analysis that speaks directly to product planning, sourcing, and competitive strategy. The scope includes:
LED Drivers Market
- A detailed historical reconstruction and forward forecast that contextualizes revenue patterns across the 2020–2032 horizon, with particular emphasis on inflection points and recovery dynamics.
- A segmentation analysis that isolates the relative significance of regions, converter topologies, and end-use applications, highlighting how growth concentrates and where competitive intensity varies.
- A comprehensive competitive assessment of key manufacturers, covering product families, positioning, and strategic implications for design-win capture and portfolio development.
- An examination of demand-side drivers, including efficiency mandates, smart-lighting adoption, retrofit cycles, and application-specific performance requirements that shape purchasing behavior.
- Supply-side considerations such as component availability, design-in support ecosystems, compliance and certification pressures, and the impact of regional sourcing shifts on cost and timeline planning.
- Strategic recommendations tailored to different stakeholder roles, from product management and engineering to procurement and market-entry planning.
The report is designed to be referenced, not merely read. Tables, comparative profiles, and scenario-aware commentary enable teams to filter insights according to their specific priorities, whether they are evaluating supplier alternatives, assessing market-entry timing, or calibrating investment against likely demand growth in targeted segments.
Strategic Implications for 2026 Decision-Making
For organizations planning initiatives around 2026, the most valuable insight is not simply that the market is expanding, but how that expansion is structured. The 6.2 percent CAGR provides a useful baseline, yet its real meaning lies in the uneven distribution of opportunity across applications, topologies, and geographies. Companies that treat the market as a monolith risk misallocating engineering resources, over-indexing on slow-moving segments, or underestimating the competitive pressure in high-growth pockets.
Procurement and supply chain teams should pay close attention to the interplay between converter architecture preferences and component availability. Isolated and non-isolated designs appeal to different system constraints, and the relative attractiveness of each depends on safety requirements, thermal budgets, bill-of-materials sensitivity, and the availability of qualified alternates. Understanding where design wins are most likely to occur—and what design-in support is needed to secure them—can materially improve forecast accuracy and reduce downstream sourcing risk.
Product and engineering leaders will find value in the way the report connects application requirements with component capabilities. Whether a team is developing architectural fixtures, commercial lighting platforms, automotive illumination subsystems, or healthcare-grade devices, the expectations for efficiency, dimming behavior, reliability, and compliance differ substantially. The study maps those differences into a structured framework that helps teams set specification priorities, evaluate reference designs, and anticipate the trade-offs that will shape commercial viability.
Commercial strategy teams should also consider the concentration dynamics of the competitive field. With the top firms holding a meaningful share, scale advantages in portfolio breadth and ecosystem support matter, but specialized players continue to succeed by aligning closely with niche requirements and delivering focused engineering value. The report examines where broad portfolios create leverage and where specialized offerings command premium positioning or stronger loyalty in targeted application sets.
Conclusion: Turning Market Intelligence into Time-Sensitive Advantage
The low voltage DC-DC LED drivers market is advancing along a path defined by efficiency imperatives, application diversification, and increasingly sophisticated design-in competition. The 2026–2032 outlook presents a credible growth arc, but realizing the value of that arc requires more than awareness of headline numbers. It requires a clear understanding of where demand concentrates, which technical and commercial levers matter most, and how leading participants compete for design influence across multiple application domains.
This report is built to provide exactly that understanding. It synthesizes historical context, forecast discipline, competitive analysis, and application-level demand dynamics into a single integrated view, enabling stakeholders to move from observation to action. For executives, engineers, and commercial leaders preparing for 2026, the difference between reactive planning and proactive strategy lies in the quality of the intelligence behind the decision.
To explore the full segmentation detail, competitive profiles, regional demand context, and forecast scenarios, access the complete study through our official market research portal. The complete dataset and extended commentary are available there for teams that require the depth needed to shape product plans, sourcing strategies, and market-entry decisions with precision.
For detailed analysis of this topic, please visit the official page: Low Voltage DC-DC LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


