



PW Consulting: Biobanking Market Hits $73.5B in 2025, Projected to Reach $114.22B by 2032 at 6.6% CAGR

The Biobanking Market at an Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global biobanking ecosystem is no longer a peripheral support function for life sciences. It has become a central infrastructure layer that determines the pace of translational research, the credibility of clinical trials, and the operational viability of precision medicine programs. As regulatory expectations rise, automation matures, and cross-institutional data sharing becomes both a mandate and a competitive advantage, executives in pharma, biotech, diagnostics, and healthcare delivery are facing a shared question: how should capital, partnerships, and operational roadmaps be aligned for the years ahead?
This article introduces PW Consulting's latest Biobanking Market research, a study designed specifically to support enterprise decision-making in 2026 and beyond. Rather than offering surface-level market commentary, the report translates macro momentum into actionable strategy by examining growth trajectories, segmentation logic, competitive positioning, regulatory pressure points, and the practical realities of scaling biobanking operations. The goal is to give leaders a defensible foundation for investment decisions, vendor selection, market entry planning, and long-term capacity strategy.
Why 2026 Is a Defining Year for Biobanking Strategy
Biobanking has entered a phase in which historical growth patterns and forward-looking operational choices increasingly diverge. Over the 2020-2025 period, the market expanded from approximately 55.3 billion USD to 73.5 billion USD, reflecting the compound effect of rising sample demand, better sample management practices, and expanding research pipelines. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, with the market projected to reach roughly 75.97 billion USD in 2026 and advance toward 114.22 billion USD by 2032. The implied compound annual growth rate of 6.6 percent is not merely a top-line statistic. It is a signal that biobanking is moving from fragmented, project-dependent scaling to more systematic, protocol-driven growth.
For executives, that signal matters because growth at this pace reshapes more than revenue forecasts. It influences how organizations think about capacity planning, regional footprint, technology adoption, and partnership models. A market growing at this level will not be won by incremental improvement alone. Firms need to determine where to build, where to buy, where to integrate, and where to standardize. They also need to understand which demand drivers are durable, which segments are consolidating, and how competitive intensity is likely to change as larger ecosystems invest in automated storage, sample logistics, and interoperable data frameworks.
The strategic challenge is compounded by the fact that biobanking now sits at the intersection of science, compliance, and infrastructure economics. High-quality sample preservation, traceability, and access are no longer optional capabilities; they are prerequisites for credible collaboration across research networks, contract organizations, and clinical programs. At the same time, capital intensity, energy requirements, and regulatory complexity create uneven adoption curves across facility types and geographies. The 2026 landscape therefore rewards firms that can separate short-term noise from structural opportunity and translate that distinction into operational choices.
What the Report Delivers: A Practical Blueprint, Not Just a Market Snapshot
This study is built to support decisions, not just descriptions. It combines historical context, forward-looking forecasts, and operational analysis into a single framework that business leaders can use to pressure-test assumptions. The report is organized to answer the questions that typically determine whether a market opportunity is commercially actionable:
- How the overall market has evolved and what the next several years are likely to look like under baseline and scenario conditions
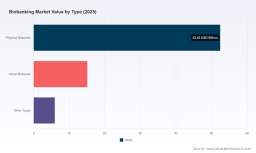
- Which structural segments are shaping demand, and how value is distributed across different biobanking types and end-use applications
- Where regional dynamics are creating concentration, divergence, or growth opportunities
- How leading suppliers are positioned, what capabilities matter most, and how the competitive field is being reshaped by automation, service models, and infrastructure investment
- Which regulatory and operational forces are changing the cost of participation, especially for smaller repositories and cross-border initiatives
- What practical implementation considerations should inform procurement, partnership, and capacity decisions in 2026
A central feature of the report is its emphasis on real-world applicability. Rather than leaving the reader with abstract market sizing, it connects growth indicators to operational realities such as automation requirements, sample handling workflows, quality and accreditation expectations, and the financial burden of ultra-low temperature preservation. The study also examines the changing role of standards and accreditation frameworks that are increasingly defining what "competent" biobanking looks like in practice. In an environment where consistency, sample integrity, and data governance are closely scrutinized, these factors directly affect which organizations can participate in high-value collaborations and which must adapt before they can scale.
Equally important, the report investigates the market's concentration profile and what it reveals about competitive dynamics. With a meaningful share of activity held by a relatively small group of established players, the landscape is neither fully fragmented nor fully consolidated. That mixed structure creates both partnership opportunities and entry barriers. For incumbents, it raises the question of how to defend core positions while expanding into adjacent services and automation-enabled workflows. For newer entrants and private capital-backed organizations, it raises the question of which niches are accessible, which require substantial infrastructure commitments, and which can be won through specialization rather than scale alone.
Competitive Landscape: Who Is Shaping the Next Phase
The competitive field in biobanking reflects a blend of industrial suppliers, automation specialists, logistics providers, and service-oriented organizations. Several companies stand out because their portfolios touch the core infrastructure of sample storage, retrieval, processing, and biobank management. Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, remains closely associated with automated storage systems, temperature-controlled equipment, and laboratory information management solutions designed for sample management. Becton, Dickinson and Company, headquartered in Franklin Lakes, New Jersey, continues to provide cryogenic systems and broader sample collection and storage solutions. PHC Holdings Corporation, headquartered in Tokyo, contributes automated cryopreservation and storage systems, while Hamilton Company, based in Reno, Nevada, focuses on robotic automation and liquid handling for biobanking workflows.
The landscape also includes organizations that approach biobanking from different operational angles. Azenta Life Sciences, based in Chelmsford, Massachusetts, develops automated storage and retrieval systems relevant to cryogenic sample management. Cryoport, Inc., headquartered in Santa Ana, California, specializes in cryogenic logistics and storage solutions. Tecan Trading AG, in Switzerland, provides laboratory automation and robotics for sample processing. Lonza Group Ltd., also based in Basel, offers services and equipment associated with cell and tissue storage. Taylor-Wharton, headquartered in Asheville, North Carolina, manufactures cryogenic freezers and storage systems. Charles River Laboratories, in Wilmington, Massachusetts, supplies equipment and services for research sample management. Stemcell Technologies Inc., in Vancouver, Canada, addresses specialized equipment and consumables for stem cell biobanking. Promocell GmbH, in Heidelberg, Germany, provides storage and processing solutions for cellular samples. Brooks Life Sciences, based in Chelmsford, Massachusetts, delivers automated sample management and storage systems.
Strategic implications of the competitive mix
This breadth of players matters because biobanking is increasingly solved as a system rather than a single product purchase. Organizations must evaluate not only the quality of a freezer or automation module, but also how well equipment, software, logistics, and service support integrate into a coherent workflow. That reality favors suppliers that can reduce operational friction and improve traceability across the full sample lifecycle. It also creates room for specialization. Some firms compete on high-throughput automation, others on cryogenic logistics, and others on consumables, cell-specific workflows, or research-grade services.
A useful way to read the competitive environment is through the lens of value migration. As sample volumes rise and collaboration networks expand, value is shifting toward capabilities that support repeatability, auditability, and interoperability. That shift is pushing established hardware and service providers to strengthen digital sample management, workflow integration, and remote monitoring features. At the same time, it is raising the importance of partnerships between equipment vendors, contract research organizations, and biobank networks that need to align on standards and exchange samples or data across institutional boundaries.
Stem Cell Banking Market
The report examines these competitive dynamics in greater depth than a simple company list can convey. It maps where scale advantages exist, where differentiation is becoming decisive, and where the demand for integrated solutions may create consolidation pressure or partnership-led growth. Because the market remains concentrated enough to reward established infrastructure players yet diverse enough to sustain specialist innovators, the strategic question is rarely whether competition exists. It is which competencies will command premium positioning as procurement teams evaluate total cost, reliability, and compliance readiness.
Regulatory, Operational, and Infrastructure Dynamics
Market growth in biobanking cannot be interpreted without acknowledging the operational constraints that shape adoption. One significant factor is capital and energy intensity. Automated storage systems and robotic repositories require substantial investment and ongoing energy consumption for ultra-low temperature preservation. These requirements limit adoption among smaller facilities, creating an uneven landscape where larger organizations and well-funded networks can move faster on automation while smaller repositories must weigh the cost of participation against their own operational scale.
Regulatory complexity adds a second layer of pressure. Biobanking operates within a range of international requirements, including GDPR, HIPAA, and 21 CFR Part 11. These frameworks create operational complexity and financial burden, particularly for smaller repositories that may lack the administrative and technical capacity to manage compliance at scale. In practice, this means that regulatory readiness is becoming a strategic differentiator. Organizations that can demonstrate consistent data governance, sample traceability, and quality control are better positioned to participate in cross-border studies, multi-site research, and high-value partnerships.
At the same time, standardization efforts are maturing. The ISO 20387:2018 standard specifies general requirements for the competence, impartiality, and consistent operation of biobanks, including quality control for biological material and data collections. European Accreditation launched a Multilateral Agreement for biobanking in 2025, with further extensions planned for 2026. These developments are not abstract. They are becoming practical criteria by which biobanks are evaluated by partners and funders, and they increasingly influence which facilities can credibly join federated platforms or cross-institutional programs.
Recent industry developments that reframe the road ahead
Recent signals from Europe illustrate how biobanking strategy is being reframed at the infrastructure level. In April 2026, BBMRI-ERIC published a 10-Year Roadmap for biobanking development through 2035, emphasizing One Health integration and infrastructure alignment across Europe. The same month, BBMRI-ERIC announced the selection of eight biobanks for dedicated funding under the EvolveBBMRI project to integrate into the BBMRI-ERIC Federated Platform. These moves matter because they show that biobanking is being treated not only as a scientific resource but also as coordinated infrastructure with alignment, interoperability, and long-term sustainability as explicit goals.
For organizations operating in or adjacent to this space, the implications are practical. Federated platforms, shared standards, and roadmap-driven investment can create new demand for compatible systems, quality processes, and service models. They also raise the bar for organizations that intend to participate in broader research ecosystems. Strategic planning in 2026 must therefore account for the fact that infrastructure alignment is becoming part of the market's growth logic, not just a compliance exercise.
How to Use This Research for 2026 Enterprise Decisions
The value of this study lies in its ability to connect market direction with decision quality. Executives can use it to evaluate whether current biobanking investments are aligned with likely demand, whether partnership strategies should prioritize automation compatibility, quality accreditation, and data interoperability, and whether regional or application-specific opportunities warrant dedicated capacity. The report is also designed to support vendor and technology evaluations by clarifying which capabilities matter most in a market where sample integrity, traceability, and operational consistency increasingly determine commercial relevance.
Because the report is structured around both macro trends and operational detail, it can support a range of decisions:
- Capacity and investment planning, including whether to expand in-house biobanking capability or rely on external service providers
- Procurement prioritization, especially when balancing automation, storage, logistics, and software integration
- Partnership and collaboration strategy, including how to position within federated networks or multi-site research programs
- Risk assessment around regulatory complexity, accreditation readiness, and the operational burden of compliance in different settings
- Market entry and expansion decisions, informed by segmentation structure and concentration patterns
The emphasis throughout is on actionable clarity. Leaders do not need another high-level overview. They need evidence that helps them determine where the market is durable, where it is fragile, and where their organization can most effectively allocate resources in the coming years.
Biobanking Market
Closing Perspective
The biobanking market in 2026 is best understood as an infrastructure market entering a more disciplined growth phase. Demand is expanding, automation is becoming a competitive necessity for many players, and regulatory and standards frameworks are increasingly shaping who can participate in high-value collaborations. At the same time, capital intensity, energy requirements, and fragmented compliance obligations continue to differentiate large and small operators. In that environment, strategic advantage comes from understanding not just that the market is growing, but how growth is being distributed, what operational capabilities it rewards, and which competitive positions are likely to strengthen over time.
PW Consulting's Biobanking Market research is designed to provide that understanding at the level of detail required for serious planning. It offers the market context, competitive analysis, segmentation logic, and operational considerations needed to support decisive action in 2026 and the forecast years that follow. For organizations that need the full segmentation view, competitive mapping, and implementation insight to move from hypothesis to execution, the complete report is available through our research portal.
For detailed analysis of this topic, please visit the official page: Biobanking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


