



PW Consulting: Electric Construction, Agriculture & Mining EV Market Hits $428M in 2025, Set for 18.5% CAGR to 2032

Electrifying the Heavy Metal: Strategic Insights for the Electric Vehicles in Construction, Agriculture, and Mining Market (2026-2032)
The heavy industry landscape is undergoing a seismic shift. Where diesel once reigned supreme as the unchallenged king of power for construction, agriculture, and mining machinery, the electrification of heavy-duty vehicles is now emerging as the definitive force shaping the next decade of industrial operations. As environmental mandates tighten and the economic case for total cost of ownership improves, the Electric Vehicles (EV) for Construction, Agriculture, and Mining market is poised for explosive growth, transforming from a niche sustainability initiative into a core strategic imperative for industrial leaders globally.
At PW Consulting, we understand that navigating this transition requires more than a superficial glance at market trends. It demands a granular, forward-looking analysis that connects macroeconomic drivers with on-the-ground product realities. Our latest comprehensive report, Electric Vehicles for Construction, Agriculture and Mining Market (2026-2032) , serves as a critical strategic compass. This insight piece explores the immediate strategic value of this research for 2026 decision-makers, highlighting the macro trajectory, the competitive intensity, and the structural forces reshaping the heavy electric ecosystem, while preserving the deep-dive segmentation data essential for precise planning within the full report.
A Market in Hypergrowth: The Numerical Trajectory
The scale of the opportunity cannot be overstated. The market has already demonstrated robust resilience and expansion over the past half-decade, moving from a foundational phase into a period of accelerated commercial deployment. Between 2020 and 2025, the market revenue surged significantly, with valuation climbing from approximately $181.6 million to $428.0 million. This historical period was characterized by pilot programs, early adopters, and the initial lowering of entry barriers for electromobility in heavy machinery.
However, the forecast period from 2026 through 2032 represents a distinct inflection point. The industry is projected to witness a steepening growth curve, driven by the maturation of battery technologies, the rollout of zero-emission regulations, and the scaling of manufacturing capacities. The overall market revenue, measured in USD million, is anticipated to accelerate noticeably. By the end of the forecast window in 2032, the market value is expected to reach a transformative level that will redefine competitive boundaries. This trajectory implies a substantiated Compound Annual Growth Rate (CAGR) of 18.5% during the forecast period. Such a rate signals that electric heavy machinery is moving toward mainstream adoption, necessitating that stakeholders prepare their capital allocation, supply chain strategies, and product portfolios for a rapidly electrifying future.
For strategic planners, these macro figures confirm that the "wait and see" approach is no longer viable. The momentum is structural, not cyclical. The transition is being underwritten by long-term decarbonization goals in Europe and North America, coupled with aggressive industrial modernization strategies in Asia Pacific. Understanding how to capture value in this expanding pie requires deep insights into which application sectors and vehicle types are driving this dollar volume, a critical analysis detailed within the full market intelligence briefing.
Segmenting the Opportunity: Where Value is Concentrated
While the aggregate growth numbers signal a booming market, the strategic distribution of that value tells a more nuanced story of where investment and procurement focus must be directed. The electric heavy machinery landscape is not a monolith; it is a complex ecosystem divided by technology architecture and end-use application, with each segment facing unique technical and economic hurdles.
Vehicle Type Dynamics: The Battery Electric Ascendancy
The technology mix is heavily skewed toward Battery Electric Vehicles (BEVs), which currently command the vast majority of market revenue. This dominance reflects the current maturity, availability, and relative cost-effectiveness of battery-based electrification compared to alternative zero-emission pathways. BEVs are leading the charge in construction and mining sectors where operational cycles can be managed, and charging infrastructure can be deployed on controlled sites.
Electric Vehicles for Construction, Agriculture and Mining Market
Conversely, Fuel Cell Electric Vehicles (FCEVs) and Plug-in Hybrid Electric Vehicles (PHEVs) occupy smaller, specialized positions in the current landscape. FCEVs, with their potential for rapid refueling and high energy density, are being eyed for specific use cases where battery weight or charging downtime is prohibitive, though their commercial penetration remains nascent. PHEVs currently serve as a transitional bridge for operators managing range anxiety or lacking full charging infrastructure, but their long-term strategic relevance is being scrutinized as full BEV ranges improve and costs decline.
Application Drivers: Construction, Agriculture, and Mining
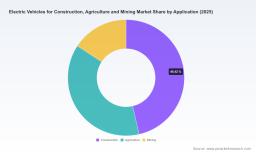
The demand pull varies significantly across the three core application verticals. The Construction sector represents the largest application share in the market, driven by urban zero-emission zones, stringent noise and emission regulations in municipalities, and the growing availability of compact and mid-size electric machinery. The agriculture sector follows as a substantial contributor, with the modernization of farming operations, labor efficiency demands, and the push for cleaner, precision agriculture fostering the uptake of electric tractors and compact utility vehicles. The Mining sector, while currently holding a smaller revenue share, represents a high-value niche where the total cost of ownership benefits of electric haulage, reduced ventilation costs in underground operations, and automated integration are compelling operators to accelerate electrification pilots into full-scale deployments.
The strategic implications of these application splits are profound. A manufacturer focused solely on large-scale mining trucks might face a different go-to-market timeline and infrastructure challenge compared to an OEM targeting compact construction loaders or agricultural tractors. Similarly, a fleet operator must weigh the infrastructure readiness of a construction site against the roaming requirements of a farming enterprise. Our full report dissects these application-specific revenue dynamics to guide precise targeting and resource allocation.
The Competitive Battleground: Titans and Disruptors
The market structure is characterized by high concentration, with the top three and top five players commanding a significant majority of the market share. This oligopolistic environment is intensifying as established heavy machinery giants leverage their scale and dealer networks, while agile entrants and tech-focused manufacturers target underserved niches or disrupt traditional value propositions. Understanding the strategic positioning, product launch cadence, and partnership strategies of these key players is essential for competitive benchmarking.
Leading the Charge: Established Heavyweights
The competitive arena is dominated by legacy industrial powerhouses that have aggressively pivoted toward electrification. Volvo Construction Equipment , based in Gothenburg, Sweden, stands out as a vanguard of the transition. Volvo CE has been aggressively expanding its portfolio of full electric construction equipment, ranging from midsize excavators like the EC230 to wheel loaders such as the L120, and articulated haulers. Their recent moves underscore a commitment to zero-emission leadership; at Bauma 2025, Volvo CE unveiled the world-first battery-electric articulated haulers, the A30 Electric and A40 Electric, with serial production commencing and initial deliveries targeted for 2026. Furthermore, they debuted the L120 Electric wheel loader and updated the EC230 Electric in North America. In May 2026, Volvo CE announced a strategic collaboration with Hitachi Energy to accelerate zero-emission construction sites, highlighting the critical intersection of equipment manufacturing with power supply and charging solutions.
Hitachi Construction Machinery , headquartered in Tokyo, Japan, is another formidable player deeply embedded in the electric excavator space. They have introduced new zero-emission electric excavators, including the ZX55U-6EB and ZX85-6EB models, aimed at battery-powered construction applications. Their innovation extends beyond the powertrain; in March 2026, Hitachi Construction Machinery began testing a machine voice control prototype with DIMAAG at CONEXPO-CON/AGG, signaling a convergence of electrification with advanced operator-assist and autonomous technologies.
Caterpillar Inc. , the US manufacturing giant, continues to push the envelope in electric-drive and hybrid electric construction machinery. Their portfolio spans loaders, excavators, dozers, and articulated trucks adapted for mining and heavy-duty applications, leveraging their global scale to influence industry standards. Liebherr from Germany is renowned for producing high-capacity electric excavators, such as the R 9200 E, and electric mining machinery for construction and quarrying operations, demonstrating that electrification is viable even for large-scale, heavy-duty requirements.
Komatsu Ltd. , also based in Tokyo, provides electric excavators like the PC210E and articulated trucks with full electric drive systems for construction, mining, and industrial use. John Deere , the American agri-machinery leader, is extending its electric reach with loaders, excavators, compact machinery, and hybrid-electric construction equipment for commercial and municipal projects. Meanwhile, SANY Group in Changsha, China, is leveraging its manufacturing prowess to offer comprehensive electric dump trucks, excavators, and heavy machinery for mining and large-scale hauling, positioning itself as a cost-competitive force in the global market. On the construction equipment side, CNH Industrial N.V. (London, UK) is manufacturing purpose-built electric construction equipment, including the CASE 580EV electric backhoe loader. Doosan Infracore in Seoul, South Korea, contributes to the heavy end with large electric excavators like the DX300LC for construction and mining. A notable disruptor in this space is Hevi , a China-based pioneer in all-electric heavy equipment solutions, offering electric wheel loaders and excavators designed for industrial and construction use.
Electric Utility Vehicles Market
Agricultural Electrification Leaders
The agriculture segment features a distinct competitive set, blending traditional tractor manufacturers with innovative ag-tech startups. AGCO Corporation , based in Suwanee, Georgia, is a key provider of electric tractors and agricultural machinery for farm and off-road electric vehicle applications. CLAAS KGaA mbH in Germany manufactures electric tractors and farm vehicles for modern agricultural operations. Kubota Corporation in Osaka, Japan, is a major supplier of electric tractors and agricultural machinery for farming and off-highway use. Mahindra and Mahindra Ltd. in India is a significant producer of electric tractors and farm vehicles for agricultural applications, capitalizing on the large domestic and export markets. Rounding out the ag-innovators is Monarch Tractor in the United States, a developer and manufacturer specializing in electric tractors for agricultural and off-road use, often highlighting smart, autonomous-ready electric platforms.
Navigating this competitive landscape requires a granular understanding of each player's supply chain vulnerabilities, pricing strategies, after-sales service models, and regional deployment strengths. The full report provides a detailed competitive benchmarking matrix and company-specific strategic assessments that are vital for M&A targeting, partnership identification, and competitive response planning.
Market Dynamics: The Forces Shaping the Velocity of Adoption
The trajectory of the electric heavy machinery market is not solely determined by manufacturer output; it is the result of a complex interplay of regulatory, infrastructural, and economic forces. Several macro-trends are acting as powerful accelerants, while others present enduring challenges that must be managed.
Regulatory and Macro Drivers: The Push for Zero Emission
Regulatory pressure is arguably the most potent catalyst for electrification in construction and mining. The EU and UK emissions requirements and decarbonization targets are accelerating adoption, particularly for electric articulated haulers in quarrying and mining. The A30 Electric and A40 Electric from Volvo CE entering serial production in 2026 is a direct response to this regulatory urgency. Beyond vehicle tailpipe emissions, there is a global shift toward carbon-neutral operations in mining and construction, supported by ISO 14001 standards and national green procurement policies that increasingly require zero-emission equipment for public and private projects.
Zero-emission regulations and stricter environmental standards for construction and mining sites are driving demand for battery-electric equipment worldwide. Furthermore, EU emissions reduction targets for heavy machinery are prompting manufacturers to prioritize full-electric models over hybrid or diesel alternatives in construction applications. This regulatory landscape effectively closes the door on incremental diesel improvements and forces a capital allocation shift toward electrification.
Economic and Infrastructure Fractures
Despite the regulatory tailwinds, economic and infrastructural realities pose significant friction. Battery and charging infrastructure costs remain the primary driver increasing the upfront price of electric construction and mining vehicles compared to conventional models. This price premium requires buyers to rationalize through total cost of ownership calculations, factoring in fuel savings, maintenance reductions, and regulatory compliance benefits. The availability of robust charging solutions, especially for large mining haul trucks or fleets of construction equipment on remote sites, remains a critical dependency. This is why partnerships like the one between Volvo CE and Hitachi Energy are so strategically significant; they acknowledge that the vehicle is only as useful as the power ecosystem surrounding it.
Strategic Implications and the Case for Deep Intelligence
As we stand in 2026, the market is transitioning from the "early adopter" phase to the "early majority" phase. The decisions made today regarding fleet procurement, OEM partnerships, technology investments, and geographic expansion will lock in competitive advantages or disadvantages for the remainder of the decade. The revenue projections through 2032 indicate that the window for establishing leadership in specific segments is narrowing.
For OEMs, the strategic questions are acute: How do you balance investments between full electric and hybrid to manage cash flow while meeting regulatory timelines? Which product segments offer the fastest path to commercial viability in your region? How do you integrate charging and energy management into your value proposition? For fleet operators and mining companies, the calculus involves infrastructure CapEx, downtime management during the transition, and securing supply of electric machines in a concentrated market. For investors and suppliers, identifying the winners in this high-growth, high-consolidation environment requires precise data on segment profitability, technology roadmaps, and procurement trends.
This article has outlined the macro contours of the Electric Vehicles for Construction, Agriculture, and Mining market. The 18.5% CAGR, the dominance of battery-electric technologies, the leadership of global giants alongside rising challengers, and the binding nature of emissions regulations collectively paint a picture of an industry in ferment. However, to translate this high-level vision into actionable strategy, decision-makers require the granular intelligence that only a comprehensive market study can provide.
Unlock the Full Strategic Picture
The insights presented here represent the surface-level currents of a deep and complex market. The full PW Consulting report, Electric Vehicles for Construction, Agriculture and Mining Market (2026-2032) , delves far deeper, offering the detailed segmentation splits, regional market revenue distributions, application-specific forecasts, competitive share analysis, and scenario modeling that your team needs to thrive.
Inside the complete report, you will find:
- Detailed Market Size and Forecast by Region: Precise revenue trajectories for North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, enabling geo-specific capacity planning and market entry strategies.
- Granular Segmentation by Type and Application: Exact revenue breakdowns and growth rates for Battery Electric, Fuel Cell, and Plug-in Hybrid vehicles across Construction, Agriculture, and Mining, allowing you to pinpoint your highest-value niches.
- Comprehensive Company Profiles and Competitive Dynamics: In-depth analysis of the strategies, product portfolios, recent developments (including 2025-2026 launches and partnerships), and market positioning of all key players, from Volvo CE and Caterpillar to SANY, John Deere, and emerging ag-tech innovators.
- Market Drivers, Restraints, and Opportunities: A thorough examination of the regulatory landscape, cost structures, charging infrastructure challenges, raw material dependencies, and the specific opportunities within green procurement and carbon-neutral initiatives.
- Strategic Recommendations: Actionable guidance for stakeholders to navigate the transition, mitigate risks, and capture growth in this rapidly evolving sector.
The heavy machinery market is electrifying at a pace that rewards the prepared. Do not rely on aggregate estimates alone. Secure the detailed market intelligence necessary to make confident, data-driven decisions in 2026 and beyond. Contact PW Consulting or access the full report to obtain the complete dataset and strategic analysis that will define your success in the electric era of construction, agriculture, and mining.
For detailed analysis of this topic, please visit the official page: Electric Vehicles for Construction, Agriculture and Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


