



PW Consulting: Steel Powder Market Hits $291M in 2025, 6.4% CAGR to 2032

Steel Powder Market Outlook 2026: Navigating Growth, Constraints, and Competitive Shifts
The global steel powder market stands at a pivotal inflection point as it enters the 2026–2032 forecast window. After tracking steady expansion from 2020 through 2025, the sector has now crossed the three-hundred-million-dollar threshold in annual revenue, positioning itself for a growth trajectory that projects a compound annual rate of 6.4 percent through the end of the decade. This is not merely a cyclical rebound. It reflects structural demand shifts across high-value manufacturing, evolving feedstock economics, and a regulatory environment that is actively redrawing trade and compliance boundaries. For executives, procurement leaders, and strategy teams, the coming year will reward those who move beyond headline growth figures and build operational playbooks rooted in granular market intelligence.
PW Consulting’s newly released Steel Powder Market research was designed precisely for that moment. Rather than functioning as a static data repository, the study translates historical momentum, forward-looking projections, and competitive signaling into decision-ready frameworks. As organizations calibrate capital allocation, supply chain resilience, and product roadmap priorities for 2026, the report offers a calibrated view of where value is being created, where margin pressure is intensifying, and which strategic moves will separate category leaders from followers.
A Market Crossing the Threshold: From Recovery to Structural Expansion
Over the past half-decade, steel powder revenue has demonstrated consistent upward movement, with annual figures climbing from the mid-two-hundred-million range into the high two hundreds before decisively breaking through three hundred million. This progression reflects more than recovered demand after earlier market softening. It underscores the deepening integration of powder metallurgy and additive manufacturing into core production strategies across multiple industrial verticals. The 6.4 percent forward CAGR embedded in our forecast model signals that momentum will not plateau; instead, it will be shaped by competing forces of capacity investment, feedstock optimization, and regional regulatory recalibration.
Importantly, headline growth masks divergent underlying dynamics. The transition from raw volume expansion to quality- and application-specific differentiation is already underway. Suppliers that can align particle morphology, purity thresholds, and metallurgical consistency with the exacting requirements of advanced manufacturing processes are capturing disproportionate value. Meanwhile, traditional commodity-oriented segments face margin compression as input cost volatility and export control mechanisms reshape cost structures. Understanding where these shifts are concentrated—and how they interact with regional demand patterns—is essential for building resilient sourcing and pricing strategies in 2026.
What the Research Delivers: Actionable Intelligence, Not Just Data
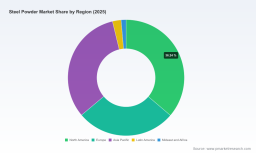
Strategic research earns its place on the executive dashboard when it converts complexity into action. Our Steel Powder Market study is structured to serve that purpose across multiple decision layers. The report opens with a detailed market sizing and forecasting architecture that traces historical performance and projects forward through the end of the forecast horizon, allowing readers to test sensitivity scenarios against base, optimistic, and constrained demand pathways. Segmentation analysis is organized around product type, application vertical, and geographic footprint, with each dimension evaluated through the lens of demand drivers, substitution risks, and pricing behavior rather than isolated share percentages.
The competitive landscape section moves beyond roster mapping to assess how key players position themselves across technology platforms, capacity footprints, and end-market focus. Recent corporate activity is examined not as isolated news items but as strategic signals: capacity expansions that target high-purity grades for demanding applications, product launches that bridge material categories, and business model shifts that redirect feedstock strategies toward recycled scrap integration. These developments are contextualized within broader industry dynamics, including regional shipment trends, feedstock dependency patterns, and the evolving relationship between traditional powder metallurgy and additive manufacturing roadmaps.
Readers will also find dedicated analysis of the regulatory and trade environment that is actively reshaping market access and cost structures. Starting in early 2026, new export licensing requirements in China, the operational rollout of EU carbon border adjustment mechanisms, and ongoing tariff developments affecting specialized inputs have introduced fresh compliance layers and cost variability. The report evaluates how these measures intersect with supply chain geography, sourcing alternatives, and margin defense strategies, providing a structured view of which exposures are manageable and which require proactive redesign.
Competitive Landscape: Strategic Positioning and Capability Divergence
The steel powder market is characterized by a concentrated core of globally active specialists alongside regional and application-focused participants. The top tier commands meaningful share, with the three largest firms accounting for roughly forty-five percent of total revenue and the five largest approaching sixty percent. That concentration does not imply uniformity; it reflects a market where capability depth, technology licensing, and end-market specialization increasingly determine competitive advantage.
Höganäs continues to anchor its global presence through a broad portfolio spanning iron, steel, and stainless steel powders tailored for powder metallurgy, additive manufacturing, and automotive applications. Recent operational moves underscore a deliberate focus on high-purity grades for demanding end markets, including announced capacity expansion at its Swedish gas atomization facility to boost output of stainless steel and nickel-based powders serving aerospace and medical applications. Outokumpu has taken a distinctly circular-economy-aligned path, developing customizable stainless steel and nickel-based alloy powders derived from recycled scrap generated by its flat products operations. Its recent expansion into aerospace and aviation, marked by the first delivery of a specialized stainless steel powder grade for advanced 3D printing, signals a push into higher-specification segments where traceability and material consistency command premium positioning.
Carpenter Technology Corporation maintains a premium orientation across stainless steels, alloy steels, and tool steel powders, serving additive manufacturing, powder forging, metal injection molding, and hot isostatic pressing workflows. Its emphasis on application-engineered materials positions it at the intersection of performance requirements and advanced processing. Sandvik’s Osprey series, encompassing tool and stainless steel powders, reinforces its focus on additive manufacturing and powder metallurgy, with recent introductions such as the Osprey MAR 55 bridging maraging steels and tool steels to offer greater versatility across demanding component designs. Kobe Steel and Laiwu Iron & Steel Group Powder Metallurgy Co., Ltd. continue to serve powder metallurgy applications with established production capabilities, while Rio Tinto has extended its materials portfolio into steel powders developed for additive manufacturing at its RTFT facility. Kymera International and Pometon SpA round out the landscape with stainless steel and metal powder offerings that support powder metallurgy workflows across diverse industrial contexts.
The strategic implication is clear: the market is fragmenting along lines of technology specificity, feedstock strategy, and end-market certification requirements. Companies that treat steel powder as a commoditized input are encountering structural headwinds; those that invest in grade customization, process consistency, and application-specific qualification are converting technical capability into pricing power and customer lock-in.
Forces Reshaping the 2026 Operating Environment
The 2026 decision environment is defined by the intersection of demand evolution, regulatory recalibration, and feedstock economics. On the demand side, advanced manufacturing continues to expand the addressable base for engineered powders, yet regional shipment data from recent industry reporting indicates that not all segments are moving in lockstep. North American iron and steel powder shipments declined by approximately six percent in the prior year amid a market downturn affecting metal injection molding and additive manufacturing volumes, a reminder that aggregate growth narratives can obscure localized softness and segment-specific volatility. This divergence reinforces the need for localized demand assessment rather than reliance on global averages when planning procurement and production schedules.
Regulatory and trade dynamics are adding new layers of complexity. The implementation of an export licensing system in China for certain steel products, including powders, introduces compliance friction and potential supply reconfiguration for buyers dependent on transboundary material flows. Simultaneously, the EU carbon border adjustment mechanism is operationalizing a certificate-based cost structure that will affect steel and aluminum import economics, prompting a reassessment of sourcing geography and total landed cost calculations. In parallel, tariff actions on specialized inputs such as tungsten products have continued to evolve, influencing cost structures for alloyed powder formulations that rely on such additions. These developments are not peripheral; they are becoming central variables in supplier qualification, contract structuring, and inventory strategy.
Feedstock strategy is emerging as a critical differentiator. With recycled scrap serving as the primary feedstock base for steel powder production, companies that can secure consistent scrap streams, control impurity profiles, and integrate scrap sourcing with existing product lines are building durable cost and quality advantages. The linkage between flat products operations and powder output, exemplified by scrap-derived powder development, illustrates how vertical integration and material circularity can reinforce both margin stability and sustainability positioning. In a market where compliance documentation, traceable feedstock, and metallurgical consistency increasingly influence procurement decisions, feedstock strategy is shifting from operational detail to strategic lever.
Why This Report Matters for 2026 Decision-Making
As organizations step into the 2026 planning cycle, the steel powder market presents a paradox: broad growth visibility coexists with sharp divergence in segment performance, regulatory exposure, and competitive capability. Navigating that paradox requires more than top-line forecasts. It demands a clear map of where demand is becoming application-specific, where cost pressures are intensifying, and where strategic positioning is creating defensible advantage.
Metal Powder Market
PW Consulting’s Steel Powder Market research is built to bridge that gap. It equips leadership teams with a structured view of market sizing and trajectory, a nuanced breakdown of segmentation dynamics across product types, applications, and regions, and a competitive analysis that connects corporate moves to underlying strategic logic. It also integrates the regulatory and feedstock forces that are actively reshaping cost structures and supply options, ensuring that strategy discussions are grounded in the operating realities of the current year.
The full report contains the detailed segmentation architectures, forecast sensitivities, competitive capability assessments, and regional demand analyses that turn high-level trends into executable plans. For executives evaluating capacity commitments, sourcing diversification, product roadmap investments, or market entry timing, the complete dataset and accompanying analytical frameworks provide the necessary resolution to move from assumption to evidence-based action.
How to Apply the Findings
- Align procurement and inventory strategy with regional demand divergence and regulatory exposure, rather than relying on global averages or historical shipment patterns alone.
- Evaluate supplier partnerships through the lens of grade customization, feedstock consistency, and certification readiness, recognizing that application-specific qualification is increasingly the primary source of pricing resilience.
- Incorporate trade and compliance variables into total cost modeling, including export licensing implications, carbon adjustment mechanics, and tariff-sensitive input dependencies that affect alloyed powder formulations.
- Use the segmentation and forecasting architectures to stress-test capacity and capital allocation decisions against base, upside, and constrained scenarios, ensuring flexibility in a market where segment performance is decoupling from aggregate growth.
- Leverage competitive capability analysis to identify white-space opportunities in high-purity, aerospace, medical, and advanced additive manufacturing segments where material consistency and traceability command strategic premium.
The steel powder market is not simply expanding; it is restructuring around quality, traceability, regulatory resilience, and application-specific engineering. The organizations that best understand those shifts will be positioned to secure supply, protect margins, and capture growth where it is most durable. PW Consulting’s full Steel Powder Market research provides the depth required to execute that strategy with confidence.
Steel Powder Market
For detailed analysis of this topic, please visit the official page: Steel Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


