



PW Consulting Reports Dairy Market to Hit $344.8M by 2032 with 6.6% CAGR

Navigating the Dairy Ingredients Horizon: Strategic Imperatives for 2026 and Beyond
The global dairy ingredients sector stands at a critical inflection point as it moves through the mid-2020s. For executives, procurement leaders, and strategic planners, the decisions made in 2026 will define competitive positioning throughout the decade. Understanding where the market has been, where it is heading, and who is shaping its trajectory is no longer a matter of routine monitoring. It requires a rigorous, forward-looking intelligence framework. PW Consulting’s latest Dairy Ingredients Market study delivers that framework, translating complex supply dynamics, shifting demand patterns, and rapidly evolving trade conditions into actionable strategy.
Dairy Ingredients Market
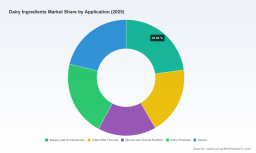
Over the past five years, the industry has experienced a period of measured expansion punctuated by supply chain recalibration, regulatory shifts, and changing end-user expectations. Total industry revenue climbed from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting steady consolidation of demand across multiple application verticals. The trajectory points toward continued growth, with market valuation projected to reach 237.36 million USD in 2026 and advance to 344.8 million USD by 2032. This progression corresponds to a compound annual growth rate of 6.6 percent across the 2026 through 2032 forecast window. Such a macro outlook signals a fundamentally resilient category, but the real strategic value lies beneath the headline figures: in how value is distributed across ingredient types, how regional supply balances interact with trade policy, and which application segments are generating the strongest margin discipline.
Why 2026 Demands a Recalibrated Strategic View
The year 2026 is not a simple continuation of recent patterns. Several structural forces are converging to reshape how dairy ingredients are sourced, formulated, priced, and distributed. On the regulatory front, the Food and Drug Administration’s July 2025 proposal to revoke 18 standards of identity for dairy products, including multiple cheese and milk variants, has introduced new considerations around labeling, formulation compliance, and ingredient substitution. For manufacturers and formulators, this creates both flexibility and ambiguity, requiring closer coordination between regulatory affairs, R&D, and procurement teams.
At the same time, trade dynamics are shifting quickly. Recent reporting from the International Dairy Foods Association in February 2026 highlighted landmark new trade agreements with Taiwan that fully eliminate dairy tariffs, materially expanding U.S. dairy ingredients market access. The same reporting noted additional accords with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, collectively boosting export potential. These developments are unfolding alongside U.S. Dairy Export Council data from January 2026 showing that 2024 U.S. dairy exports recorded increased volumes on a milk-fat basis while experiencing declines on a skim-solids basis. The divergence underscores a nuanced export environment where composition, destination, and commodity mix matter as much as total shipment volume.
On the demand side, a McKinsey dairy industry survey from April 2026 found rising demand for dairy ingredients even as cost pressures and margin challenges persist across the value chain. This combination of resilient demand and compressed profitability is precisely the environment in which granular market intelligence becomes indispensable. Executives cannot rely on aggregate growth narratives alone; they must understand which ingredient categories are absorbing volume, which applications are commanding premium positioning, and how competitive intensity is evolving among established producers and specialized suppliers.
Inside the Research: What This Study Delivers
PW Consulting’s Dairy Ingredients Market report is structured to move beyond surface-level forecasts and into the operational detail that decision-makers actually use. The study is built around several core analytical pillars:
- Historical reconstruction and forward modeling covering the 2020 to 2025 historical window and a detailed 2026 to 2032 forecast period, with revenue expressed in million USD and a documented 6.6 percent CAGR.
- Segment-level analysis across ingredient types, end-use applications, and regional markets, designed to reveal where growth is concentrated and where competitive saturation is most pronounced.
- Competitive landscape assessment profiling leading producers and suppliers, evaluating their product portfolios, geographic reach, formulation capabilities, and strategic positioning within the broader ingredients ecosystem.
- Market structure evaluation examining concentration metrics and the balance between diversified global players and specialized regional operators, helping buyers and investors gauge pricing power, supply resilience, and partnership options.
- Regulatory, trade, and standards context integrating developments such as FDA identity standard revisions, ADPI-maintained industry standards for U.S.-produced dairy ingredients including whey, lactose, and milk proteins, and the latest trade agreement outcomes that affect market access and cost structures.
- Recent industry milestones capturing events such as the April 2026 ADPI Annual Conference in Chicago and other sector gatherings that shape innovation direction, foodservice application trends, and cross-functional collaboration across the ingredients community.
The report is deliberately built for practical use. Rather than stopping at high-level trends, it connects demand signals to ingredient functionality, links regional supply dynamics to trade policy outcomes, and frames competitive moves within the context of margin discipline and formulation innovation. This integrated approach allows readers to assess not only where the market is going, but how their own sourcing strategies, product development roadmaps, and partnership decisions should adapt in response.
Competitive Landscape: Who Is Shaping the Market
The dairy ingredients arena is populated by a mix of large, globally active dairy organizations and focused ingredient specialists. The competitive field spans North American producers with strong domestic supply chains, European exporters with broad international distribution, and formulation-oriented companies that provide custom concentrates and blended powders tailored to specific food and beverage applications. Rather than a single dominant architecture, the market operates as a layered ecosystem in which scale, specialization, and application expertise create distinct competitive advantages.
Several organizations stand out through the breadth of their ingredient portfolios and their presence across multiple end markets. Agropur, headquartered in Montreal, Canada, focuses on dairy ingredient production including whey, milk protein, and casein for food and beverage applications. Arla Foods, based in Viby J, Denmark, provides dairy ingredients such as milk powders, whey proteins, and lactose for global food and nutrition markets. Lactalis, located in Bourgbarre, France, offers dairy ingredients including milk powders, whey, and casein for global food and beverage industries. Saputo Cheese USA, with operations linked to Montreal, Canada, supplies whey powders, milk proteins, and other dairy ingredients for food production. These organizations illustrate how major dairy groups leverage ingredient divisions to serve a wide range of industrial and consumer-facing applications.
Alongside these broader players, a set of specialized suppliers adds critical depth to the market. Bluegrass Ingredients, Inc., based in Kentucky, United States, specializes in custom dairy concentrates, blended powders, and whey-based ingredients for food formulation. California Dairies, Inc., in Tulare, California, produces and supplies milk powders, whey products, and other dairy ingredients for industrial and food applications. Dairy Farmers of America, headquartered in Roseville, Illinois, supplies milk powder, whey, casein, and other dairy ingredients for dairy products, food manufacturing, and nutrition. Glanbia Nutritionals, located in La Crosse, Wisconsin, manufactures whey protein isolates, concentrates, and other dairy protein ingredients for sports nutrition and food products. Land O’Lakes, based in Arden Hills, Minnesota, provides milk powders, whey products, and functional dairy ingredients for food processing and nutrition. Leprino Foods, in Denver, Colorado, produces cheese powders, whey, and other dairy ingredients used in food manufacturing and baked goods. MCT Dairies, based in Millburn, New Jersey, distributes and supplies dairy ingredients across global markets for food and beverage applications. Proliant Dairy Ingredients, in Ames, Iowa, specializes in dairy protein ingredients, whey products, and milk proteins for food and industrial use. Schreiber Foods, headquartered in Green Bay, Wisconsin, manufactures dairy ingredients such as milk powders, whey, and casein for beverage and food industries.
Together, these companies represent the operational core of an industry that must continuously balance scale efficiency with formulation precision. Their product ranges, application focus, and geographic footprints shape how buyers evaluate supply reliability, technical support, and long-term partnership potential. The full report provides a more detailed competitive mapping, assessing how these organizations are positioned relative to one another across ingredient types, end-use segments, and regional markets, while preserving the analytical depth needed to support sourcing strategy, partnership evaluation, and competitive benchmarking.
Market Dynamics: Regulation, Trade, and Demand Signals
A durable understanding of dairy ingredients requires attention to the forces that alter cost structures, market access, and formulation choices. The July 2025 FDA proposal to revoke 18 standards of identity for dairy products has introduced a meaningful regulatory variable. For ingredient suppliers and end-product manufacturers alike, changes to identity standards can affect labeling requirements, ingredient substitution pathways, and the competitive positioning of specific product forms. The strategic implication is not simply compliance; it is the opportunity to reconsider formulation architectures and ingredient blending strategies in light of broadened flexibility.
Worldwide Infant Dairy Ingredients Market
Trade policy is equally consequential. The February 2026 announcement of new agreements with Taiwan, alongside expanded collaboration with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, signals a widening aperture for export-oriented growth. These agreements can reduce tariff barriers, improve destination-market competitiveness, and reshape the relative attractiveness of different sourcing origins. At the same time, the U.S. Dairy Export Council’s January 2026 data reminds the market that export performance is not uniform. Increased milk-fat basis volumes alongside skim-solids declines indicate that commodity composition, end-use demand, and pricing dynamics differ significantly by product stream. Organizations that treat dairy ingredients as a single homogeneous category risk misreading both opportunity and exposure.
On the demand side, the April 2026 McKinsey survey’s finding of rising ingredient demand amid cost and margin pressure captures the current tension. Buyers are seeking functional reliability, consistent supply, and formulation versatility, while suppliers are navigating input volatility and the need to protect profitability. In this environment, industry standards maintained by organizations such as the American Dairy Products Institute play an important role in anchoring quality expectations for U.S.-produced dairy ingredients including whey, lactose, and milk proteins. The June 2026 reinforcement of those standards, alongside the April 2026 ADPI Annual Conference’s focus on innovation and foodservice applications, suggests that technology, consistency, and application performance remain central competitive differentiators.
What Strategic Decision-Makers Need to Know Next
The macro picture is clear enough to establish confidence in continued growth, but the strategic decisions that matter most are segmental, operational, and partnership-driven. Which ingredient categories are expanding fastest in value terms? Where are application segments generating the strongest demand pull, and which are facing substitution risk or margin compression? How do regional supply balances interact with the new trade agreements to alter sourcing geography? Which competitors are building advantage through formulation capability, and which are competing primarily on scale and distribution?
These are the questions that determine whether an organization simply rides broad market growth or actively captures disproportionate value from it. The answers require a detailed view of segmentation splits, regional performance patterns, application-level demand intensity, and competitive positioning that cannot be responsibly compressed into a single summary. PW Consulting’s full Dairy Ingredients Market study is built to provide exactly that depth, enabling procurement teams, R&D leaders, and corporate strategists to align their plans with the most current structural reality of the market.
For executives preparing 2026 initiatives and longer-range plans through 2032, the study offers a structured intelligence base: historical trajectory, forward projections anchored to a 6.6 percent CAGR, segment and regional breakdowns, competitive profiling, and dynamic context drawn from the latest regulatory, trade, and industry developments. The objective is not to overwhelm with data, but to give decision-makers the clarity needed to prioritize investments, manage supply risk, and position products where demand and margin discipline intersect.
The full report is available for review and acquisition through PW Consulting’s market research portal. Readers seeking a complete segment-by-segment view, detailed competitive mapping, and region-specific growth pathways are encouraged to access the source page for the complete intelligence package. In a market where aggregate growth can mask important local and segmental shifts, that level of detail is what turns insight into advantage.
For detailed analysis of this topic, please visit the official page: Dairy Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


