



PW Consulting: Wellington Boots Market to Hit $1,842.67M by 2032 at 4.8% CAGR

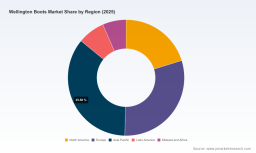
Strategic Intelligence in the Wellington Boots Market: A 2026 Outlook
The global Wellington boots market stands at a critical inflection point as enterprises navigate shifting trade dynamics, material innovation, and evolving consumer expectations. At PW Consulting, we recognize that stakeholders across agriculture, industrial manufacturing, retail, and footwear distribution require more than surface-level trends. They need a rigorously validated, forward-looking framework that translates historical momentum into actionable decision pathways. Our newly released Wellington Boots Market research report delivers precisely that: a comprehensive intelligence asset engineered to support strategic planning throughout the 2026-2032 forecast horizon.
This introductory analysis outlines the strategic rationale behind the study, highlights the operational architecture of the full report, and frames the competitive and macroeconomic forces that will shape procurement, product development, and market entry decisions over the coming years. Readers seeking complete quantitative breakdowns, granular regional demand matrices, and detailed competitor benchmarking will find the full intelligence document essential. The following preview establishes the analytical foundation while directing quantitative deep dives to the complete release.
Market Trajectory and the Strategic Imperative for 2026
The Wellington boots sector has demonstrated consistent expansion across the 2020-2025 historical window, reflecting structural demand from professional working environments, agricultural operations, and the growing consumer preference for weather-ready functional footwear. Our analysis places the 2025 revenue baseline at approximately USD 1,330.0 million, with forward trajectory modeling indicating sustained growth through the end of the decade. The forecast period projects a compound annual growth rate of 4.8 percent, positioning the market to approach USD 1,842.7 million by 2032.
Such trajectory is not merely a function of incremental consumption. It is the cumulative result of durable end-use demand, public and private procurement cycles, and the ongoing repositioning of Wellington-style footwear as both utilitarian equipment and lifestyle-adjacent product. For executives evaluating capacity planning, inventory allocation, or geographic expansion, the central strategic question is no longer whether the category will grow, but where growth concentrates, which material platforms will sustain margin integrity, and how trade policy reshapes sourcing economics. Our report answers these questions through segmented modeling that isolates demand drivers, pricing elasticity, and channel behavior without oversimplifying the operational complexity on the ground.
The forecast architecture covers an eight-year horizon from 2026 through 2032. This duration is deliberate. Short-term projections often miss inflection events such as tariff adjustments, raw material cost shocks, or product lifecycle transitions. An eight-year span enables leadership teams to test scenario-based strategies, evaluate capital deployment timing, and align product roadmaps with multi-cycle procurement calendars. By anchoring the study in historical data from 2020 onward and extending projections with scenario-tested assumptions, the report provides a reliable scaffold for board-level discussions and operating-plan development.
What the Report Delivers: Operational Content for Decision-Makers
Comprehensive market intelligence must translate into executable insight. The Wellington Boots Market research is structured to serve cross-functional teams, from procurement and supply chain leadership to marketing, product development, and corporate strategy. Rather than offering a single aggregate figure, the study decomposes the market into analytically meaningful dimensions that correspond to real operational decisions.
The report provides a detailed examination of the material composition landscape, evaluating how different manufacturing substrates influence cost structures, performance characteristics, and end-user segmentation. It also maps application-driven demand patterns, distinguishing between professional agricultural usage, household and lifestyle consumption, industrial manufacturing environments, outdoor recreation, and additional specialized deployments. This segmentation lens is critical because each vertical exhibits distinct purchasing cycles, durability requirements, price sensitivity, and channel preferences.
Geographically, the study assesses regional demand dynamics to help leadership teams identify where volume concentration is strongest, where growth momentum is accelerating, and where regulatory or logistics constraints may alter entry strategies. The analysis integrates market concentration metrics to contextualize competitive rivalry and distribution leverage, giving stakeholders a clear view of how consolidated the landscape is and where white space or partnership opportunities may reside.
Beyond structural segmentation, the report embeds forward-looking assessments of pricing architecture, supply chain exposure, and product innovation trajectories. The inclusion of scenario modeling enables users to evaluate how changes in raw material costs, freight economics, or duty regimes could shift margin profiles and sourcing strategies. This is particularly valuable in a category where input costs and trade policy are actively reshaping manufacturer pricing behavior and retailer purchasing decisions.
To support implementation, the study incorporates a structured competitive benchmarking section that examines product architecture, positioning, and strategic moves among leading participants. This component is designed to help organizations compare value propositions, anticipate competitive responses, and identify areas where differentiation must be driven by construction quality, material innovation, or channel alignment rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Recent Moves
The Wellington boots market is shaped by a diversified set of participants spanning heritage craftsmanship, professional-grade work and fishing footwear, industrial protective equipment, and consumer-oriented lifestyle products. Our competitive analysis examines how these companies construct their offerings and where strategic activity is intensifying.
Le Chameau, headquartered in Normandy, France, exemplifies a craftsmanship-led approach with iconic handcrafted rubber Wellington boots built around a Chamolux rubber upper and dual-material construction designed for durability and weather resistance. Its recent retail partnership activity in 2025, including the stocking of new Fairfax collaboration Wellington boots at major retailers, signals a deliberate extension into broader consumer distribution while preserving a premium product identity.
Grundéns, based in Canada, focuses on professional-grade rubber and neoprene fishing and work boots, with its Crewman model engineered for commercial durability. The company's 2025 product launch of the Crewman boot after nine months of field testing across Alaska, the Canadian Maritimes, Maine, and Europe demonstrates a testing-intensive development model aligned with demanding environmental and operational conditions.
Xtratuf, operating in the United States under Rocky Brands ownership, maintains a strong presence with durable waterproof rubber work and fishing boots. The brand's positioning reflects a practical, performance-first portfolio that supports commercial and recreational use cases where waterproof integrity and rugged construction are paramount.
Rubbermaid, headquartered in Atlanta, Georgia, contributes a commercial-grade rubber boots and protective footwear line aimed at industrial and facility use. Its offering underscores how facility management, hygiene, and workplace safety requirements shape demand for durable rubber products in institutional settings.
Bogs Footwear, based in Portland, Oregon, emphasizes waterproof rubber and seamless Wellington-style boots for farm, work, and outdoor use. Its construction philosophy highlights the consumer and professional overlap in the category, where comfort and weather protection intersect.
Blundstone, headquartered in Hobart, Australia, offers rugged rubber and leather Wellington boots for work and casual use. The combination of material types reflects a dual-purpose strategy that bridges utility and everyday wear, appealing to users who want durability without sacrificing style versatility.
Aigle, from France, markets unisex rubber Wellington boots with lugged soles and dual-material uppers for outdoor and adventure use. Its design language aligns with the broader outdoor recreation segment, where traction, weatherproofing, and aesthetic coherence matter to active consumers.
Dunlop Boots, based in the United Kingdom, focuses on industrial and professional rubber boots with chemical-resistant features. This specialization illustrates how sector-specific performance requirements, such as chemical handling and workplace safety compliance, drive product engineering decisions and segment-specific demand.
Rockland, operating in the United States, addresses the affordable rubber Wellington boot segment for general consumer and work applications. Its positioning demonstrates that accessibility and broad functionality remain important demand anchors, particularly where price sensitivity is high and usage expectations are standardized.
Tingley Rubber, also based in the United States, supplies durable rubber overshoes and Wellington-style footwear for safety and industrial use. Its product focus reinforces the role of protective footwear in occupational environments where overshoes and specialized rubber constructions serve practical compliance and contamination-control functions.
Together, these participants illustrate a market where differentiation is increasingly defined by material engineering, durability validation, channel strategy, and brand positioning across professional and consumer contexts. The report evaluates these dynamics with a structured competitive framework, enabling clients to benchmark their own product strategies and anticipate how rivals may respond to cost pressures, regulatory changes, and evolving consumer preferences.
Macroeconomic and Regulatory Dynamics Shaping the 2026 Decision Environment
Strategic planning in the Wellington boots market cannot be separated from the broader operating environment. Several interconnected forces are actively reshaping sourcing economics, product development priorities, and margin management.
Chelsea Bootie Market
Trade and duty policy has emerged as a central variable. Recent U.S. customs actions have applied a 37.5 percent ad valorem duty under HTS 6401.99 for waterproof rubber boots originating from China under Executive Order 14389, with effect from February 2026. In parallel, broader U.S. footwear import tariffs introduced in April 2025 raised duties for Vietnamese boots by 46 percent and Indonesian boots by 32 percent, with duties reaching up to 145 percent on certain Chinese imports. These measures directly affect Wellington boots supply chains by altering landed cost calculations, reshaping sourcing geography, and creating pressure on manufacturers and distributors to reassess supplier mixes and inventory positioning.
On the European and UK side, the HS Code 6401.99.00 classification for rubber Wellington boots carries EU import duties of 16 percent and UK duties of 16 percent under 2026 HTS revisions. For companies operating transatlantic supply chains or evaluating European distribution footprints, these duty levels influence margin modeling and demand forecasting at the regional level.
Cost-side pressure is equally significant. Industry-wide exposure to rising raw material and freight costs in 2025 has led manufacturers to increase Wellington boot prices by more than 20 percent in order to maintain margins. This pricing response is not merely a tactical adjustment; it signals a structural shift in the cost base that procurement teams and pricing strategists must incorporate into forward budgets, contract negotiations, and retail price architecture.
Consumer and product development trends are also reshaping the landscape. Eco-friendly materials have featured in roughly half of new product launches for Wellington boots since 2023, driving consumer demand particularly in Europe and North America. This shift is mirrored in broader footwear dynamics, with Wellington-style boots commanding substantial material demand share in consumer footwear and rubber remaining a central substrate. The implication for product teams is clear: sustainability messaging, material substitution, and performance validation are becoming inseparable from commercial competitiveness.
These dynamics are not isolated. Duty changes influence sourcing; sourcing decisions affect material availability and cost; cost pressures affect pricing; pricing interacts with consumer willingness to pay; and consumer preferences increasingly reward material innovation. The report integrates these interdependencies into a coherent analytical narrative so that leadership teams can evaluate second-order effects rather than reacting to single variables in isolation.
Strategic Takeaways for Executive Planning in 2026
As organizations prepare for the 2026 operating year, the Wellington boots market demands a disciplined, evidence-based approach to strategy. Several priorities stand out for executives seeking to align their plans with the market's actual structure and trajectory.
First, sourcing and supply chain strategy must be re-examined in light of evolving duty regimes and freight economics. Companies that rely on single geography sourcing or fixed supplier contracts may face heightened exposure to cost volatility and duty-driven margin compression. Scenario planning that evaluates alternative sourcing paths, inventory buffers, and channel timing can reduce disruption risk and preserve pricing flexibility.
Second, product strategy should account for the growing role of material innovation and performance differentiation. With eco-friendly materials increasingly prevalent in new launches and consumer expectations rising in key regions, product roadmaps that rely solely on legacy constructions may lose relative positioning. Organizations should assess where dual-material construction, weather resistance, chemical resistance, or seamless design can serve as credible differentiators aligned to professional or consumer use cases.
Wellington Boots Market
Third, segmentation discipline is essential. The market's demand is distributed across agriculture, household use, industrial manufacturing, outdoor recreation, and additional applications, each with distinct purchasing behavior and performance requirements. A uniform product or pricing strategy is unlikely to optimize results across these verticals. Leaders should use segmentation insights to tailor product specifications, channel selection, and commercial messaging to the specific operational and emotional drivers within each application group.
Fourth, competitive positioning must be understood in context. The landscape includes companies pursuing craftsmanship-led premium strategies, professional-grade durability narratives, industrial protective applications, and affordable general-use offerings. Understanding where a given organization sits within this spectrum, and how competitors are deploying retail partnerships, product launches, and material innovation, enables more precise strategic choices around brand architecture, channel expansion, and product investment.
Finally, forecast discipline matters. The eight-year projection horizon in the full report is designed to support multi-cycle planning rather than short-term reaction. Organizations that integrate forward demand modeling with cost scenarios and competitive intelligence are better positioned to time capacity investments, rationalize SKU portfolios, and allocate commercial resources where growth probability is highest.
Accessing the Full Intelligence Framework
This overview has outlined the strategic architecture of the Wellington Boots Market research and the decision environment that makes it relevant for 2026 planning. The complete report expands significantly on these themes, providing the detailed market sizing, segmentation breakdowns, regional demand analysis, competitive benchmarking, and scenario-based forecasts needed to translate strategy into execution.
For teams responsible for sourcing, product development, pricing, distribution, or corporate planning, the full study offers the depth required to move from directional awareness to evidence-based action. Given the ongoing influence of tariff structures, raw material economics, and material innovation on both cost and consumer response, organizations that equip themselves with comprehensive market intelligence will be better prepared to manage risk, capture growth, and compete effectively across professional and consumer segments.
The Wellington boots category continues to evolve at the intersection of utility, durability, and consumer lifestyle expectations. In that environment, strategic clarity depends on rigorous analysis, and rigorous analysis depends on complete data. The full PW Consulting report is built to provide exactly that foundation for the decisions ahead.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


