



PW Consulting: Dental Drug Market to Reach $6.8B by 2032, 6.2% CAGR Through 2032

Navigating the Dental Drug Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: The Imperative for Precision Intelligence
The dental pharmaceutical sector is undergoing a structural transformation. For executives, investors, and market strategists, relying on generic healthcare forecasts is no longer sufficient. The Dental Drug Market operates at the intersection of clinical necessity, specialized regulatory pathways, and evolving reimbursement models. Our latest comprehensive market research report is designed to cut through the noise, providing a granular, data-backed roadmap for decision-making throughout the forecast period extending to 2032.
As we enter 2026, the market stands at a pivotal juncture. Following a trajectory of steady growth from 2020 through 2025, the industry is projected to continue its expansion, driven by rising prevalence of dental caries, periodontal diseases, and an aging population demanding restorative and pain management solutions. This research does not merely present historical snapshots; it constructs a forward-looking strategic framework. By synthesizing macroeconomic indicators with micro-level competitive intelligence, we empower stakeholders to allocate capital efficiently, identify white-space opportunities, and anticipate regulatory headwinds before they impact margin structures.
Market Trajectory and Core Growth Dynamics
Understanding the baseline momentum is critical for any strategic plan. Our analysis tracks the market's evolution from a base value of approximately 5,200 million USD in 2020, reflecting a period of recovery and stabilization post-pandemic disruptions. Through 2025, the market has demonstrated resilience, with year-over-year fluctuations reflecting supply chain adjustments and shifting clinical priorities. The current valuation for 2025 stands at 5,850 million USD, indicating a robust recovery and renewed demand for specialized dental pharmaceutical products.
Looking ahead, the forecast period from 2026 to 2032 paints a picture of sustained growth. The market is expected to reach milestone valuations in the coming years, underpinned by a Compound Annual Growth Rate of 6.2 percent. This growth rate is not merely a statistical projection; it represents the compounded effect of increasing dental visit frequencies, the integration of pharmaceutical components into broader dental workflows, and the continuous innovation in pain management and infection control. Stakeholders must recognize that this growth is uneven across categories and geographies. While the aggregate numbers suggest stability, the underlying segments tell a more complex story of divergence, where certain therapeutic classes and delivery mechanisms are outpacing others. Our report deconstructs this complexity, allowing firms to pivot their strategies toward high-velocity pockets rather than chasing legacy volume.
Therapeutic Class and Formulation Landscapes
The diversity of products within the dental drug ecosystem requires a nuanced understanding of therapeutic demand. The market is not monolithic. It spans from immediate clinical interventions to long-term preventive care. Our segmentation analysis dives deep into the performance of various therapeutic classes, revealing which categories are capturing clinician and patient attention.
Dental Market
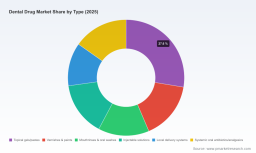
Local anesthetics remain a cornerstone of dental practice, forming a substantial portion of the revenue mix due to the fundamental necessity of pain control during procedures. However, the landscape extends far beyond numbing agents. Antimicrobials and antiseptics play a critical role in infection management, particularly as antibiotic stewardship becomes more stringent. Anti-inflammatories and analgesics continue to see demand, influenced by both clinical efficacy and broader public health conversations around pain relief. Furthermore, preventive and maintenance categories such as fluoride and remineralization agents, desensitizing agents, and hemostatics represent essential components of modern chairside workflows. Each of these classes operates under different pricing pressures, reimbursement rules, and competitive intensities.
Parallel to therapeutic classification, the delivery mechanism is a key battleground for differentiation. The market encompasses a wide array of formulations, including topical gels and pastes, varnishes and paints, mouthrinses and oral washes, injectable solutions, local delivery systems, and systemic oral antibiotics or analgesics. The choice of formulation often dictates the procurement process, the clinical adoption curve, and the manufacturing complexity. For instance, injectable solutions and topical gels require distinct compliance protocols and supply chain capabilities. Manufacturers that can innovate across these formats, or consolidate offerings to simplify procurement for dental practices, hold a distinct advantage. Our report evaluates the relative traction of each formulation type, helping companies understand where to concentrate R&D resources and commercial efforts.
Regional Market Architecture
Geography remains a primary determinant of market potential and risk. The Dental Drug Market exhibits significant variation in maturity, regulatory environment, and purchasing power across regions. North America continues to represent the largest revenue contributor, reflecting a well-established dental infrastructure, high patient awareness, and comprehensive insurance coverage mechanisms. Europe follows as a major market, characterized by diverse national healthcare policies and a strong emphasis on public health outcomes. The Asia Pacific region presents a compelling growth narrative, driven by expanding dental care access, rising disposable incomes, and a growing middle class seeking aesthetic and restorative treatments. Latin America and the Middle East and Africa, while smaller in absolute terms, offer niche opportunities for market entry and brand building in emerging dental ecosystems.
Crucially, regional revenue splits are not static. They are influenced by currency fluctuations, localized manufacturing capabilities, and the degree of integration between dental equipment suppliers and pharmaceutical distributors. A strategy that works in the mature markets of North America may require significant adaptation for the price-sensitive, volume-driven environments found elsewhere. Our analysis provides the contextual depth needed to assess regional attractiveness without relying on one-size-fits-all assumptions.
Competitive Landscape: Who Is Shaping the Market?
The competitive environment is defined by a mix of specialized manufacturers, large diversified conglomerates, and strategic distributors. Market concentration metrics indicate that the top three players hold approximately 35 percent of the market share, while the top five account for roughly 40 percent. This concentration suggests a moderately fragmented landscape where scale matters, but innovation and niche specialization can still secure significant positions.
Sector leaders are actively reshaping their positions through strategic moves and portfolio expansions. Septodont Holding, headquartered in France, stands out as a leading manufacturer focused on local and topical anesthetics, maintaining a strong global distribution footprint. Their recent strategic investment in Balanced Pharma Inc., including a board appointment in early 2025, signals a clear intent to support the development of enhanced dental injection drugs and to influence the next generation of pain management solutions. This move highlights how incumbents are looking beyond organic growth to secure future pipelines.
Dentsply Sirona, based in the United States, integrates pharmaceutical components such as anesthetics, endodontic irrigants, and hemostatic agents directly into broader dental workflows. Their strength lies in the synergy between hardware and consumables, offering practices a unified ecosystem. Henry Schein, also US-based, operates as a major distributor and provider, leveraging an extensive catalog and distribution network to deliver dental anesthetic and pharmaceutical products to a wide client base. Their release of the Dental Supplies Catalog for 2025/2026 in mid-2025, featuring expanded anesthetic offerings, underscores the importance of catalog breadth and accessibility in driving volume.
Other key players further illustrate the diversity of competitive approaches. Ultrdent Products and 3M focus on desensitizing agents, cavity varnishes, and integrated components for restorative and oral care portfolios. Centrix Inc. and Pierrel specialize in dental anesthetics and local formulations for office-based procedures, catering to the practical needs of clinical settings. Huons Global from South Korea and Normon from Spain add geographic depth, manufacturing and distributing anesthetics and related drugs within their respective regions. Balanced Pharma Inc. represents an emerging innovator focused on developing new dental injection drugs and analgesics aimed at reducing opioid use, aligning product development with shifting societal and regulatory expectations around pain management.
Understanding the strategic intent and operational focus of these companies is essential for competitive positioning. Our report profiles these key players, analyzing their product portfolios, geographic reach, and recent activities to help clients anticipate competitor responses and identify partnership or acquisition targets.
Regulatory, Reimbursement, and Operational Headwinds
No strategic analysis of the dental drug market is complete without a rigorous examination of external forces that can alter profitability and access. The regulatory environment is tightening, with direct implications for drug development, approval timelines, and pricing structures. The FDA has published Prescription Drug User Fee Act fee rates for fiscal year 2026, with application fees for drugs requiring clinical data reaching over 4.6 million USD. Such costs raise the barrier to entry for new formulations and incentivize companies to optimize their regulatory strategies or pursue line extensions of existing approved products.
On the reimbursement front, the Medicare Drug Price Negotiation Program has begun to implement negotiated prices for selected Part D drugs starting in 2026, with additional selections announced for applicability in 2028. Medicare beneficiaries are projected to save an estimated 1.5 billion USD in 2026 from the first round of negotiated prices. While dental drugs often fall through the cracks of broad Medicare negotiations, the precedent set by these policies influences payer expectations, hospital and clinic procurement negotiations, and the broader pricing architecture across the pharmaceutical supply chain. Companies must assess how these downstream pricing pressures might eventually cascade into dental-specific channels.
Operational costs are another critical variable. Dental drug manufacturing and distribution involve specialized labor for cartridge filling, quality control, and compliance with regulatory standards in dental clinics and pharmacies. Labor costs and the availability of skilled personnel can impact production scalability and margin stability. Furthermore, the supply of active pharmaceutical ingredients remains a strategic concern. For example, local anesthetics dominate the dental drug segment, driven by API sourcing for lidocaine and related compounds. Volatility in raw material availability or pricing can disrupt supply chains and force companies to maintain higher inventory buffers or diversify sourcing strategies. Our report integrates these operational and regulatory dynamics into a cohesive risk assessment framework, enabling clients to stress-test their business models.
Inside the Report: A Toolkit for Decision Makers
The value of a market research report lies in its actionable utility. Our Dental Drug Market study is structured to serve as a practical toolkit for strategy teams, product managers, and investors. It moves beyond descriptive analytics to provide diagnostic and prescriptive insights.
- Comprehensive Market Sizing and Forecasting: Detailed baseline data and multi-year projections that allow you to benchmark your internal forecasts and align long-term planning with sector-wide trends.
- Segmentation Deep Dives: Granular analysis by region, therapeutic class, and formulation type, highlighting growth rates, revenue contributions, and demand drivers for each segment without the ambiguity of aggregated data.
- Competitive Intelligence Profiles: In-depth company profiles covering product offerings, geographic presence, recent developments, and strategic positioning, enabling you to map the competitive battlefield and identify gaps.
- Regulatory and Reimbursement Analysis: A forward-looking assessment of policy changes, fee structures, and negotiation programs that could impact pricing, market access, and compliance costs.
- Supply Chain and Cost Structure Insights: Examination of labor requirements, raw material dependencies, and manufacturing complexities, providing context for margin analysis and operational planning.
- Strategic Recommendations: Synthesized findings that translate data into actionable guidance for market entry, portfolio optimization, M&A targeting, and risk mitigation.
Strategic Outlook: Positioning for 2026 and the Decade Ahead
As the market progresses through the forecast window, success will depend on agility and precision. The companies that thrive will be those that can balance scale with specialization, navigate an increasingly complex regulatory environment, and align their product portfolios with the evolving clinical and economic priorities of dental practices. Growth will not be uniform; it will be captured by firms that understand where demand is intensifying, which therapeutic classes are gaining clinical preference, and how reimbursement shifts might alter procurement behavior.
Dental Drug Market
This is why high-quality, timely intelligence is indispensable. Our report provides the foundation for making informed decisions in 2026 and beyond. Whether you are evaluating a new product launch, assessing a potential acquisition, refining your geographic expansion plan, or simply seeking to validate your internal assumptions against external reality, this research delivers the clarity required to move with confidence. The data points, segmentation detail, and competitive assessments contained in the full study offer a level of depth that surpasses public information and equips you to anticipate rather than react.
To access the complete analysis, including all segmentation data, detailed company profiles, and proprietary strategic recommendations, we invite you to explore the full report. The Dental Drug Market holds significant promise, but realizing that promise demands more than surface-level observation. It requires a rigorous, evidence-based perspective that our research is designed to deliver.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


