



PW Consulting: LED Street Lighting Market to Hit $13.479B by 2032 with 5.28% CAGR

Navigating the Next Wave of Urban Infrastructure: Strategic Intelligence for the Global LED Street Lighting Market
As municipalities worldwide accelerate infrastructure modernization and sustainability mandates tighten, the global LED street lighting market stands at a critical inflection point. For executives, procurement leaders, and urban planners, understanding the trajectory of this market is no longer optional. It is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 to 2032 and beyond.
Macro Trajectory and Revenue Context
The market has demonstrated consistent expansion over the past five years. Drawing from historical tracking between 2020 and 2025, revenue has climbed steadily from approximately 7.6 billion to nearly 9.4 billion USD. Looking forward, the forecast period positions annual revenue to surpass the 9.8 billion mark in 2026, with continued upward momentum projected through 2032. The compound annual growth rate for this forecast window is estimated at 5.28 percent, reflecting sustained demand drivers including municipal energy retrofit programs, aging infrastructure replacement cycles, and the integration of smart connected controls. These figures establish a clear baseline for capital allocation, partnership evaluation, and long-term portfolio planning. Rather than treating LED street lighting as a passive commodity replacement, organizations must recognize it as a dynamic market segment where technology refresh, regulatory alignment, and operational efficiency converge.
LED Lighting Market
Rising Input Costs and Material Market Realities
Cost volatility in raw materials introduces a layer of operational complexity that cannot be ignored in 2026 procurement strategies. Prices for essential metals and conductive materials have experienced notable pressure. Silver prices have risen sharply over the trailing twelve months, while copper has crossed significant thresholds in early 2026. These movements directly influence component manufacturing, fixture assembly costs, and supply chain pricing structures. For buyers and vendors alike, understanding how material cost fluctuations cascade through bill-of-materials, margin structures, and tender evaluations is essential. Forward-looking procurement requires scenario planning, multi-sourcing strategies, and a clear understanding of which cost drivers are transitory versus structurally embedded in the market.
Regulatory Momentum and Municipal Energy Mandates
Policy and regulatory frameworks continue to shape deployment velocity. In the United States, federal and state-level energy programs project that LED street lighting installations will dominate the majority of lighting installations by 2035, yielding annual energy savings exceeding 569 terawatt-hours. Such projections reinforce the financial case for early adoption and provide long-term visibility for manufacturers and system integrators. Meanwhile, structural shifts in other regions have created parallel opportunities. In Brazil, the transfer of public street lighting assets to municipalities created strong incentives for energy-efficient LED retrofits, particularly in markets facing elevated electricity costs. With a substantial share of municipalities now directly responsible for energy expenditures, the economic mechanics of lighting upgrades have shifted from centralized utility planning to localized budgetary decision-making. These regulatory transitions alter who controls procurement, how payback periods are evaluated, and which financing models gain traction.
What This Research Delivers: Operational Depth for Decision-Makers
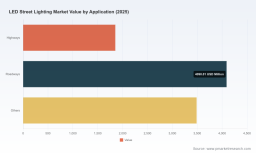
Our market research is structured to move beyond headline figures and deliver operationally relevant intelligence. The publication provides a granular mapping of market segmentation, competitive positioning, and demand drivers across multiple dimensions. Readers will gain clarity on how product architectures are evolving under the broader shift toward LED-dominant installations, including the performance characteristics that municipal buyers now prioritize. The report examines application-specific deployment patterns across roadways, highways, and other municipal and utility contexts, explaining how usage environments influence luminaire specifications, optical requirements, and lifecycle expectations. Regional demand dynamics are contextualized to highlight where infrastructure budgets, electrification goals, and retrofit programs are most concentrated, enabling targeted market entry and expansion strategies. Crucially, the analysis integrates supply-side realities with end-user purchasing behavior, ensuring that revenue forecasts are anchored in market mechanics rather than extrapolated trends.
Competitive Landscape and Strategic Positioning
The market exhibits meaningful concentration among established players, with top-tier firms accounting for a substantial share of total industry revenue. This competitive density rewards companies that can differentiate through performance credentials, control integration, service ecosystems, and regional execution capability. Several core enterprises define the current competitive frontier. Acuity Brands delivers roadway luminaires and integrated smart controls tailored to municipal street and roadway applications. Signify Holding provides connected smart street lighting systems and a broad portfolio of road and street LED luminaires designed for urban infrastructure. Eaton Corporation contributes high-efficacy LED cobrahead and roadway luminaires for municipal street lighting projects, emphasizing reliable illumination performance. Cree Lighting manufactures high-efficiency LED street and roadway fixtures aimed at municipal and transportation applications. LEOTEK specializes in energy-efficient LED street light fixtures and complete citywide upgrade solutions, while Evluma manufactures energy-efficient LED roadway luminaire series for utilities and municipalities. TRT Lighting produces configurable LED street and highway lantern ranges for roadway applications. ZGSM manufactures high-efficacy LED street lights with tool-free maintenance for municipal roads, and Schréder provides full-spectrum outdoor lighting solutions including LED street luminaires for urban infrastructure. Together, these players illustrate a market where hardware performance, smart control interoperability, and municipal service readiness are increasingly decisive.
Recent Product Launches and Innovation Signals
Product introductions in early 2026 underscore the pace of technical refinement and market responsiveness. Evluma launched a new roadway luminaire series featuring modular design, broad lumen packages, high surge protection, and low-glare optics, targeting both utility and municipal applications. ZGSM introduced an updated cobra head LED street light series with high luminous efficacy, asymmetric distribution options, tool-free maintenance, and recognized certification for roads and urban applications. These releases signal several strategic themes. Modularity supports serviceability and component-level upgrades. Thermal and optical refinements address comfort and compliance requirements. Certification and distribution flexibility reduce friction in municipal qualification processes. For competitors and buyers alike, these launches are not isolated events; they are indicators of where performance thresholds are rising and how manufacturers are working to reduce total cost of ownership across installation, operation, and maintenance phases.
Implications for 2026 Corporate Strategy
For organizations operating in or adjacent to this market, the strategic implications are direct and time-sensitive. First, procurement and sourcing strategies must account for material cost volatility, particularly for metals and conductive components that influence fixture economics. Teams should evaluate contract structures, inventory buffers, and supplier diversification to protect margin stability. Second, product and portfolio planning should align with the growing emphasis on efficiency, optical quality, surge resilience, and maintainability. Specifications that once served as differentiators are increasingly becoming baseline expectations in municipal tenders. Third, smart control integration and interoperability are becoming strategic assets. Municipalities and utilities are looking beyond illumination output to network compatibility, remote management, and data-enabled maintenance. Vendors that can credibly support these requirements gain access to broader system-level engagements. Fourth, regional strategy should be informed by asset ownership models and energy cost structures. In markets where municipalities directly control lighting budgets and energy expenditures, the value proposition shifts toward measurable savings, rapid deployment, and lifecycle service support. In regions with centralized utility planning, standardization and compliance credentials may carry greater weight. Finally, competitive positioning requires clarity on whether a company competes on performance leadership, cost efficiency, regional reach, or integrated solutions. The market concentration profile indicates that scale and portfolio breadth remain important, but differentiation in specific application segments and service models can still create defensible positions.
Conclusion: From Observation to Actionable Intelligence
The LED street lighting market is evolving under the combined influence of infrastructure renewal, energy efficiency mandates, material cost dynamics, and rapid product innovation. For leaders tasked with capital planning, product strategy, partnership decisions, and regional expansion, high-level trends are necessary but insufficient. The full 2026 to 2032 forecast, segmentation analysis, competitive profiling, and regulatory context are essential to convert market awareness into executable strategy. PW Consulting's complete market research consolidates these dimensions into a single decision-ready framework, enabling executives to stress-test assumptions, identify priority opportunities, and align investments with the direction of demand. To access the full dataset, detailed segmentation breakdowns, competitive benchmarking, and strategic scenario guidance, we invite you to explore the complete report through our primary research portal. The strategic clarity required for 2026 begins with the right intelligence.
LED Street Lighting Market
For detailed analysis of this topic, please visit the official page: LED Street Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


