



PW Consulting: Blood Bank Information Systems Market to Reach $1,580.8M by 2032, Growing at 7.8% CAGR

Strategic Intelligence for the Next Wave: Inside the Blood Bank Information Systems Market Outlook 2026
The global blood bank information systems market is entering a phase of structural acceleration, driven by tightening regulatory frameworks, the digital transformation of transfusion workflows, and the financial imperative to convert legacy inventory operations into scalable, interoperable platforms. Our newly published market research report, Blood Bank Information Systems Market: Strategic Intelligence for the Next Wave 2026–2032 , maps this transition with executive-grade precision. Covering the historical baseline from 2020 through 2025 and projecting forward to 2032, the study translates complex operational, technological, and compliance forces into a decision-ready architecture for health systems, blood centers, procurement leaders, and investment teams.
For organizations planning cycles in 2026, the difference between reactive procurement and strategic positioning lies in understanding how macro trajectories intersect with grounded, operational realities. This report is engineered to deliver that clarity. Below is a preview of the analytical rigor, structural breakdowns, and competitive intelligence contained within our full dataset.
A Market Reaching an Inflection Point
The industry has demonstrated sustained, compound growth over the past half-decade. From a historical revenue base of approximately 658.5 million USD in 2020, the market advanced through successive years of expansion, reaching 947.0 million USD in 2025. That progression is not merely a function of incremental digitization; it reflects a fundamental re-architecture of how blood is tracked, allocated, tested, and transfused across institutional and regional networks.
Looking ahead, the forecast trajectory indicates continued momentum, with the overall market projected to surpass the 1.5 billion USD threshold by 2032. The implied compound annual growth rate across the 2026–2032 forecast horizon stands at 7.8 percent. While these headline figures provide essential directional context, the strategic value for executives lies in what sits beneath them: the relative weight of deployment models, the pace of institutional adoption, the shifting cost structures associated with cloud architectures, and the compliance-driven procurement triggers that accelerate upgrade cycles.
Regulatory Acceleration as a Procurement Catalyst
Compliance has evolved from a baseline requirement into a dominant force shaping technology investment. In the United States, FDA regulations mandate that blood bank information systems support complete traceability from donor to recipient, eliminating gaps that previously allowed fragmented record-keeping to persist across standalone modules. Across the Atlantic, the European Union’s Substances of Human Origin (SoHO) Regulation introduces expectations for real-time, audit-ready data trails, placing a premium on systems capable of maintaining unbroken lineage documentation under live operational conditions.
These regulatory expectations are not theoretical. Recent industry data indicates that 72 percent of blood centers identify regulatory compliance as the primary driver for upgrading blood bank information systems. That dynamic reframes the purchasing conversation: organizations are no longer evaluating platforms primarily on incremental feature sets, but on their capacity to future-proof audit workflows, integrate with laboratory and electronic health record ecosystems, and withstand jurisdictional scrutiny without operational friction.
Architecture Shifts: From Capital-Seated Infrastructure to Scalable Deployment
A parallel transformation is underway in how these systems are provisioned. Traditional on-premises deployments, once the default model for institutional blood management platforms, are being re-evaluated against cloud-based architectures that reduce upfront capital expenditure while enabling elastic inventory management. Cloud delivery models allow blood centers and hospital networks to scale allocation logic, donor tracking, and inventory visibility without the rigidity of fixed infrastructure.
The strategic implication is nuanced. Lower capital barriers do not automatically translate into faster adoption; they introduce new considerations around data sovereignty, interoperability with legacy EHR environments, and the total cost of ownership across multi-year contracts. Our report examines these trade-offs explicitly, helping decision-makers align deployment strategies with institutional readiness, staffing capacity, and compliance calendars.
Functional Core: What the Systems Actually Do
At the operational level, blood bank information systems are converging around a shared set of functional imperatives, even as vendors differentiate through workflow design, integration depth, and compliance instrumentation. The core capabilities span several interconnected domains:
- Donation management workflows that coordinate scheduling, donor eligibility, collection tracking, and post-donation documentation across distributed intake sites.
- Transfusion service orchestration that links pre-transfusion testing, crossmatch logic, issue controls, and bedside allocation into a closed-loop process designed to reduce error surfaces.
- Inventory control and traceability that reconcile stock levels, expiration management, component segmentation, and quarantine protocols while maintaining donor-to-recipient lineage.
- Regulatory and standards alignment that hardcodes compliance checks, audit-ready reporting, and documentation practices aligned with accreditation bodies and jurisdictional requirements.
- Interoperability and integration that connect blood bank operations with laboratory information systems, hospital EHRs, and regional sharing networks.
Vendors approach these functions from different strategic angles. Some emphasize modular suites that can be deployed incrementally across inventory and point-of-care allocation workflows. Others position transfusion-centric platforms with embedded safety checks and compliance instrumentation built into daily operations. A further cohort structures their offerings around web-accessible blood bank and transfusion service environments designed to standardize pre-transfusion testing, inventory control, and accreditation alignment. Still others embed blood bank functionality inside broader electronic health record platforms, pursuing integrated donor, inventory, and transfusion workflows within a unified clinical ecosystem.
Evaluating these approaches requires more than feature comparison. It requires understanding which architecture maps to an institution’s existing integration maturity, which compliance obligations are most immediate, and which operational pain points are severe enough to justify migration or expansion. The report provides the structured lens required to make that assessment without defaulting to vendor-led narratives.
Competitive Landscape: Concentration, Differentiation, and Recent Moves
Market concentration in this sector remains relatively distributed. Aggregate data indicates that the top three competitors account for roughly 26.8 percent of total market revenue, while the top five capture approximately 34.5 percent. That structure suggests room for specialized differentiation, regional expansion, and workflow-specific positioning, even as larger platforms leverage scale and integration breadth.
Blood Bank Information Systems Market
Several established players define the current competitive frontier. Haemonetics offers a modular blood bank information system portfolio designed to support inventory control, traceability, point-of-care allocation, and safe transfusion workflows. WellSky has built a transfusion blood bank information system with embedded safety checks, EHR and laboratory integration, and compliance tools oriented toward patient safety and operational continuity. SCC Soft Computer provides a web-based blood bank and transfusion service information management environment that incorporates pre-transfusion testing, inventory control, and alignment with AABB and FDA expectations. Mediware Information Systems delivers blood bank information system modules focused on transfusion service management, inventory control, and regulatory compliance. Cerner Corporation approaches the category from within its broader electronic health record platform, pursuing integrated donor, inventory, and transfusion workflows as part of a connected clinical architecture.
Recent activity among these leaders underscores how the market is evolving in practice. In early 2026, WellSky advanced its transfusion platform with a new kits feature focused on inventory and workflow optimization for blood banks, reflecting a continued emphasis on operational efficiency within compliance-oriented environments. Later in the year, SCC Soft Computer participated in a major regional conference in Australia, showcasing its web-based blood bank system and signaling ongoing attention to international deployment contexts and demonstration-led engagement. These moves are representative of broader patterns: the push toward workflow refinement, the emphasis on modular or web-accessible architectures, and the continued relevance of live demonstration and conference-based engagement in a sector where trust, compliance, and operational fit dominate procurement decisions.
Report Scope: What Decision-Makers Will Find Inside
Our full study is built for executives who need more than directional trends. It is structured to support procurement strategy, portfolio planning, competitive positioning, and investment prioritization across the 2026–2032 horizon. The report includes:
- Historical and forecast market sizing from the 2020 baseline through the 2032 projection, with attention to the pace of growth across the forecast window and the inflection points that shape planning assumptions.
- Functional and adoption-oriented segmentation that breaks down how demand distributes across core system types and major application environments, enabling readers to understand where operational concentration lies and which contexts are expanding most rapidly.
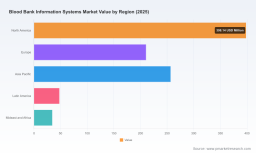
- Regional demand architecture that contextualizes how mature and emerging markets differ in infrastructure readiness, compliance pressure, and procurement cadence, without reducing the analysis to static share rankings.
- Deployment and cost-structure analysis covering the shift toward cloud-based delivery, its implications for capital expenditure, scalability, inventory management, and integration effort.
- Competitive profiling of the leading platforms, including functional positioning, integration strategies, compliance emphasis, and recent product and market activities that signal likely direction.
- Regulatory and reimbursement context that maps FDA traceability expectations, EU SoHO audit-trail requirements, and the compliance-driven upgrade behavior observed across blood centers.
- Strategic implications for 2026 planning that translate the data into procurement timing, vendor evaluation criteria, integration prioritization, and risk management considerations.
Throughout the report, the emphasis remains on usable intelligence rather than abstract sizing. The objective is to help leadership teams determine not only where the market is moving, but how that movement should change operational planning, vendor selection, and compliance readiness in the near term.
Blood Bank Market
Why This Research Matters for 2026 Decisions
The 2026 planning cycle coincides with a convergence of pressures that make blood bank information systems a strategic subject rather than a purely operational one. Regulatory obligations are tightening across major jurisdictions. Cloud delivery is reshaping cost expectations and deployment flexibility. Integration with laboratory and EHR environments is becoming a threshold requirement rather than a differentiator. And compliance-driven upgrade behavior is accelerating procurement conversations that previously unfolded over multi-year horizons.
In that environment, incomplete market intelligence carries real cost. Decision-makers who rely on high-level trends without segment-level clarity may misjudge where adoption is actually concentrated. Teams that evaluate vendors without a structured view of compliance fit, integration debt, and deployment economics may overinvest in features that do not reduce operational risk. Organizations that treat regulatory alignment as an afterthought may find themselves forced into reactive migrations under audit pressure.
Our report is designed to reduce those uncertainties. By combining macro trajectory, functional segmentation, competitive positioning, and compliance context into a single analytical framework, it enables leaders to evaluate architectural choices, procurement timing, and vendor fit with greater confidence. The headline growth trajectory and the 7.8 percent forecast compound rate provide the strategic backdrop; the actionable intelligence lies in the structural breakdowns, adoption patterns, and competitive dynamics that explain how that growth is being generated and where it is likely to concentrate.
Preview, Not Replacement
This article provides a directional lens into the full study, but it cannot substitute for the data depth, comparative tables, and segment-level analysis contained in the complete report. The specific breakdowns that allow procurement teams to map demand concentration, evaluate regional readiness, and benchmark competitive positioning are developed in detail within our published dataset. Those insights are central to building defensible 2026 strategies, and they are best reviewed in the full analytical context.
For executives, analysts, and procurement leaders responsible for blood bank information systems planning, the report offers a structured foundation for evaluating where to invest, what to prioritize, and how to align technology decisions with compliance, interoperability, and operational resilience goals. The market’s next phase will reward organizations that can translate regulatory pressure, deployment flexibility, and integration requirements into disciplined, evidence-based choices. Our research is intended to support exactly that process.
For detailed analysis of this topic, please visit the official page: Blood Bank Information Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


