



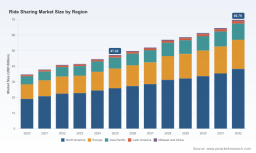
PW Consulting: Ride Sharing Market Hits $47.22B in 2025, Projects 5.85% CAGR to $69.79B by 2032

Strategic Horizons in the Ride Sharing Market: A 2026 Decision-Maker’s Guide to Sustainable Mobility Growth
The global ride sharing ecosystem has evolved from a disruptive novelty into a foundational pillar of modern urban and interurban mobility. As enterprises, municipalities, and mobility operators navigate an era defined by regulatory realignment, autonomous technology maturation, and shifting consumer expectations, the need for precise, forward-looking intelligence has never been more acute. PW Consulting’s newly released ride sharing market research delivers exactly that: a comprehensive, data-grounded examination of an industry poised for sustained expansion through the end of the decade. This introduction outlines the strategic architecture of the study, highlights the macro-level trajectory shaping 2026 corporate planning, and demonstrates how decision-makers can translate analytical depth into actionable competitive advantage.
The Macro Trajectory: Mapping an Industry in Deterministic Expansion
Over the past half-decade, the global ride sharing sector has demonstrated remarkable resilience and consistent upward momentum. Historical valuation data from 2020 through 2025 reveals a market that has systematically outpaced pre-pandemic projections, recovering swiftly from operational disruptions and reinvesting in platform sophistication, fleet modernization, and geographic penetration. The baseline valuation has climbed steadily across successive fiscal periods, establishing a robust foundation for the current forecast cycle.
Looking ahead, our modeling frameworks project a compound annual growth rate of approximately 5.85% across the 2026 to 2032 horizon. This trajectory reflects a confluence of structural drivers: urbanization intensification, the normalization of app-based mobility as a primary transit alternative, and the gradual integration of alternative powertrains into commercial fleets. By the close of the forecast window, the sector is positioned to surpass significant valuation thresholds, reshaping how capital is allocated, how partnerships are structured, and how regulatory compliance is priced into operational models. For executives evaluating market entry, portfolio diversification, or technology investments, these macro indicators provide a reliable compass—but they represent only the starting point. The real strategic differentiation lies beneath the headline figures.
Beyond Headline Numbers: What the Report Delivers for 2026 Strategy
PW Consulting’s research framework is engineered for practitioners who require more than aggregate market sizing. The study dissects the ride sharing value chain through multiple analytical lenses, ensuring that strategic, financial, and operational leaders can extract precise insights tailored to their functional mandates. Rather than presenting static snapshots, the report maps intercurrent dynamics—how pricing architectures interact with regional regulatory environments, how service-tier positioning influences customer retention, and how application-specific demand patterns reshape fleet deployment strategies.
The analytical architecture encompasses detailed breakdowns of market structure across geographic territories, service classifications, and utilization contexts. Each segmentation is examined not in isolation, but as part of an interconnected ecosystem where cross-regional demand shifts, tiered pricing elasticity, and destination-driven utilization patterns collectively inform competitive positioning. Additionally, the study evaluates market concentration dynamics, highlighting how dominant platform architectures shape pricing power, network effects, and barriers to entry. For strategy teams, this means moving beyond speculative trend-chasing toward evidence-based scenario planning that accounts for both near-term operational realities and long-term structural shifts.
Competitive Architecture: Navigating a Consolidated but Dynamic Landscape
The ride sharing sector remains characterized by pronounced concentration, with a small cohort of globally scaled platforms commanding the majority of market share. This consolidation has not eliminated competitive friction; rather, it has elevated the complexity of differentiation. Market leaders must balance scale economies with localized service quality, regulatory adaptability, and technological innovation, while emerging and regional players pursue niche positioning, transparent pricing models, and multi-modal service integration.
Carpooling Market
The report provides granular corporate profiling for pivotal industry participants, examining their operational footprints, strategic priorities, and recent market maneuvers. Uber Technologies, Inc. continues to anchor the global landscape through its expansive network architecture and deepening integration with public-sector mobility procurement, including recently formalized government-wide ride procurement frameworks that extend its footprint into federal civilian and defense ecosystems. Lyft, Inc. has reinforced its North American operational base through sustained platform expansion and capital allocation strategies that signal confidence in long-term urban mobility demand.
Ride Sharing Market
In parallel, regional and specialized operators are redefining competitive boundaries. Bolt Technology OÜ maintains aggressive multi-country expansion, leveraging localized driver incentives and streamlined urban routing. Grab Holdings Limited has entrenched itself as a comprehensive Southeast Asian mobility and services ecosystem, blending ride sharing with adjacent consumer platforms to drive retention and cross-utilization. inDriver has carved a distinct positioning around transparent, user-negotiated pricing and driver-centric earnings structures, appealing to cost-sensitive urban demographics. Via Transportation, Inc. continues to pioneer on-demand microtransit and optimized ride-pooling architectures, addressing gaps in scheduled public transit and suburban connectivity.
The study traces how these players are responding to compounding industry catalysts. Autonomous vehicle integration has transitioned from pilot experimentation to commercial deployment, with driverless ride-hailing services launching in key metropolitan corridors and freight-mobility partnerships accelerating the testing of autonomous integration into existing platform architectures. Simultaneously, public-sector engagement is deepening, as government agencies formalize rideshare procurement pathways, extend membership benefits to workforce populations, and integrate mobility solutions into broader transportation procurement portfolios.
Forces Reshaping the Boardroom: Regulation, Electrification, and Labor Frameworks
No strategic assessment of the ride sharing market would be complete without addressing the regulatory and structural transformations currently recalibrating operational economics. Across major jurisdictions, compliance requirements are evolving from peripheral considerations into core architectural constraints. In North America, environmental mandates are accelerating fleet electrification timelines, with regulatory bodies establishing aggressive zero-emission targets for mobility platforms and tying compliance to measurable greenhouse gas reductions. These requirements are not merely sustainability initiatives; they fundamentally alter capital expenditure planning, vehicle procurement cycles, and total cost of ownership calculations.
Europe’s regulatory trajectory introduces parallel complexity. The impending platform worker directive, scheduled for full implementation in late 2026, will standardize employment benefits and worker protections across digital mobility platforms. This framework is expected to reshape cost structures, influence driver acquisition and retention dynamics, and compel platforms to re-evaluate operational models that rely on highly flexible labor arrangements. For market participants with significant European exposure, compliance readiness and workforce model adaptation will become decisive competitive variables.
At the same time, public-sector mobility procurement is maturing into a structured, long-duration revenue stream rather than a sporadic opportunity. Government-wide purchasing frameworks now encompass multi-year performance periods, integrate civilian and defense mobility needs, and extend ancillary benefits that deepen platform loyalty among institutional user bases. These developments signal a broader paradigm shift: ride sharing is increasingly treated as essential infrastructure, subject to procurement standardization, performance accountability, and integration with public transportation planning.
Why 2026 Demands Precision Intelligence
The 2026 decision environment is defined by simultaneity. Companies must concurrently manage autonomous fleet transition timelines, comply with divergent regional labor and emissions mandates, optimize tiered pricing architectures, and respond to demand patterns that vary sharply across urban, airport, and rural mobility contexts. Aggregate market forecasts alone cannot inform the nuanced trade-offs required at the portfolio, operational, or investment level. Decision-makers need segmentation-level clarity, competitive scenario modeling, and regulatory impact mapping that connect high-level growth trajectories to executable strategic choices.
PW Consulting’s ride sharing market research is constructed to meet that requirement. The study provides a structured reference architecture for evaluating expansion timing, service-tier prioritization, geographic weighting, and partnership strategy. It enables boards and executive teams to assess where concentration dynamics create scale advantages, where regulatory inflection points will alter margin profiles, and where emerging platform models may disrupt incumbent positioning. By synthesizing historical performance, forward-looking growth modeling, and real-time industry catalysts, the report equips stakeholders with the analytical rigor necessary to move from reactive adaptation to proactive strategic design.
Accessing the Full Intelligence Architecture
This introduction offers a strategic preview of the analytical frameworks and industry dynamics underpinning our latest ride sharing market research. The complete study expands far beyond this overview, delivering detailed segmentation analysis, competitive maneuver mapping, regulatory scenario evaluation, and structured insights designed for immediate integration into corporate planning processes. For executives, investors, and strategy leaders seeking to align 2026 initiatives with validated market trajectories, the full report provides the granular intelligence required to convert macro growth signals into disciplined, high-conviction action. We invite decision-makers to access the complete research architecture, where comprehensive data models, detailed corporate profiles, and forward-looking scenario analyses are synthesized into a single, actionable reference for navigating the next phase of mobility market evolution.
For detailed analysis of this topic, please visit the official page: Ride Sharing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


