



PW Consulting: Automatic Checkweighers Reach $397.5M in 2025, Projected to Hit $539.0M by 2032

Strategic Imperatives in the Automatic Checkweighers Market: Navigating Growth Through Precision and Compliance
Executive Overview
In the modern manufacturing and packaging landscape, the automatic checkweigher has evolved from a simple weight verification tool into a critical node within quality assurance ecosystems. As regulatory frameworks tighten and consumer expectations for product consistency rise, the strategic deployment of these systems determines operational efficiency and brand integrity. This article examines the trajectory of the global Automatic Checkweighers Market, highlighting why robust intelligence is essential for decision-makers navigating the period from 2026 through 2032.
Understanding the macroeconomic indicators is the first step, but true competitive advantage lies in decoding the underlying drivers. Our latest research publication dissects these complexities to provide a roadmap for capital allocation, technology adoption, and supply chain optimization. The following analysis outlines the market structure, competitive intensity, and regulatory currents that define this sector, underscoring the necessity of detailed data for precise strategic planning.
Market Trajectory and Economic Foundations
The industry has demonstrated resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend, with the market valuation rising from approximately 320.0 million USD in 2020 to an estimated 397.5 million USD by 2025. This historical performance sets a robust baseline for the forecast period. Looking forward, the market is projected to grow from 423.84 million USD in 2026 to 539.0 million USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5% during the forecast window. While these aggregate figures provide a high-level view of health, they merely scratch the surface of the available intelligence. The value for enterprise strategists lies not in the total number, but in understanding which specific segments are driving this velocity. The report delves into breakouts that reveal where investment yields the highest returns, without exposing the granular percentages publicly. Decision-makers require knowledge of which specific types or applications are outpacing the average growth rate to prioritize their procurement strategies effectively.
Furthermore, the concentration of market power is a critical consideration. With the top three players holding a significant share and the top five commanding an even larger portion of the revenue, the market structure suggests a competitive environment where differentiation is key. Understanding the dominance of these key entities helps purchasers evaluate vendor stability and negotiate terms, while vendors themselves need to know the barriers to entry and the space available for mid-tier players to capture niche opportunities.
Segmentation Dynamics and Strategic Allocation
Effective market strategy requires a nuanced understanding of how demand is distributed across different categories. The landscape is primarily segmented by region, type, and application, each presenting distinct challenges and opportunities for stakeholders. While aggregate revenue is important, the allocation of resources across these dimensions determines the success of implementation.
Regarding regional distribution, North America and Europe have historically maintained substantial presence, reflecting mature industrial bases and stringent regulatory environments. However, the Asia Pacific region presents a compelling growth narrative driven by expanding manufacturing capabilities and increasing adoption of automation technologies. Latin America and the Middle East and Africa, while smaller in current valuation, represent emerging avenues for expansion. Our analysis breaks down the revenue contribution of each geography to identify where infrastructure development is accelerating demand for inline quality control solutions.
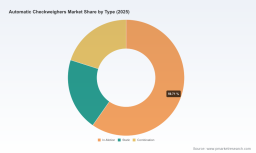
In terms of technology type, the market is divided among In-Motion, Static, and Combination systems. In-Motion checkweighers dominate the revenue landscape, catering to high-speed production lines where downtime is costly. Static systems serve specific applications requiring precise stationary weighing, while Combination systems offer integrated solutions that merge checkweighing with metal detection or other inspection technologies. The choice between these types depends heavily on the production speed and the specific quality control requirements of the facility. The report provides detailed assessments of the revenue split between these types to guide equipment selection based on operational throughput needs.
Application-wise, the Food and Beverage sector remains the primary driver of demand, accounting for the largest share of revenue. This is followed by the Pharmaceutical industry, which demands higher accuracy and compliance standards, along with Consumer Products and other sectors. Each application vertical imposes unique requirements on checkweigher specifications, such as hygienic design for food or data integrity for pharma. By analyzing the revenue distribution across these applications, companies can tailor their marketing efforts and product development roadmaps to the most lucrative verticals. For instance, the pharmaceutical segment may offer lower volume but higher margin potential compared to high-volume food processing.
Strategic Segments Covered in the Full Report:
- By Region: Detailed revenue analysis for North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- By Type: In-depth evaluation of In-Motion, Static, and Combination checkweigher systems.
- By Application: Comprehensive breakdown of Food and Beverage, Pharmaceutical, Consumer Products, and Other sectors.
Competitive Landscape and Key Player Strategies
The market is characterized by the presence of established multinational corporations and specialized manufacturers who compete on precision, integration capabilities, and compliance certifications. The competitive intensity is high, with consolidation trends and strategic partnerships shaping the industry structure. Major players are not only competing on hardware specifications but also on software integration and after-sales support ecosystems.
Automatic Checkweighers Market
Mettler-Toledo International Inc., headquartered in Switzerland, continues to be a dominant force, particularly known for their C-Series and PlusLine dynamic checkweighers. Their strategy heavily emphasizes MID certification and seamless integration with metal detectors and X-ray systems, specifically targeting food packaging quality control. Recent activities, such as their demonstration of C33 PlusLine checkweighers and CM/CX combination systems at Anuga FoodTec 2025, highlight their commitment to enhancing inspection capabilities through integrated solutions.
Ishida Co., Ltd., based in Kyoto, Japan, competes with high-speed multi-lane capabilities through their DACS-GN and DACS-EL series. Their focus on MID approval ensures compliance for the European market, making them a strong candidate for global manufacturers operating under strict regulatory regimes. Similarly, Wipotec-OCS GmbH from Germany offers HC-A and HC-M dynamic checkweighers optimized for high-throughput food and industrial applications. Their March 2026 catalog release emphasizing modular integration for shipping cases underlines their focus on flexibility and logistics efficiency.
Other significant contributors include Anritsu Corporation, whose SSV-h series utilizes force-balance load cells for high accuracy in pharma and food industries, ensuring reliability in sensitive environments. Bizerba SE & Co. KG and Yamato Scale Co., Ltd. provide integrated solutions that blend checkweighing with metal detection and multihead weighing, respectively, catering to snack packaging and high-speed pharmaceutical lines. Minebea Intec GmbH rounds out the European presence with their Essentus performance series, focusing on combination systems for pharma and food safety. Loma Systems, based in the UK, reinforces the importance of compliance with their CW3 dynamic checkweighers, often exhibited alongside metal detection and X-ray solutions at events like Pack Expo East 2026.
Additionally, A&D Company, Limited and Thermo Fisher Scientific Inc. contribute to the ecosystem with high-precision industrial checkweighers and IoT-enabled static and dynamic systems. The presence of Thermo Fisher Scientific highlights a trend toward connectivity and data monitoring in pharmaceutical applications. The report provides a detailed competitive benchmarking of these ten key companies, analyzing their market share, product portfolios, and strategic moves to help stakeholders identify potential partners or competitors.
Regulatory Pressures and Industry Dynamics
Compliance is no longer optional; it is a primary driver of technology adoption. Regulatory mandates such as the Weights and Measures Act and various food safety standards require manufacturers to implement precise weighing solutions to prevent underfilling or overfilling. This regulatory pressure directly fuels demand for MID-certified devices and systems that can log data for audit trails.
Manufacturers are increasingly seeking solutions that offer inline quality control checks while helping them meet compliance requirements without slowing down production lines. For instance, the requirement for Measuring Instruments Directive approval in Europe influences procurement decisions for companies exporting to the EU. The integration of checkweighers with metal detectors and X-ray systems is also becoming standard practice to ensure comprehensive safety compliance, particularly in the food sector.
Recent industry developments underscore this focus on compliance and integration. Mettler-Toledo's emphasis on MID-certified dynamic checkweighers at trade shows demonstrates how vendors are aligning their product launches with regulatory needs. Similarly, Ishida's incorporation of MID approval in their DACS-GN series and Wipotec's support for high-speed applications with precision weighing technology meeting industry standards reflect a broader industry shift. Anritsu's SSV-h series meeting stringent accuracy standards and Loma Systems' design for food safety compliance further illustrate how regulation shapes product specifications. These dynamics suggest that vendors who can certify their equipment and simplify compliance reporting will gain a competitive edge in the coming years.
Strategic Implications for 2026 Decision-Makers
For executives and procurement leaders, the 2026 landscape demands a shift from reactive purchasing to proactive strategic planning. The data indicates that while the market is growing steadily, the value lies in selecting the right technology for the right application. Investing in static systems for high-speed lines may result in bottlenecks, whereas in-motion systems might be overkill for low-volume pharmaceutical batches.
Companies must also consider the total cost of ownership, including integration costs with existing sensors and control systems. The trend toward combination systems suggests that future-proofing facilities with modular equipment that can add metal detection or X-ray capabilities later is a prudent strategy. Furthermore, the geographic shifts in demand imply that supply chain logistics and local service support are critical factors when selecting vendors. Manufacturers operating globally need to ensure their partners have a presence and certification status relevant to their operating regions.
The concentration of the market also implies that negotiating leverage may vary depending on the vendor. Smaller players might offer more customized solutions or faster support, while larger incumbents provide stability and a broader portfolio. Understanding the specific market share and positioning of the top key companies allows businesses to benchmark their current vendors and explore alternatives that might offer better value or technological alignment.
Checkweighers Market
Conclusion and Call to Action
The Automatic Checkweighers Market is poised for steady expansion, driven by regulatory compliance, quality assurance demands, and industrial automation trends. However, navigating this landscape requires more than high-level growth rates. It demands a granular understanding of regional revenue splits, segmentation performance, and competitive maneuvering.
This article has highlighted the key themes and dynamics shaping the industry, but the full strategic picture requires access to comprehensive data. To unlock the complete intelligence necessary for informed decision-making, including detailed segmentation splits, historical data tables, and exhaustive competitor profiling, we invite you to access the full market research report. Equip your organization with the precise data needed to optimize investments and stay ahead in a competitive manufacturing environment.
Access the Full Automatic Checkweighers Market Report Here
For detailed analysis of this topic, please visit the official page: Automatic Checkweighers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


