



PW Consulting: Germanium Market to Hit $403.5M by 2032 with 3.5% CAGR

Strategic Intelligence for a Critical Materials Landscape: Navigating the Germanium Market 2026-2032
In the rapidly evolving landscape of critical minerals, germanium occupies a unique and increasingly precarious position. Once viewed primarily as a niche byproduct of zinc mining, this element has become a linchpin for advanced optics, semiconductor infrastructure, and defense technologies. As supply chains fragment along geopolitical lines and demand curves shift toward high-tech applications, understanding the trajectory of the germanium market is no longer optional for strategic planners—it is imperative.
PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip stakeholders with the actionable intelligence needed to navigate the period from 2026 through 2032. This report goes beyond surface-level statistics to provide a granular analysis of market drivers, regulatory headwinds, and competitive dynamics that will define the industry in the coming years.
Market Trajectory and Structural Resilience
The global germanium market has demonstrated remarkable resilience and growth over the past half-decade. Our analysis traces historical performance from 2020 through 2025, where the market valuation climbed from 260.0 USD Million to 320.0 USD Million. This upward trend reflects sustained demand from fiber optic networks and infrared imaging systems, coupled with tightening supply constraints.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion, albeit with nuanced fluctuations driven by external shocks. The compound annual growth rate is estimated at 3.5 percent, signaling a steady but calculated growth environment. By the end of the forecast horizon in 2032, the market is anticipated to reach a significant valuation, underscoring the long-term viability of germanium-dependent technologies.
However, growth is not uniform. The period between 2027 and 2029 shows notable variance, highlighting how sensitive the market is to geopolitical interventions and supply chain reconfigurations. Stakeholders must understand that while the long-term trajectory is positive, volatility remains a key feature of this landscape. The report dissecting these fluctuations provides the context needed to model risk scenarios accurately.
Geopolitical Dynamics and Supply Chain Realignment
The most profound shift in the germanium market over the last few years has been the weaponization of supply chains. Regulatory frameworks have moved from background concerns to primary market drivers. China, historically the dominant supplier, imposed export licensing controls on germanium in July 2023 and escalated restrictions by banning direct exports to the United States in December 2024. These actions, documented by the U.S. Department of Commerce, have fundamentally altered trade flows and forced a rapid search for alternative sourcing.
In response, the United States has accelerated efforts to domesticate production. U.S. Executive Order 14241 of March 2025 directs the Secretary of Defense to facilitate private investment in domestic mineral production projects, including germanium refining. This policy shift is not merely symbolic; it is backed by tangible financing and strategic intent to reduce reliance on foreign supply. Furthermore, U.S. tariffs on Chinese imports of critical minerals including germanium were imposed in September 2025 to further insulate domestic markets.
These regulatory maneuvers have had immediate price implications. Germanium metal price data from the U.S. Geological Survey Mineral Commodity Summaries 2026 notes a rise from 3,150 USD per kilogram in January 2025 to 5,380 USD per kilogram by October 2025 in Europe. By early 2026, global prices reached 8,597.50 USD per kilogram, representing a dramatic increase from early 2025 levels. Such volatility necessitates robust hedging strategies and long-term supply agreements, details of which are covered extensively in our supply chain risk assessment section.
Competitive Landscape and Strategic Consolidation
The market structure is moderately concentrated, with the top three players holding a significant portion of market share and the top five commanding nearly half of the total revenue. This concentration suggests that pricing power and supply security are heavily influenced by a select group of integrated producers and refiners.
Key companies shaping the landscape include major integrated producers such as Yunnan Chihong Zinc & Germanium Co., Ltd. and Yunnan Lincang Xinyuan Germanium Industry Co., Ltd., both based in China. These entities control extensive operations from mining and purification to refining, offering germanium metal, ingots, and related forms for infrared, fiber optics, and semiconductor applications. Their strategic positioning allows them to react quickly to demand shifts, though regulatory constraints now complicate their access to Western markets.
In the West, Umicore of Belgium stands out as a leading refiner and recycler, specializing in high-purity metal and ingots from secondary sources. This focus on recycling offers a degree of supply insulation against primary mining disruptions. Similarly, Teck Resources Limited in Canada supplies germanium as a byproduct of integrated zinc production, providing metal and oxides for industrial and high-tech uses. In Russia, JSC Germanium remains a primary producer from zinc and coal sources, manufacturing compounds and tetrachloride for electronics and optics.
Specialized refiners and manufacturers also play critical roles. PPM Pure Metals GmbH in Germany and Indium Corporation in the United States refine and recycle germanium for high-purity applications in semiconductors and advanced electronics. AXT, Inc. and 5N Plus Inc. focus on compound semiconductor manufacturing and specialty chemicals, sourcing germanium for wafer production and defense-related optical applications. China Germanium Co., Ltd. rounds out the key players as an integrated producer offering high-purity metal and refined products for electronics and fiber optic sectors.
Recent developments highlight the intensity of strategic maneuvering. In January 2026, the Department of Defense invested 18.1 million USD in Defense Production Act funds to expand zone refining capacity for germanium metal sevenfold at the St. George, Utah facility operated by 5N Plus Inc., targeting optics and satellite solar crystals. In March 2026, Indium Corporation received a New Product Introduction Award for their halogen-free solder paste, signaling innovation in assembly applications. Metallium Limited signed a 10-year offtake agreement with Indium Corporation to supply recovered gallium and germanium from U.S. recycling operations, emphasizing the growing importance of circular supply chains. Additionally, Blue Moon Metals Inc. closed the purchase of Teck's Apex germanium and gallium mine in March 2026, securing a domestic primary supply source.
Segmentation Insights and Application Drivers
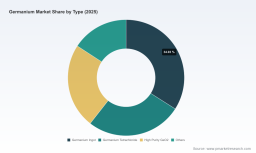
Understanding where demand originates is crucial for targeted investment. The market is segmented by type, application, and region, with each segment exhibiting distinct growth characteristics. Product forms such as germanium ingots, tetrachloride, and high-purity dioxide serve different industrial needs, from semiconductor substrates to optical lens manufacturing.
On the application side, fiber optics remains a dominant consumption channel, driven by global bandwidth expansion and telecommunications infrastructure upgrades. Infrared optics continues to be a critical segment, fueled by defense, thermal imaging, and night vision technologies. Electronics and solar applications represent a growing frontier, particularly as compound semiconductors gain traction in high-efficiency photovoltaic cells and specialized electronic components.
Regional consumption patterns reveal a complex tapestry of demand. While Asia Pacific remains a central hub for manufacturing and consumption, North America and Europe are prioritizing supply chain security and domestic processing capabilities. Latin America and the Middle East and Africa represent emerging opportunities, though their current share reflects developing infrastructure and limited localized refining capacity. The report provides a deep dive into how these regional dynamics interact with trade policies and logistics costs.
Report Content and Operational Utility
This market research is designed as a decision-support tool for executives, procurement managers, and investors. It contains detailed profiles of key companies, analyzing their capacities, strategic focus, and recent operational moves. The competitive landscape section evaluates market share distribution and identifies potential partnerships or M&A opportunities that could reshape the industry.
Readers will find comprehensive segmentation analysis that breaks down revenue contributions by product type and application without exposing sensitive proprietary data until the full report is accessed. The regulatory impact analysis quantifies how export controls and tariffs affect supply chain costs and lead times. Furthermore, the price trend analysis correlates historical data with policy events to forecast potential future scenarios.
Our methodology ensures that all data is cross-verified with industry sources and government publications. The forecast model incorporates multiple variables, including production capacity expansions, recycling rates, and demand elasticity for downstream technologies. This rigorous approach ensures that the insights provided are robust enough to support CAPEX planning, inventory strategy, and market entry decisions.
Germanium Market
Conclusion: The Imperative for Intelligence
As the germanium market navigates a period of historic transformation, information asymmetry will be the primary differentiator between success and stagnation. The convergence of geopolitical tension, technological demand, and supply chain restructuring creates a complex environment where intuition is insufficient. Access to verified, forward-looking data is essential.
PW Consulting's Germanium Market report offers the depth and clarity required to make informed strategic choices in 2026 and beyond. We invite you to explore the full findings, including detailed segmentation data, comprehensive company profiles, and scenario-based forecasts, by visiting our research portal. Secure the intelligence needed to lead in a critical materials market.
Indium Market
For detailed analysis of this topic, please visit the official page: Germanium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


